Rendering basis Render web-normalized sections and canonical supplemental objects exactly. Canonical reviewed JSON is authoritative for web/PDF. Do not OCR or rewrite legal text.
नेपाली मूल पाठ
यस बैंकबाट इजाजतपत्रप्राप्त “क”, “ख” र “ग” वर्गका बैंक तथा वित्तीय संस्थाले प्रदान गर्ने सेवाबारे सर्वसाधारणलाई सुसूचित पार्ने, सो सेवा वापत लिइने शुल्कहरु पारदर्शी रुपमा लिने व्यवस्था गर्न तथा बैंक तथा वित्तीय संस्थाहरु मार्फत वित्तीय साक्षरता अभिवृद्धि गर्ने आवश्यकतालाई दृष्टिगत गरी सर्वसाधारणलाई वित्तीय ग्राहक संरक्षण तथा वित्तीय साक्षरता सम्बन्धी व्यवस्था जारी गरिएकोले सोही बमोजिम गर्नु/गराउनु हुन नेपाल राष्ट्र बैंक ऐन, २०५८ को दफा ७९ ले दिएको अधिकार प्रयोग गरी देहायका निर्देशन जारी गरिएको छ ।
Controlled English translation
Considering the need to inform the public about services provided by Class “A”, “B” and “C” banks and financial institutions licensed by this Bank, to ensure transparent charging of fees for such services, and to enhance financial literacy through banks and financial institutions, the following directives on financial consumer protection and financial literacy are issued in exercise of the authority conferred by Section 79 of the Nepal Rastra Bank Act, 2058.
इजाजतपत्रप्राप्त संस्थाले ग्राहकलाई प्रदान गर्ने सेवासँग सम्बन्धित सबै प्रकारका विवरण सार्वजनिक रुपमा जानकारी गराउनुपर्नेछ । ग्राहकले सेवा लिँदा सेवा तथा उपकरण, शुल्क, कमिशन, ब्याजदर, जरिवाना, हर्जाना, खाता बन्द गर्ने/नवीकरण गर्ने प्रक्रिया, कार्ड तथा विद्युतीय उपकरणको प्रयोग र जोखिम, ग्राहकले अवलम्बन गर्नुपर्ने सतर्कता लगायतका विषय स्पष्ट रुपमा उपलब्ध गराउनु पर्नेछ ।
(क) वित्तीय सेवा, सबै प्रकारका खाता तथा कर्जा र वित्तीय उपकरणसम्बन्धी जानकारी सुरक्षित वित्तीय निर्णय गर्न उपयुक्त हुने गरी उपलब्ध गराउनु पर्नेछ ।
(ख) सरल र स्पष्ट भाषामा लिखित जानकारी गराउँदा कम्तीमा विभिन्न प्रकारका खाता, शुल्कको आधार, बैंकिङ उपकरणका प्रक्रिया/कार्यविधि, खाता बन्द/नवीकरण, ब्याजदर गणना विधि, अग्रिम भुक्तानी शुल्क, समयमै भुक्तानी नगरेको कारवाही, विलम्ब शुल्क/जरिवाना/हर्जाना, विद्युतीय कार्ड सञ्चालन कार्यविधि र ग्राहक सतर्कता समावेश गर्नु पर्नेछ ।
(ग) ग्राहकले आफ्नो कारोबारसम्बन्धी जानकारी निःशुल्क रुपमा लिन सक्ने व्यवस्था गर्नु पर्नेछ ।
(घ) Internet Banking तथा Mobile Application मा कर्जा तथा निक्षेपको ब्याजदर स्पष्ट देखिने व्यवस्था गर्नु पर्नेछ ।
(ङ) Core Banking System मा कारोबार प्रविष्ट गर्दा कारोबारको विवरण स्पष्ट बुझिने गरी narration लेख्नु पर्नेछ; यस प्रयोजनका लागि alpha-numeric code मात्र प्रयोग गर्न पाइने छैन ।
(च) ग्राहकबाट लिइने विभिन्न शुल्क तथा ब्याजदरसम्बन्धी विवरण इ.प्रा. निर्देशन १५ बमोजिम आफ्नै वेबसाइटमा प्रकाशित गर्नु पर्नेछ ।
Controlled English translation
A licensed institution shall publicly disclose all material information relating to services provided to customers. Information shall clearly cover services and instruments, fees, commissions, interest rates, penalties, charges for delayed payment, account closure/renewal procedures, cards and electronic instruments, associated risks and precautions to be taken by the customer.
(a) Information on financial services, all types of accounts and credit, and financial instruments shall be made available so as to support sound financial decisions.
(b) Written information in simple and clear language shall at least cover account types, basis of charges, procedures for banking instruments, account closure/renewal, method of interest calculation, prepayment charges, consequences of non-payment on time, late fees/penalties, electronic-card procedures and customer precautions.
(c) Customers shall be able to obtain information relating to their transactions free of charge.
(d) Lending and deposit interest rates shall be clearly displayed in Internet Banking and Mobile Applications.
(e) When a transaction is entered in the Core Banking System, the narration shall clearly describe the transaction; alpha-numeric codes alone shall not be used for this purpose.
(f) Details of fees and interest rates charged to customers shall be published on the institution’s website in accordance with Directive No. 15.
(क) ग्राहकलाई उपलब्ध गराइने सेवा सम्बन्धी जानकारी वा सूचना सरल र स्पष्ट भाषामा हुनु पर्नेछ ।
(ख) ग्राहकसँग कारोबारमा प्रयोग हुने कागजातहरु नेपाली भाषामा उपलब्ध हुने व्यवस्था गर्नु पर्नेछ । अन्तर्राष्ट्रिय कारोबारसँग सम्बन्धित कागजातहरु आवश्यकताअनुसार अंग्रेजी भाषामा समेत तयार गर्न सकिनेछ ।
Controlled English translation
(a) Information or notices relating to services made available to customers shall use simple and clear language.
(b) Documents used in transactions with customers shall be made available in Nepali. Documents relating to international transactions may also be prepared in English as necessary.
(क) संस्थाले प्रवाह गर्ने सूचना वा जानकारी सर्वसाधारण ग्राहकले सजिलै बुझ्ने र पढ्न सक्ने हुनु पर्नेछ ।
(ख) सर्वसाधारणमा भ्रम सिर्जना हुन सक्ने कुनै पनि प्रकारको विज्ञापन गर्न/गराउन पाइने छैन ।
(ग) सूचनाको हकसम्बन्धी ऐन, २०६४ बमोजिम माग भएको सूचना उपलब्ध गराउन, माग गरिएका सूचनाको अभिलेख राख्न तथा प्रत्येक तीन महिनामा ऐनबमोजिमको सूचना अध्यावधिक गरी प्रकाशन गर्नुपर्नेछ ।
(घ) मुख्य तथा शाखा/प्रदेश कार्यालयमा सूचनाको हकसम्बन्धी ऐनबमोजिम सूचना अधिकारी तोकी सोको विवरण सार्वजनिक गर्नुपर्नेछ ।
Controlled English translation
(a) Information disseminated by the institution shall be easy for the general public/customer to understand and read.
(b) No advertisement that may mislead the public shall be made.
(c) Information requested under the Right to Information Act, 2064 shall be provided, records of requests maintained, and the information required by the Act updated and published every three months.
(d) Information Officers shall be designated at the head office and relevant branch/provincial offices in accordance with the Right to Information Act and their details made public.
ज्येष्ठ नागरिक, अपाङ्ग र साक्षर नभएका व्यक्तिलाई विशेष प्राथमिकता दिई सहज रुपमा बैंकिङ सुविधा उपलब्ध गराउन बैंक तथा वित्तीय संस्थाले विशेष काउण्टर तोकी सेवा दिनु पर्नेछ । साथै, स्थानीय तहमा ५ वा सोभन्दा बढी शाखा रहेका स्थानमा कम्तीमा एक शाखा र एटिएम सञ्चालन भएको स्थानमा १ (एक) एटिएम अपाङ्गमैत्री बनाउनु पर्नेछ ।
अपाङ्गता भएका व्यक्तिलाई ATM, Mobile Banking, Internet Banking जस्ता वित्तीय सेवाहरु व्यक्ति स्वयंले प्रयोग गर्न सक्षम रहने यकिन गरी उपलब्ध गराउनु पर्नेछ ।
Controlled English translation
Banks and financial institutions shall give special priority to senior citizens, persons with disabilities and illiterate persons and provide easy banking facilities through designated special counters. In a Local Level where the institution has five or more branches, at least one branch, and where ATMs are operated, at least one ATM, shall be made accessible to persons with disabilities.
Financial services such as ATM, Mobile Banking and Internet Banking shall be made available to persons with disabilities in a manner ensuring that the person can independently use the service.
ग्राहकसँग वित्तीय सेवाको लागि सम्झौता गर्दा सो सम्झौतामा उल्लिखित शुल्क, ब्याजदर र शर्तहरुमा परिवर्तन हुँदा इजाजतपत्रप्राप्त संस्थाले सम्बन्धित ग्राहकलाई जानकारी गराउनु पर्नेछ । सार्वजनिक रुपमा जानकारी गराउनुपर्ने अवस्थामा राष्ट्रियस्तरका संस्थाले राष्ट्रिय दैनिक र क्षेत्रीयस्तरका संस्थाले क्षेत्रीय/जिल्लास्तरका पत्रिकामार्फत सार्वजनिक गर्नु पर्नेछ ।
Controlled English translation
Where fees, interest rates or terms stated in an agreement for a financial service change, the licensed institution shall inform the concerned customer. Where public notice is required, a national-level institution shall publish through a national daily and a regional-level institution through a regional/district-level newspaper.
(क) खाता खोल्दा, चेक जारी गर्दा (Good for Payment चेक समेत), Stop Payment गर्दा, मौज्दात प्रमाणित गर्दा, खाता सञ्चालन/बन्द गर्दा, स्टेटमेन्ट दिँदा, विशेष रकम खातामा जम्मा गर्दा र e-banking सेवा प्रदान गर्दा न्यूनतम/वास्तविक लागतभन्दा बढी शुल्क लिन पाइने छैन ।
(ख) निष्क्रिय खाता सक्रिय गराउँदा शुल्क लिन पाइने छैन ।
(ग) न्यूनतम मौज्दातभन्दा कम भएको कारणले मौज्दात रकम कट्टा गरी मौज्दात घटाउन पाइने छैन; न्यूनतम मौज्दात रकममा समेत तोकिएको ब्याज प्रदान गर्नु पर्नेछ ।
(घ) उपर्युक्त बाहेकका सेवाको शुल्कबारे ग्राहकलाई पूर्व जानकारी गराउनु पर्नेछ ।
(ङ) नेपाली मुद्रामा विद्युतीय कार्ड जारी गर्दा सुरुमा लिने शुल्क बाहेक कार्डको अवधि समाप्त नभएसम्म नवीकरण शुल्क लिन पाइने छैन ।
Controlled English translation
(a) Charges for account opening, cheque issuance (including Good for Payment cheques), Stop Payment, balance certification, account operation/closure, statements, special deposits and e-banking services shall not exceed the minimum/actual cost permitted by the source.
(b) No fee shall be charged to reactivate a dormant account.
(c) An account balance shall not be reduced merely because it falls below the minimum balance; prescribed interest shall also be provided on the minimum-balance amount.
(d) Customers shall be informed in advance of charges for services other than those stated above.
(e) For an electronic card issued in Nepali currency, no renewal charge shall be collected until the card’s validity expires, apart from the initial issuance charge.
(क) चेक, बिल, पे-अर्डर लगायतका वित्तीय उपकरणबाट आफ्नो खातामा रकम जम्मा गर्दा त्यस्तो उपकरणको Clearing सम्पन्न नभएसम्म रकम ग्राहकको खातामा जम्मा गर्न/गराउन पाइने छैन । कारोबारमा कुनै शुल्क लाग्ने भए अग्रिम जानकारी दिई ग्राहकको खाताबाट मात्र लिनु पर्नेछ ।
(ख) ग्राहकले प्राप्त चेक खातामा जम्मा गर्न प्रस्तुत गर्दा सम्बन्धित खातामा पर्याप्त रकम भएमा अन्य कुनै कारणले चेक जम्मा हुन नसकेमा चेक प्रस्तुत गर्ने ग्राहकको खाताबाट शुल्क वा रकम लिन पाइने छैन ।
(ग) खातामा मौज्दात पर्याप्त भई भुक्तानी नहुने चेक प्रस्तुत भएको अवस्थामा एकीकृत निर्देशनको सम्बन्धित चेक-अनादर/कालोसूची व्यवस्था लागू गरी ग्राहकलाई लिखित सूचना दिनुपर्नेछ ।
Controlled English translation
(a) Where a cheque, bill, pay order or other financial instrument is deposited into an account, the amount shall not be credited before completion of Clearing. Any applicable charge shall be disclosed in advance and debited only from the customer’s account.
(b) Where a customer presents a cheque for deposit and sufficient funds exist in the relevant account, no fee or amount shall be charged to the presenting customer merely because the cheque cannot be credited for another reason.
(c) Where a cheque presented for payment is not paid despite sufficient balance, the applicable cheque-dishonour/blacklisting provisions of the Unified Directives shall be followed and the customer informed in writing.
बैंक तथा वित्तीय संस्थाले कर्जा प्रवाह गर्दा देहायका व्यवस्थाहरुको अधीनमा रही प्रशासनिक सेवा शुल्क, अग्रिम भुक्तानी शुल्क तथा प्रतिबद्धता शुल्क लिन सक्नेछन् ।
तर, आफ्नै मुद्दती रसिदको धितोमा कर्जा प्रवाह गर्दा कुनै पनि किसिमको शुल्क लिन पाइने छैन ।
(क) कर्जा नीति निर्देशिका (Credit Policy Guidelines) तथा कुनै पनि प्रकारको Product Paper मा प्रशासनिक सेवा शुल्क, अग्रिम भुक्तानी शुल्क तथा प्रतिबद्धता शुल्क सम्बन्धी व्यवस्था स्पष्ट रुपमा उल्लेख गर्नुपर्ने छ ।
(ख) कर्जा प्रवाह गर्दा लिने सेवा शुल्क, अग्रिम भुक्तानी शुल्क र प्रतिबद्धता शुल्क बाहेक अन्य कुनै पनि शुल्क लिन पाइनेछैन । कर्जासँग सम्बन्धित सम्पूर्ण लागत ब्याजदरमै नै प्रतिविम्बित हुन पर्नेछ ।
(अ) इजाजतपत्रप्राप्त “क”, “ख” र “ग” वर्गका बैंक तथा वित्तीय संस्थाले कर्जा स्वीकृति गर्दा सेवा शुल्क वापत क्रमशः अधिकतम ०.७५ प्रतिशत, १.०० प्रतिशत, १.२५ प्रतिशतसम्म मात्र सेवा शुल्क लिन पाइनेछ ।
तर, प्रतिबद्धता शुल्क र नवीकरण हुने प्रकृतिका कर्जामा लिने नवीकरण शुल्कको हकमा माथि उल्लिखित सेवा शुल्कको अधिकतम २० प्रतिशतसम्म तथा देहाय अनुसार अग्रिम भुक्तानी शुल्क वा ऋणीले बैंक परिवर्तन गर्दा लिने कर्जा स्वाप शुल्क लिन यस व्यवस्थाले बाधा पुर्याएको मानिने छैन :-
क) कर्जाको अग्रिम भुक्तानी शुल्क: कर्जा प्रवाह भएको २ वर्ष भित्र कर्जाको अग्रिम भुक्तानी भएमा खण्ड (अ) मा उल्लिखित सेवा शुल्कको अधिकतम शत प्रतिशतसम्म, २ वर्ष देखि ५ वर्ष भित्र कर्जा चुक्ता भएमा खण्ड (अ) मा उल्लिखित सेवा शुल्कको अधिकतम ५० प्रतिशतसम्म र ५ वर्ष भन्दा पछि कर्जा चुक्ता भएमा माथि उल्लिखित सेवा शुल्कको अधिकतम २० प्रतिशतसम्म ।
ख) कर्जा स्वाप शुल्क: कर्जा प्रवाह भएको २ वर्ष भित्र बैंक परिवर्तन गरेमा बक्यौता रकममा खण्ड (अ) मा उल्लिखित सेवा शुल्कको अधिकतम शत प्रतिशतसम्म, २ वर्ष देखि ५ वर्ष भित्र बैंक परिवर्तन गरेमा बक्यौता रकममा खण्ड (अ) मा उल्लिखित सेवा शुल्कको अधिकतम ५० प्रतिशतसम्म र ५ वर्ष पछि बैंक परिवर्तन गरेमा बक्यौता रकममा खण्ड (अ) मा उल्लिखित सेवा शुल्कको अधिकतम २० प्रतिशतसम्म ।
ग) इजाजतपत्रप्राप्त संस्थाले स्थिर ब्याजदरमा प्रवाहित कर्जाको हकमा कर्जा प्रवाह भएको २ वर्षभित्र तथा ग्रेस अवधि प्रदान गरी प्रवाह गरेको परियोजना कर्जाको हकमा परियोजना सञ्चालनमा आएको २ वर्षसम्म कर्जाको अग्रिम भुक्तानी वा कर्जा स्वाप भएको अवस्थामा यस व्यवस्थाको खण्ड (क) मा उल्लिखित शुल्कको अतिरिक्त थप १ प्रतिशत अग्रिम भुक्तानी शुल्क वा कर्जा स्वाप शुल्क लिन बाधा पुगेको मानिने छैन ।
(आ) स्थिर ब्याजदरमा प्रवाह भएका आवधिक कर्जाको हकमा ऋणीसँगको सहमतिमा कर्जा स्वीकृति पत्रमा उल्लेख भएबमोजिम खण्ड (अ) मा उल्लिखित सेवा शुल्कको शत प्रतिशत अग्रिम भुक्तानी शुल्क वा स्वाप शुल्क लिन सकिने छ ।
(इ) लघुवित्त वित्तीय संस्थाहरुलाई विपन्न वर्ग कर्जा प्रवाह गर्दा ०.५० प्रतिशतभन्दा बढी सेवा शुल्क लिन पाइने छैन ।
(ई) कर्जाको सीमा वृद्धि गरिएमा वृद्धि भएको रकममा मात्र तोकिएको सीमाभित्र रही सेवा शुल्क लिन सकिनेछ । किस्तामा भुक्तानी हुने मध्यम तथा दीर्घकालीन कर्जामा कर्जाको अवधिभर Review charge लगायत अन्य कुनै पनि शीर्षकमा शुल्क लिन पाइने छैन ।
(उ) माथि उल्लेख भएका बाहेक अन्य जुनसुकै शीर्षकमा शुल्क लिएको वा तोकिएको सीमा भन्दा बढी शुल्क लिएको पाइएमा सो शुल्कमा १० प्रतिशत थप गरी ग्राहकको खातामा जम्मा गर्नु पर्नेछ ।
(ग) कर्जा प्रवाह गर्दा लिने प्रशासनिक सेवा शुल्क, अग्रिम भुक्तानी शुल्क र प्रतिबद्धता शुल्कको दर, प्रक्रिया तथा गणना विधिको सम्बन्धमा कर्जा सम्झौतापत्रमा स्पष्ट रुपमा उल्लेख गर्नुपर्ने छ ।
(घ) बैंक तथा वित्तीय संस्थाले एउटै प्रकारको कर्जा प्रवाह गर्दा विभिन्न ग्राहकसँग लिने प्रशासनिक सेवा शुल्क, अग्रिम भुक्तानी शुल्क र प्रतिबद्धता शुल्कमा ०.२५ प्रतिशत बिन्दु भन्दा बढीले फरक पार्न पाइने छैन ।
(ङ) ग्राहकले कर्जाको लागि निवेदन दिए पश्चात् कर्जा स्वीकृतिको प्रक्रिया आरम्भ गर्दाको बखत प्रशासनिक सेवा शुल्क लिन सक्नेछन् । तर, कर्जा अस्वीकृत भएको अवस्थामा यस्तो शुल्क ग्राहकको खातामा फिर्ता गरिदिनु पर्नेछ ।
(च) इजाजतपत्रप्राप्त संस्थाले आफ्ना ग्राहकहरुलाई अन्य संस्था/निकाय मार्फत सेवा लिने सन्दर्भमा सो सेवा वापत त्यस्ता संस्था/निकायहरुलाई भुक्तानी गर्नुपर्ने लागत भन्दा बढी हुने गरी सेवा शुल्क असुल गर्न पाइने छैन ।
उदाहरणको लागि ग्राहकको सम्बन्धमा कर्जा सूचना प्राप्त गर्दा वा कालोसूचीमा सूचीकृत गर्दा वा सो सूचीबाट हटाउँदा लिइने शुल्क कर्जा सूचना केन्द्रले लिने शुल्क भन्दा बढी हुने गरी असुल गर्न पाइने छैन । त्यसैगरी धितो मूल्याङ्कन वापत लिइने शुल्क, बीमा शुल्क लगायत तेस्रो पक्षले लिने शुल्कहरु सेवा प्रदायकले लिने भन्दा बढी हुने गरी लिन पाइने छैन ।
तर इलेक्ट्रोनिक माध्यमबाट हुने चेक क्लियरिङका सम्बन्धमा रु. २ लाख भन्दा कम रकमको चेक क्लियरिङ कारोबारमा सम्बन्धित बैंक तथा वित्तीय संस्थाले आफ्ना ग्राहकहरुसँग कुनै किसिमको शुल्क लिन पाइने छैन ।
(छ) ग्राहकले आफ्नो स्वीकृत कर्जा सीमाको वार्षिक औसत ६० प्रतिशतभन्दा कम रकम उपयोग गरेमा कम हुने रकममा मात्र निश्चित दरले प्रतिबद्धता शुल्क लिन सक्नेछन् (जस्तै, औसतमा ३५ प्रतिशत मात्र उपयोग गरेको भए उपभोग नगरेको २५ प्रतिशतमा मात्र प्रतिबद्धता शुल्क लिन) । तर, उपरोक्तमा उल्लिखित शुल्क अग्रिम रुपमा लिन पाइने छैन । आवधिक कर्जाको हकमा स्वीकृत कर्जा सीमाभन्दा कम उपयोग गरेको अवस्थामा उपयोग नगरेको रकममा मात्र एकपटकका लागि प्रतिबद्धता शुल्क लिन सकिनेछ ।
(ज) रु. ५० लाखसम्मको सीमामा कायम भएको जुनसुकै प्रकारको कर्जा भुक्तानी गर्दा अग्रिम भुक्तानी शुल्क लाग्ने छैन । सो सीमाभन्दा बढीको कर्जाको हकमा कर्जा लिँदाको बखत तोकिएको शर्त वा ब्याजदर थप/परिवर्तन भएको कारण ऋणीले अर्को बैंक तथा वित्तीय संस्थामा कर्जा भुक्तानी गरेमा अग्रिम भुक्तानी गरे वापत कुनै किसिमको शुल्क लिन पाइने छैन ।
(झ) परियोजना कर्जाको हकमा कर्जा लिँदाको बखत ऋणीसँग गरिएको सम्झौतामा उल्लिखित ब्याजदर लगायतका अन्य शर्तहरु ऋणीको सहमति बिना बैंकले एकतर्फी रुपमा थप/परिवर्तन गरेको कारणले ऋणीले कर्जा अग्रिम रुपमा चुक्ता गर्न चाहेमा त्यस्तो अग्रिम भुक्तानी वापत कुनै किसिमको शुल्क लिन पाइने छैन ।
Controlled English translation
Banks and financial institutions may charge administrative service fees, prepayment charges and commitment fees when extending credit, subject to the following provisions.
However, no fee of any kind shall be charged when credit is extended against the institution’s own fixed-deposit receipt.
(a) The Credit Policy Guidelines and any type of Product Paper shall clearly state the provisions relating to administrative service fees, prepayment charges and commitment fees.
(b) No fee other than the service fee, prepayment charge and commitment fee charged when extending credit shall be collected. All costs relating to the credit shall be reflected in the interest rate.
(A) Class “A”, “B” and “C” licensed banks and financial institutions may, when approving credit, charge service fees of not more than 0.75 percent, 1.00 percent and 1.25 percent respectively.
However, in the case of a commitment fee and the renewal fee charged on renewable credit, nothing in this provision shall prevent charging up to 20 percent of the above service fee and, as follows, a prepayment charge or a loan-swap charge where the borrower changes banks:
(a) Prepayment charge: where credit is prepaid within two years after disbursement, up to 100 percent of the service fee referred to in paragraph (A); where the credit is repaid between two and five years, up to 50 percent of that service fee; and where it is repaid after five years, up to 20 percent of that service fee.
(b) Loan-swap charge: where the borrower changes banks within two years after disbursement, up to 100 percent of the service fee referred to in paragraph (A) on the outstanding amount; where the borrower changes banks between two and five years, up to 50 percent; and where the borrower changes banks after five years, up to 20 percent.
(c) In the case of credit extended at a fixed interest rate, where the credit is prepaid or swapped within two years after disbursement, and in the case of project credit extended with a grace period, where the credit is prepaid or swapped within two years after the project comes into operation, nothing in this provision shall prevent charging, in addition to the charge referred to in paragraph (a), an additional prepayment charge or loan-swap charge of 1 percent.
(B) In the case of term credit extended at a fixed interest rate, with the borrower’s consent, a prepayment charge or swap charge equal to 100 percent of the service fee referred to in paragraph (A) may be charged as stated in the credit approval letter.
(C) A service fee exceeding 0.50 percent shall not be charged when extending deprived-sector credit to a microfinance financial institution.
(D) Where a credit limit is increased, a service fee may be charged only on the increased amount and only within the prescribed limit. For medium- and long-term credit repayable in instalments, no fee shall be charged during the credit period under any heading such as Review Charge.
(E) Where a fee is collected under any heading other than those stated above, or above the prescribed limit, the amount of such fee plus an additional 10 percent shall be credited to the customer’s account.
(c) The credit agreement shall clearly state the rates, procedures and calculation methods relating to the administrative service fee, prepayment charge and commitment fee charged when extending credit.
(d) When a bank or financial institution extends the same type of credit, the difference among the administrative service fee, prepayment charge and commitment fee charged to different customers shall not exceed 0.25 percentage point.
(e) An administrative service fee may be charged when the credit-approval process commences after a customer submits a credit application. However, where the credit is rejected, that fee shall be refunded to the customer’s account.
(f) Where a licensed institution causes its customer to obtain a service through another institution/body, it shall not collect from the customer a service fee exceeding the cost payable to that institution/body for the service.
For example, the fee collected for obtaining credit information, listing a customer on the blacklist or removing the customer from the blacklist shall not exceed the fee charged by the Credit Information Centre. Likewise, charges for collateral valuation, insurance and other third-party services shall not exceed the amount charged by the service provider.
However, for cheque-clearing transactions through electronic means involving a cheque amount of less than NPR 200,000, the concerned bank or financial institution shall not charge its customer any fee.
(g) Where a customer uses, on an annual average basis, less than 60 percent of the approved credit limit, a commitment fee at a specified rate may be charged only on the shortfall (for example, where only 35 percent is used on average, the commitment fee may be charged only on the unused 25 percent). Such fee shall not be collected in advance. In the case of term credit, where the approved credit limit is underutilised, a commitment fee may be charged once only on the unused amount.
(h) No prepayment charge shall apply when repaying any type of credit within a limit of NPR 5 million. For credit above that limit, where the borrower repays the credit to another bank or financial institution because a condition or interest rate specified when the credit was taken has been added to or changed, no fee shall be charged for such prepayment.
(i) In the case of project credit, where the bank unilaterally adds to or changes the interest rate or other terms stated in the agreement entered into when the credit was taken without the borrower’s consent, and the borrower wishes to repay the credit early for that reason, no fee of any kind shall be charged for such prepayment.
(क) ग्राहकबाट प्राप्त गुनासो/उजुरी समाधान गर्न दायित्व सम्बन्धित बैंक वा वित्तीय संस्थाको हुनेछ र गुनासो/उजुरीको समाधानको लागि संस्थाले छुट्टै कक्षको व्यवस्था गर्नुपर्नेछ ।
(ख) सेवाग्राहीलाई सहज हुने गरी “सूचना तथा गुनासो सुनुवाई डेस्क” स्थापना गरी वरिष्ठ व्यवस्थापक वा सोभन्दा माथिको अधिकारीलाई गुनासो सुन्ने अधिकारी तोक्नु पर्नेछ । अधिकारीको नाम, पद, फोन, मोबाइल र इमेल वेबसाइटको अग्र भागमा राख्नु पर्नेछ ।
(ग) उपभोक्ताको गुनासो सुनुवाईका लागि हटलाइनसमेतको व्यवस्था गर्नु पर्नेछ ।
(घ) बैंक तथा वित्तीय संस्थाका कामकारवाही सम्बन्धी गुनासो सहज बनाउन नेपाल राष्ट्र बैंकको गुनासो पोर्टल gunaso.nrb.org.np को लिंक वेबसाइटमा राख्नु पर्नेछ ।
(ङ) ग्राहकको गुनासो सुनुवाई सम्बन्धी नीतिगत व्यवस्था बनाई लागू गर्नुपर्नेछ र यसको लिंक वेबसाइटको अग्रभागमा राख्नु पर्नेछ; कुन तहबाट गुनासो सम्बोधन हुने हो सो समेत उपलब्ध गराउनु पर्नेछ ।
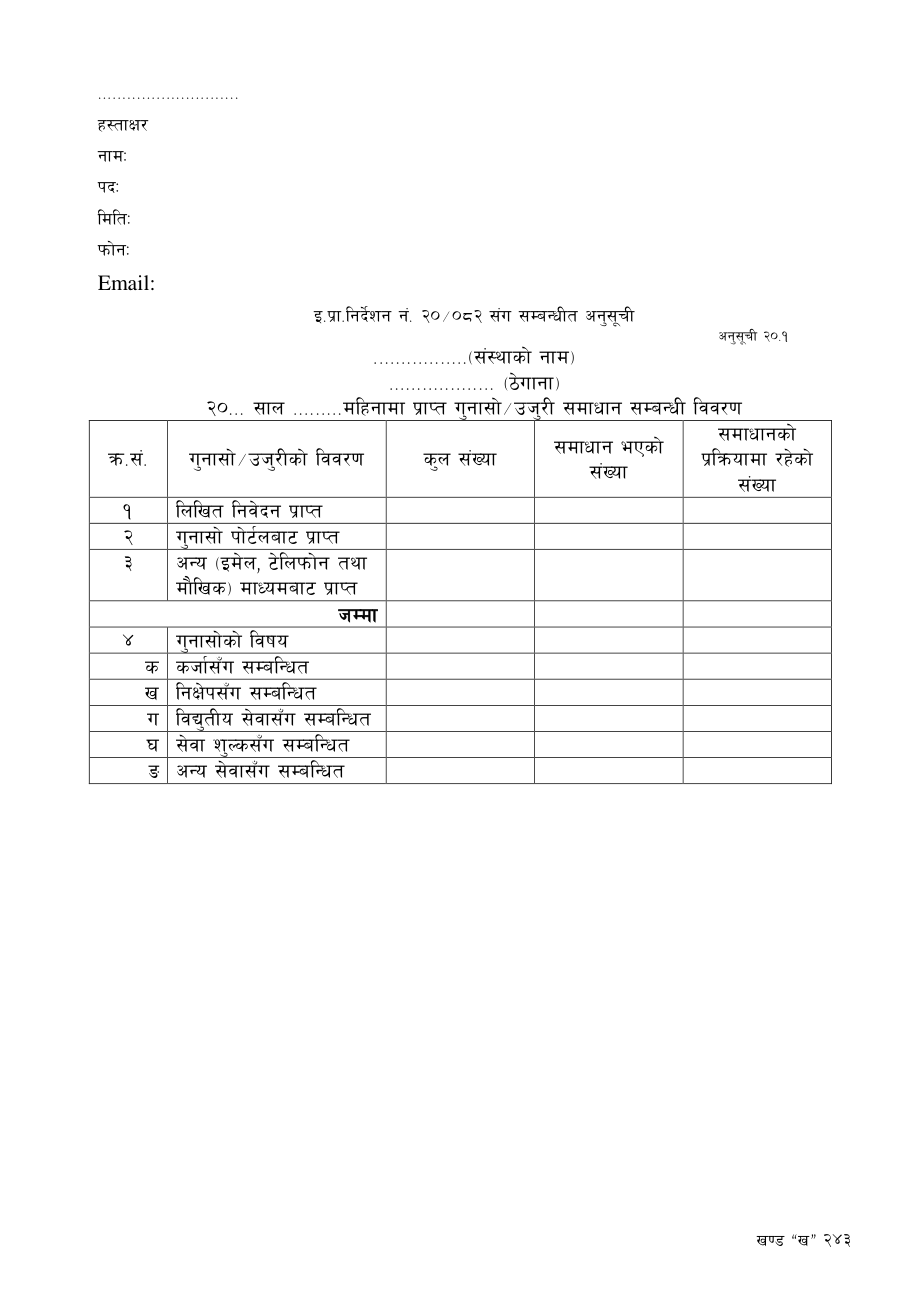
(च) प्राप्त गुनासो र निरुपणसम्बन्धी तथ्याङ्क अनुसूची २०.१ बमोजिम प्रत्येक त्रैमासमा cpreporting@nrb.org.np मा पठाउनु पर्नेछ; ग्राहकबाट प्राप्त गुनासो र त्यसको निरुपणको अवस्था अर्धवार्षिक रुपमा १५ दिनभित्र सम्बन्धित विभागमा पेश गरी वार्षिक प्रतिवेदनमा समेत प्रकाशन गर्नु पर्नेछ ।
Controlled English translation
(a) The concerned bank or financial institution shall be responsible for resolving complaints/grievances received from customers and shall maintain a separate facility for complaint handling.
(b) A “Information and Grievance Hearing Desk” shall be established for convenient customer access, and a senior manager or higher officer designated as the grievance officer. The officer’s name, designation, telephone, mobile number and email shall appear prominently on the website.
(c) A hotline shall also be maintained for consumer grievance handling.
(d) The institution’s website shall contain a link to Nepal Rastra Bank’s grievance portal, gunaso.nrb.org.np.
(e) A policy on customer grievance handling shall be prepared and implemented, with a prominent website link and information on the level responsible for resolving complaints.
(f) Statistics on complaints received and resolved shall be sent each quarter in the format of Schedule 20.1 to cpreporting@nrb.org.np; the status of complaints and resolution shall also be submitted half-yearly within 15 days to the concerned department and disclosed in the annual report.
(क) संस्थाले आफ्ना कार्यक्रमहरुमा वित्तीय साक्षरता सम्बन्धी कार्यक्रम अनिवार्य रुपमा समावेश गर्नु पर्नेछ ।
(ख) आफूले प्रदान गर्ने वित्तीय सेवा सुविधाका सम्बन्धमा सर्वसाधारणलाई सुसूचित गराउने व्यवस्था गर्नु पर्नेछ ।
(ग) वित्तीय साक्षरता अभिवृद्धि गरी वित्तीय प्रणालीलाई सुदृढ पुर्याउने खालका विज्ञापन तथा सूचनाहरुलाई प्राथमिकता दिनु पर्नेछ ।
(घ) नेपाल राष्ट्र बैंकबाट जारी वित्तीय साक्षरता मार्गदर्शन, २०७९ लागू गरी मार्गदर्शनको अनुसूची ३ अनुसारको विवरण पेश गर्नु पर्नेछ ।
Controlled English translation
(a) Financial-literacy programmes shall be mandatorily included in the institution’s programmes.
(b) Arrangements shall be made to inform the public about the financial services and facilities provided.
(c) Priority shall be given to advertisements and information that enhance financial literacy and strengthen the financial system.
(d) The Financial Literacy Guidelines, 2079 issued by Nepal Rastra Bank shall be implemented and the statement prescribed in Schedule 3 of those Guidelines submitted.
(क) ग्राहकसँग वित्तीय कारोबार गर्दा ग्राहकका व्यावसायिक सूचनाहरुको गोपनीयता कायम गर्नु पर्नेछ । नाम, ठेगाना, खाता विवरण, कारोबार तथा अन्य असम्बन्धित/अनधिकृत व्यक्तिलाई दिन नहुने सूचना सुरक्षित राख्नु पर्नेछ ।
(ख) प्रचलित कानुनबमोजिम अधिकारप्राप्त निकाय वा संस्थालाई विवरण उपलब्ध गराउनुपर्ने अवस्थामा यस व्यवस्थाले बाधा पुर्याएको मानिने छैन ।
Controlled English translation
(a) In carrying out financial transactions with customers, confidentiality of customers’ business information shall be maintained. Names, addresses, account information, transactions and other information that should not be disclosed to unrelated/unauthorised persons shall be protected.
(b) Nothing in this provision prevents disclosure to an authority or institution legally entitled to receive the information.
बैंक तथा वित्तीय संस्थाले ग्राहकलाई प्रदान गर्ने सेवा सम्बन्धी जानकारी 24x7 Call Centre वा Audio Notice Board बाट समेत उपलब्ध गराउनु पर्नेछ । यस्तो सेवा उपलब्ध गराएबापत ग्राहकसँग कुनै किसिमको शुल्क लिन पाइने छैन ।
Controlled English translation
Banks and financial institutions shall also make information relating to customer services available through a 24x7 Call Centre or Audio Notice Board. No fee shall be charged to customers for such service.
बैंक तथा वित्तीय संस्थाले अनिवार्य रुपमा आफ्नो वेबसाइट राख्नु पर्नेछ । वेबसाइटमार्फत सार्वजनिक हुने सामग्री नेपाली भाषामा समेत सार्वजनिक गर्ने व्यवस्था गर्नु पर्नेछ ।
Controlled English translation
A bank or financial institution shall mandatorily maintain its own website. Materials made public through the website shall also be made available in Nepali.
एक वर्षभन्दा बढी भुक्तानी अवधि भएका आवधिक कर्जाको हकमा कर्जा प्रवाह पश्चात् तेस्रो पक्षलाई तिर्नुपर्ने शुल्क बाहेक अन्य कुनै पनि शुल्क लिन पाइने छैन ।
Controlled English translation
For term credit with a repayment period exceeding one year, after disbursement no charge shall be collected other than charges payable to a third party.
बैंक तथा वित्तीय संस्थाले एकतर्फी रुपमा ग्राहकको अनुमति बिना कुनै पनि प्रकारको वित्तीय सेवा उपलब्ध गराउन वा शुल्क लिन पाउने छैन । ग्राहकको अनुमति बिना उपलब्ध गराएको सेवा वापत शुल्क लिएमा सो शुल्कमा १० प्रतिशत थप गरी ग्राहकको खातामा जम्मा गर्नु पर्नेछ ।
Controlled English translation
A bank or financial institution shall not unilaterally provide any financial service or charge a fee without the customer’s consent. If a fee is charged for a service provided without consent, the fee shall be refunded to the customer’s account together with an additional 10 percent.
इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाले जारी गरेको बैंक जमानत (Bank Guarantee) को Verification आफ्नो वेबसाइट/पोर्टल मार्फत गर्न सकिने व्यवस्था गर्नु पर्नेछ ।
Controlled English translation
A licensed bank or financial institution shall make arrangements so that a Bank Guarantee issued by it can be verified through its website/portal.
(१) एकीकृत निर्देशन, २०८१ को सेवा शुल्क सम्बन्धी इ.प्रा. निर्देशन नं. २०/०८१ तथा सोपश्चात् मिति २०८२ माघ २ सम्म जारी भएका यसै विषयसँग सम्बन्धित सम्पूर्ण परिपत्रहरु खारेज गरिएको छ ।
(२) उपबुँदा (१) बमोजिम खारेज गरिएका निर्देशन तथा परिपत्रबमोजिम भए गरेका काम कारवाही यसै निर्देशनबमोजिम भए गरेको मानिनेछ ।
Controlled English translation
(1) Directive No. 20/081 of the Unified Directives, 2081 relating to service charges and all circulars relating to the same subject issued thereafter up to Magh 2, 2082 are repealed.
(2) Acts and actions taken pursuant to the directives and circulars repealed under sub-clause (1) shall be deemed to have been taken pursuant to this Directive.
Original Nepali text is authoritative. English is a controlled facilitative translation and is not an official Nepal Rastra Bank translation.
In case of inconsistency, ambiguity or difference, the official Nepali Directive and applicable Nepal Rastra Bank circulars prevail.
C.M. & Associates is not affiliated with, approved by or endorsed by Nepal Rastra Bank. This material is provided for information and reference only and does not constitute legal, regulatory, tax or professional advice.
Technical controls cannot guarantee prevention of screenshots or copying.