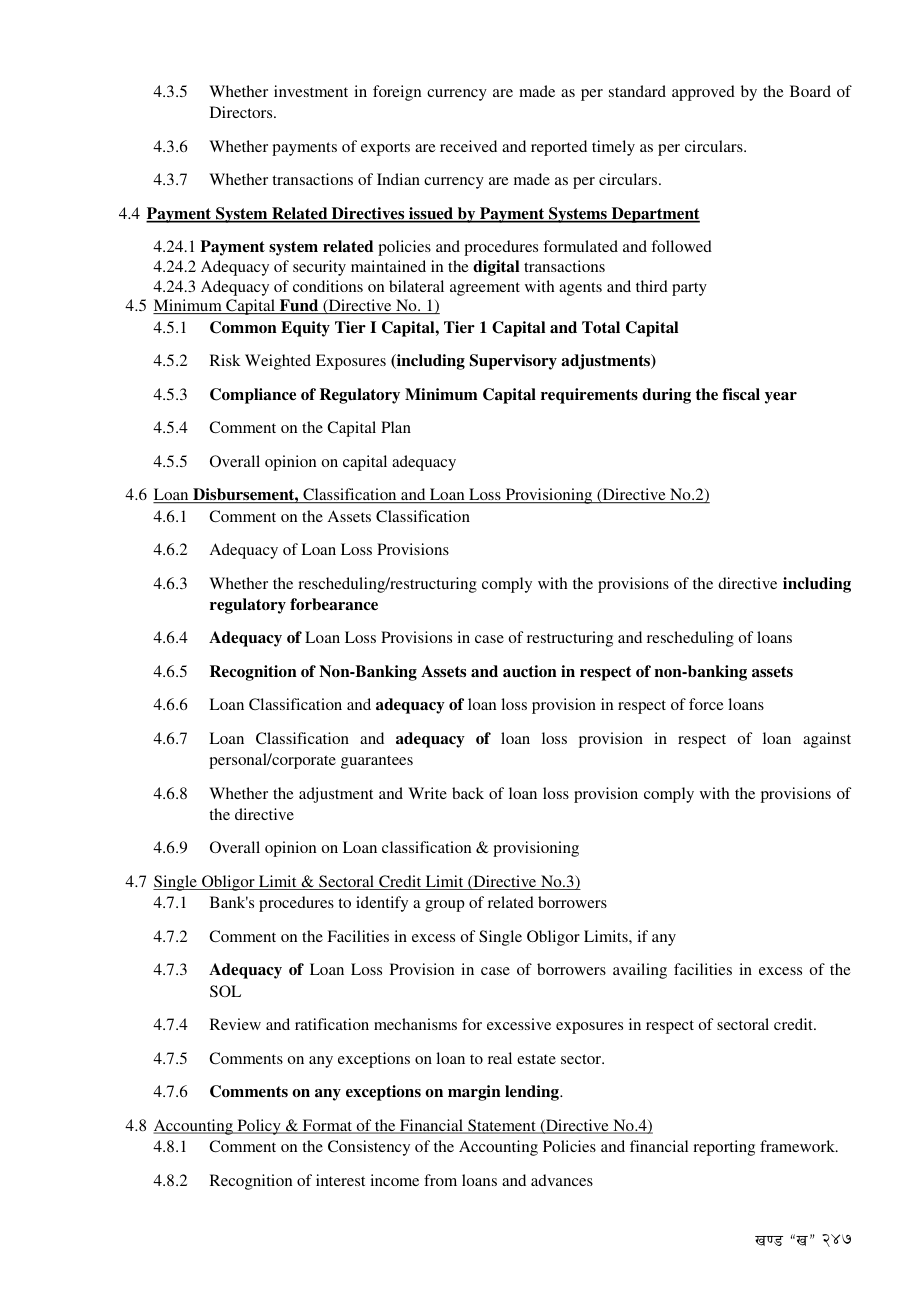
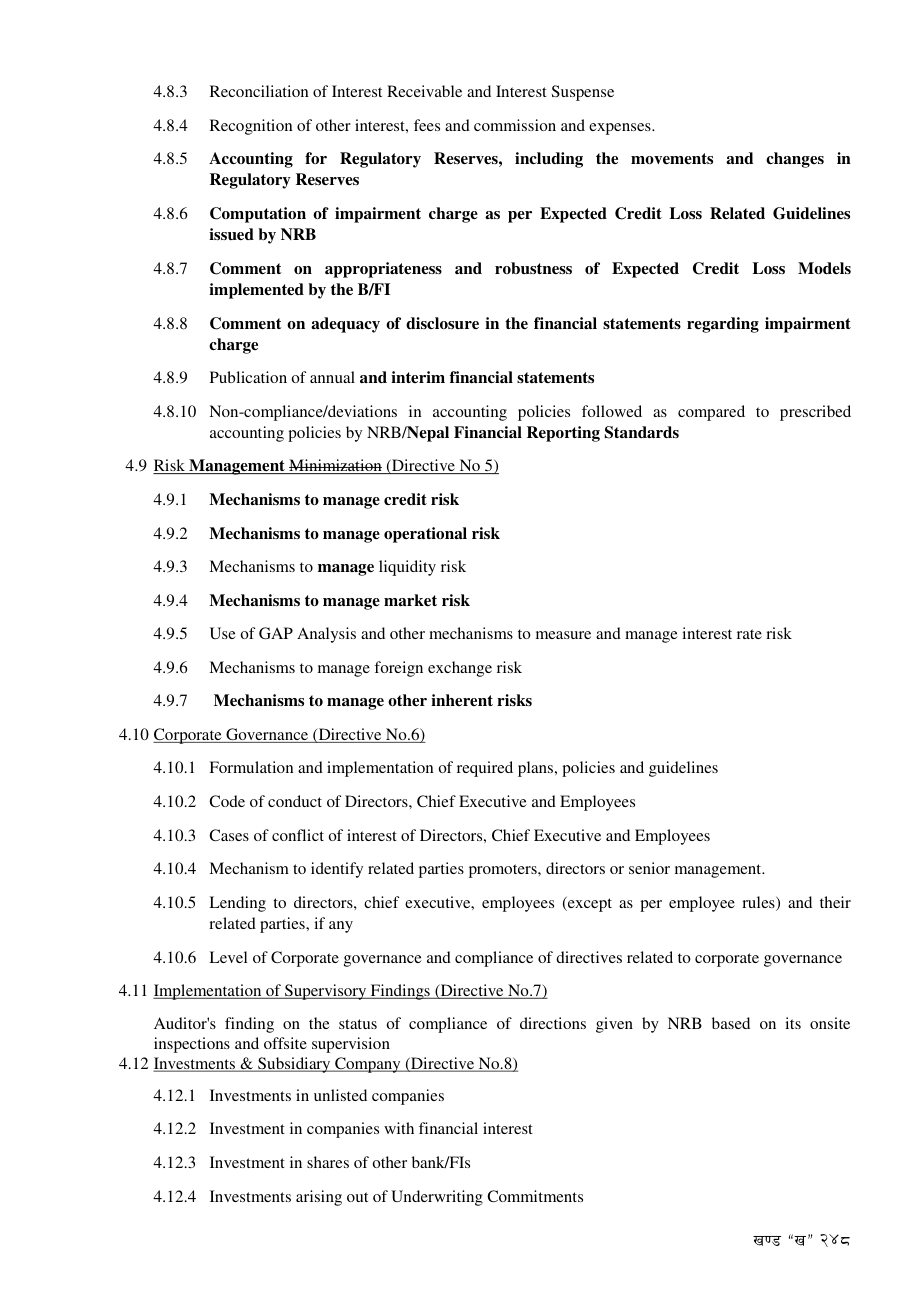
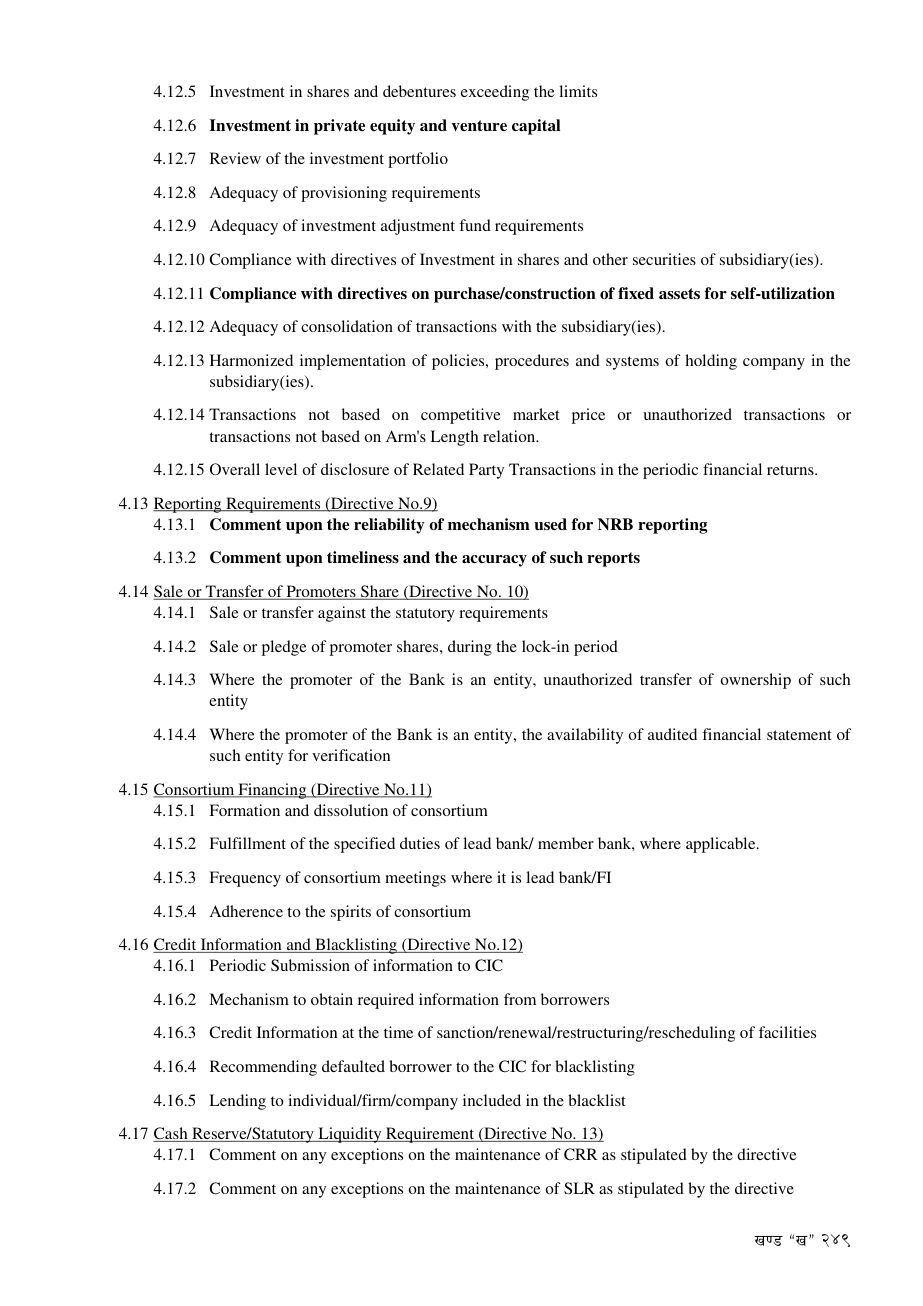
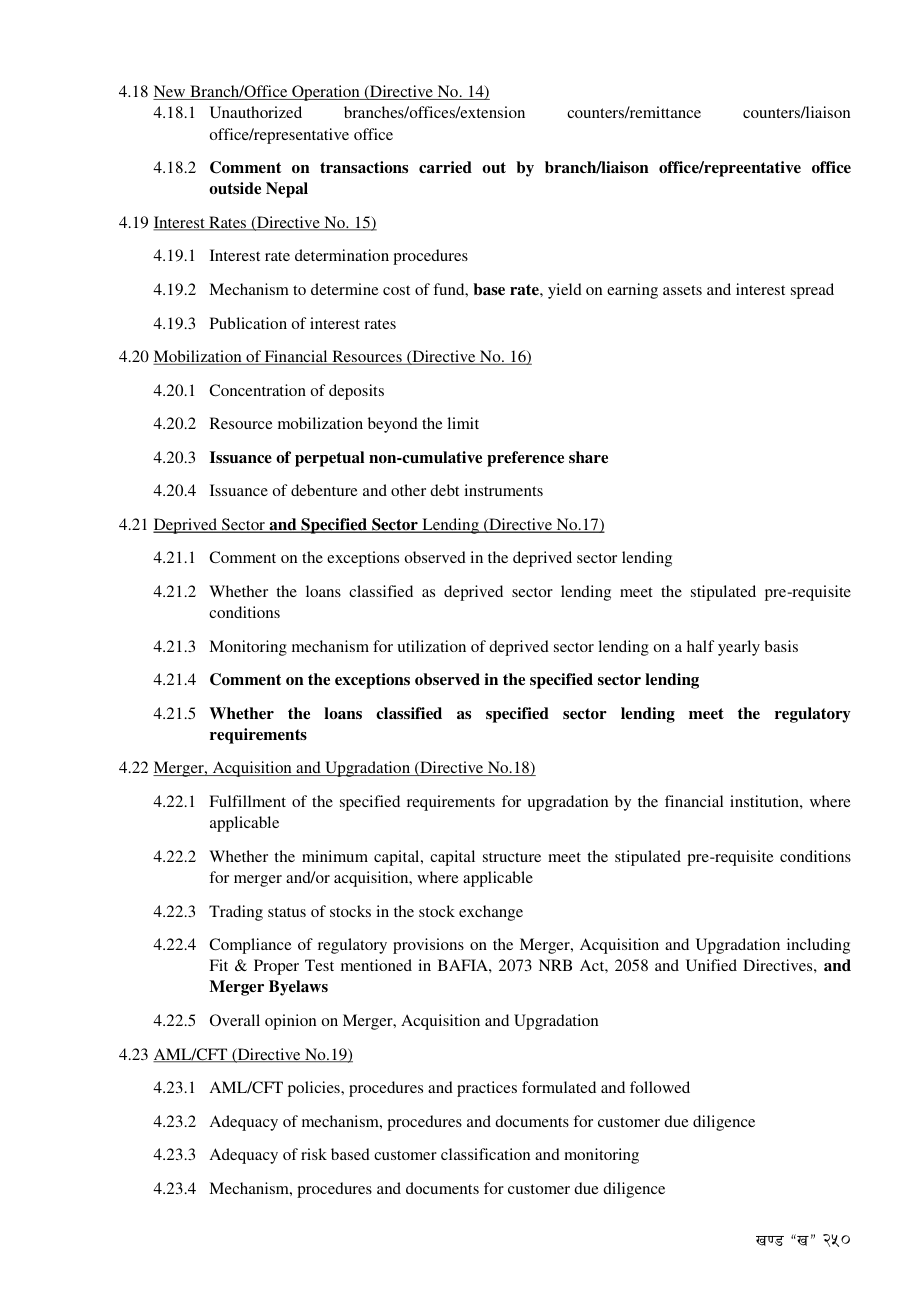
Original/reproduced Nepali source controls; English is a controlled facilitative translation.
Applicability Class A licensed institutions; Class B licensed institutions; Class C licensed institutions
Classification PASS WITH EXPLICIT SOURCE GAP
Updated-through statement Circular No. 14 (A/B/C), FY 2082/83: Clause 48/overtime and renumbered repeal-saving recorded; exact wording not reproduced.
Rendering basis Render web-normalized sections and canonical supplemental objects exactly. Canonical reviewed JSON is authoritative for web/PDF. Do not OCR or rewrite legal text.
नेपाली मूल पाठ
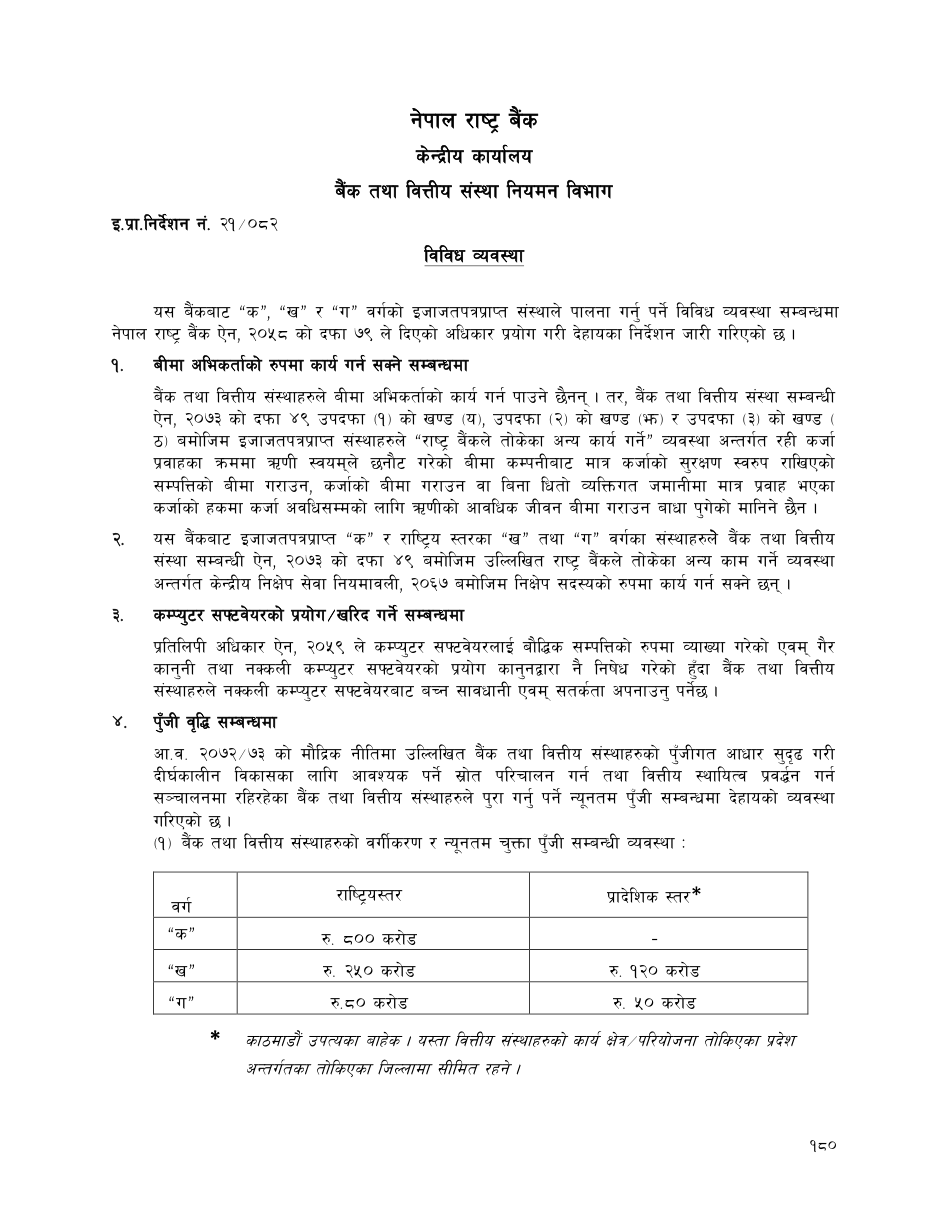
यस बैंकबाट “क”, “ख” र “ग” वर्गको इजाजतपत्रप्राप्त संस्थाले पालना गर्नु पर्ने विविध व्यवस्था सम्बन्धमा नेपाल राष्ट्र बैंक ऐन, २०५८ को दफा ७९ ले दिएको अधिकार प्रयोग गरी देहायका निर्देशन जारी गरिएको छ ।
Controlled English translation
In exercise of the authority conferred by Section 79 of the Nepal Rastra Bank Act, 2058, the following directives are issued in relation to miscellaneous provisions to be complied with by Class “A”, “B” and “C” licensed institutions.
बैंक तथा वित्तीय संस्थाहरुले बीमा अभिकर्ताको कार्य गर्न पाउने छैनन् । तर, बैंक तथा वित्तीय संस्था सम्बन्धी ऐन, २०७३ को दफा ४९ उपदफा (१) को खण्ड (य), उपदफा (२) को खण्ड (क) र उपदफा (३) को खण्ड (ठ) बमोजिम इजाजतपत्रप्राप्त संस्थाहरुले “राष्ट्र बैंकले तोकेको अन्य कार्य गर्ने” व्यवस्था अन्तर्गत रही कर्जा प्रवाहका क्रममा ऋणी स्वयंले छनौट गरेको बीमा कम्पनीबाट मात्र कर्जाको सुरक्षण स्वरुप राखिएको सम्पत्तिको बीमा गराउन, कर्जाको बीमा गराउन वा बिना धितो व्यक्तिगत जमानतमा मात्र प्रवाह भएका कर्जाको हकमा कर्जा अवधिसम्मको लागि ऋणीको आवधिक जीवन बीमा गराउन बाधा पुगेको मानिने छैन ।
Controlled English translation
Banks and financial institutions shall not act as insurance agents. However, under the provision permitting licensed institutions to perform “other functions prescribed by Nepal Rastra Bank” pursuant to the applicable clauses of Section 49 of the Bank and Financial Institution Act, 2073, nothing shall prevent a licensed institution, in the course of lending, from arranging through an insurance company selected by the borrower: insurance of property pledged as loan security, insurance of the loan, or—where the loan is extended without collateral solely against personal guarantee—term life insurance of the borrower for the period of the loan.
यस बैंकबाट इजाजतपत्रप्राप्त “क” र राष्ट्रिय स्तरका “ख” तथा “ग” वर्गका संस्थाहरुले बैंक तथा वित्तीय संस्था सम्बन्धी ऐन, २०७३ को दफा ४९ बमोजिम उल्लिखित राष्ट्र बैंकले तोकेका अन्य काम गर्ने व्यवस्था अन्तर्गत केन्द्रीय निक्षेप सेवा नियमावली, २०६७ बमोजिम निक्षेप सदस्यको रुपमा कार्य गर्न सक्ने छन् ।
Controlled English translation
Class “A” institutions and national-level Class “B” and “C” institutions licensed by this Bank may, under the provision in Section 49 of the Bank and Financial Institution Act, 2073 permitting other functions prescribed by Nepal Rastra Bank, act as Depository Participants in accordance with the Central Depository Service Regulations, 2067.
प्रतिलिपि अधिकार ऐन, २०५९ ले कम्प्युटर सफ्टवेयरलाई बौद्धिक सम्पत्तिको रुपमा व्याख्या गरेको एवम् गैर कानुनी तथा नक्कली कम्प्युटर सफ्टवेयरको प्रयोग कानुनतः निषेध रहेको हुँदा बैंक तथा वित्तीय संस्थाहरुले नक्कली कम्प्युटर सफ्टवेयरबाट बच्न सावधानी पुर्याउनु पर्नेछ ।
Controlled English translation
As the Copyright Act, 2059 recognises computer software as intellectual property and the use of illegal or counterfeit computer software is prohibited by law, banks and financial institutions shall exercise due care to avoid counterfeit or unauthorised computer software.
आ.व. २०७२/७३ को मौद्रिक नीतिमा उल्लिखित बैंक तथा वित्तीय संस्थाहरुको पुँजीगत आधार सुदृढ गरी दीर्घकालीन विकासका लागि आवश्यक पर्ने स्रोत परिचालन गर्न तथा वित्तीय स्थायित्व प्रवर्द्धन गर्ने समग्रतामा गरिएका बैंक तथा वित्तीय संस्थाहरुले पूरा गर्नु पर्ने न्यूनतम चुक्ता पुँजी सम्बन्धमा देहायको व्यवस्था गरिएको छ ।
(१) बैंक तथा वित्तीय संस्थाहरुको वर्गीकरण र न्यूनतम चुक्ता पुँजी सम्बन्धी व्यवस्था :
वर्ग | राष्ट्रियस्तर | प्रादेशिक स्तर*
“क” | रु. ८०० करोड | -
“ख” | रु. २५० करोड | रु. १२० करोड
“ग” | रु. ८० करोड | रु. ५० करोड
* काठमाडौं उपत्यका बाहेक । यस्ता वित्तीय संस्थाहरुको कार्य क्षेत्र/परियोजना तोकिएका प्रदेश अन्तर्गतका तोकिएका जिल्लामा सीमित रहने ।
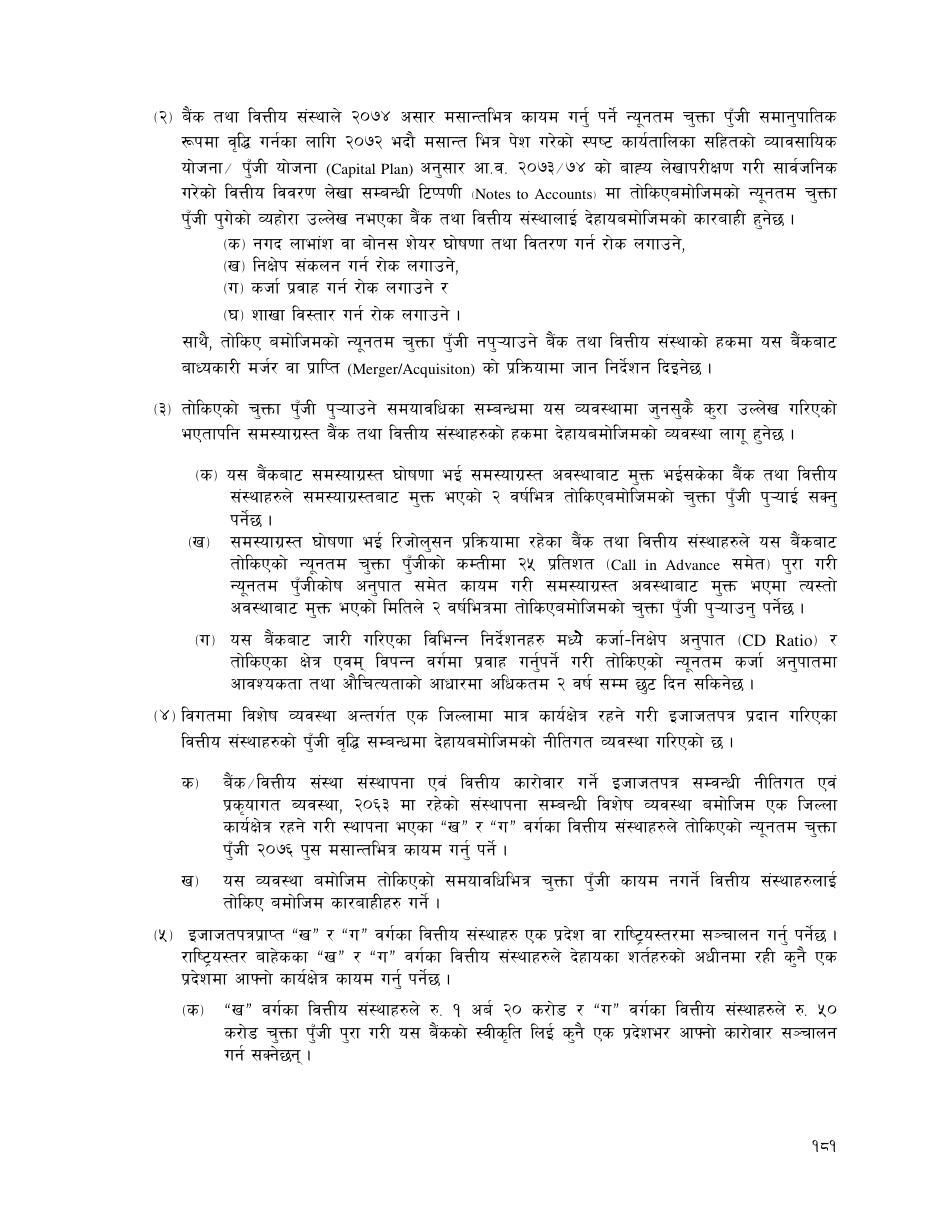
(२) बैंक तथा वित्तीय संस्थाले २०७४ असार मसान्तभित्र कायम गर्नु पर्ने न्यूनतम चुक्ता पुँजी समानुपातिक रुपमा वृद्धि गर्नका लागि २०७२ भदौ मसान्त भित्र पेश गरेको स्पष्ट कार्यतालिका सहितको व्यावसायिक योजना/पुँजी योजना (Capital Plan) अनुसार आ.व. २०७३/७४ को बाह्य लेखापरीक्षण गरी सार्वजनिक गरेको वित्तीय विवरण लेखा सम्बन्धी टिप्पणी (Notes to Accounts) मा तोकिएबमोजिमको न्यूनतम चुक्ता पुँजी पुगेको व्यहोरा उल्लेख नभएका बैंक तथा वित्तीय संस्थाहरुलाई देहायबमोजिमको कारवाही हुनेछ ।
(क) नगद लाभांश वा बोनस शेयर घोषणा तथा वितरण गर्न रोक लगाउने,
(ख) निक्षेप संकलन गर्न रोक लगाउने,
(ग) कर्जा प्रवाह गर्न रोक लगाउने र
(घ) शाखा विस्तार गर्न रोक लगाउने ।
साथै, तोकिएबमोजिमको न्यूनतम चुक्ता पुँजी नपुर्याउने बैंक तथा वित्तीय संस्थाको हकमा यस बैंकबाट बाध्यकारी मर्जर वा प्राप्ति (Merger/Acquisition) को प्रक्रियामा जान निर्देशन दिइनेछ ।
(३) तोकिएको चुक्ता पुँजी पुर्याउने समयावधिका सम्बन्धमा यस व्यवस्थामा जुनसुकै कुरा उल्लेख गरिएको भएतापनि समस्याग्रस्त बैंक तथा वित्तीय संस्थाहरुको हकमा देहायबमोजिमको व्यवस्था लागू हुनेछ ।
(क) यस बैंकबाट समस्याग्रस्त घोषणा भई समस्याग्रस्त अवस्थाबाट मुक्त भईसकेका बैंक तथा वित्तीय संस्थाहरुले समस्याग्रस्तबाट मुक्त भएको २ वर्षभित्र तोकिएबमोजिमको चुक्ता पुँजी पुर्याई सक्नु पर्नेछ ।
(ख) समस्याग्रस्त घोषणा भई रिजोलुसन प्रक्रियामा रहेका बैंक तथा वित्तीय संस्थाहरुले यस बैंकबाट तोकिएको न्यूनतम चुक्ता पुँजीको कम्तीमा २५ प्रतिशत (Call in Advance समेत) पूरा गरी न्यूनतम पुँजीकोष अनुपात समेत कायम गरी समस्याग्रस्त अवस्थाबाट मुक्त भएमा त्यस्तो अवस्थाबाट मुक्त भएको मितिले २ वर्षभित्रमा तोकिएबमोजिमको चुक्ता पुँजी पुर्याउनु पर्नेछ ।
(ग) यस बैंकबाट जारी गरिएका विभिन्न निर्देशनहरु मध्ये कर्जा-निक्षेप अनुपात (CD Ratio) र तोकिएका क्षेत्र एवम् विपन्न वर्गमा प्रवाह गर्नु पर्ने गरी तोकिएको न्यूनतम कर्जा अनुपात आवश्यकताको औचित्यताको आधारमा अधिकतम २ वर्षसम्म छुट दिन सकिनेछ ।
(४) विगतमा विशेष व्यवस्था अन्तर्गत एक जिल्लामा मात्र कार्यक्षेत्र रहने गरी इजाजतपत्र प्रदान गरिएका वित्तीय संस्थाहरुको पुँजी वृद्धि सम्बन्धमा देहायबमोजिमको नीतिगत व्यवस्था गरिएको छ ।
क) बैंक/वित्तीय संस्था संस्थापना एवं वित्तीय कारोबार गर्ने इजाजतपत्र सम्बन्धी नीतिगत एवं प्रक्रियागत व्यवस्था, २०६३ मा रहेको संस्थापना सम्बन्धी विशेष व्यवस्था बमोजिम एक जिल्ला कार्यक्षेत्र रहने गरी स्थापना भएका “ख” र “ग” वर्गका वित्तीय संस्थाहरुले तोकिएको न्यूनतम चुक्ता पुँजी २०७६ पुस मसान्तभित्र कायम गर्नु पर्ने ।
ख) यस व्यवस्था बमोजिम तोकिएको समयावधिभित्र चुक्ता पुँजी कायम नगर्ने वित्तीय संस्थाहरुलाई तोकिएबमोजिम कारवाहीहरु गर्ने ।
(५) इजाजतपत्रप्राप्त “ख” र “ग” वर्गका वित्तीय संस्थाहरु एक प्रदेश वा राष्ट्रियस्तरमा सञ्चालन गर्नु पर्नेछ । राष्ट्रियस्तर बाहेकका “ख” र “ग” वर्गका वित्तीय संस्थाहरुले देहायका शर्तहरुको अधीनमा रही कुनै एक प्रदेशमा आफ्नो कार्यक्षेत्र कायम गर्नु पर्नेछ ।
(क) “ख” वर्गका वित्तीय संस्थाहरुले रु. १ अर्ब २० करोड र “ग” वर्गका वित्तीय संस्थाहरुले रु. ५० करोड चुक्ता पुँजी पूरा गरी यस बैंकको स्वीकृति लिई कुनै एक प्रदेशभर आफ्नो कारोबार सञ्चालन गर्न सक्नेछन् ।
(ख) बुँदा नं. (क) बमोजिमको चुक्ता पुँजी पूरा नगरेसम्म हाल कायम रहेका जिल्लाहरुमा सीमित रही आफ्नो कारोबार सञ्चालन गर्नु पर्नेछ ।
(ग) एकभन्दा बढी प्रदेशमा समेत शाखा कार्यालय खोली सञ्चालनमा रहेका वित्तीय संस्थाहरुले २०७७ असारमसान्तभित्र उक्त शाखा बिक्री, बन्द वा स्थानान्तरण गरी आफ्नो सम्पूर्ण कार्यक्षेत्र एउटै प्रदेशभित्र सीमित गरी सक्नु पर्नेछ ।
(घ) प्रादेशिक स्तरका लागि तोकिएको चुक्ता पुँजी पूरा गरेका वित्तीय संस्थाले एकभन्दा बढी प्रदेशमा रहेका शाखा कार्यालय बिक्री, बन्द वा स्थानान्तरण नगरेसम्म आफ्नो प्रदेशका बाँकी जिल्लामा कार्यक्षेत्र विस्तार गर्न पाउने छैनन् ।
(ङ) बुँदा नं. (ख) र बुँदा नं. (घ) मा जुनसुकै कुरा लेखिएको भएतापनि रु. ५० करोड चुक्ता पुँजी पूरा गरेका “ख” वर्गका वित्तीय संस्थाहरु र रु. ४० करोड चुक्ता पुँजी पूरा गरेका “ग” वर्गका वित्तीय संस्थाहरुले यस बैंकको स्वीकृति लिई कुल पाँच जिल्ला ननाघ्ने गरी एउटै प्रदेशभित्रका जोडिएका ५ जिल्लासम्म कार्यक्षेत्र विस्तार गर्न भने यस व्यवस्थाले बाधा पुर्याएको मानिने छैन ।
(च) प्रादेशिक वा राष्ट्रियस्तरमा स्तरोन्नति हुने क्रममा चुक्ता पुँजी पूरा गर्ने प्रयोजनका लागि गाभ्ने/गाभिने वा प्राप्ति सम्बन्धी कार्यलाई प्राथमिकता दिनु पर्नेछ ।
Controlled English translation
In accordance with the policy announced in the Monetary Policy for FY 2072/73 to strengthen the capital base of banks and financial institutions, mobilise resources required for long-term development and promote financial stability, the following provisions apply to the minimum paid-up capital to be maintained by banks and financial institutions.
(1) Classification and minimum paid-up capital:
Class | National Level | Provincial Level*
“A” | NPR 8 billion | -
“B” | NPR 2.5 billion | NPR 1.2 billion
“C” | NPR 800 million | NPR 500 million
* Outside Kathmandu Valley. The area of operation/projects of such financial institutions shall remain limited to the specified districts within the specified Province.
(2) Banks and financial institutions that did not disclose in the Notes to Accounts of their audited and published financial statements for FY 2073/74 that they had achieved the prescribed minimum paid-up capital in accordance with the business plan/Capital Plan, including the clear timetable submitted by Bhadra-end 2072 for proportionate increase of capital to the level required by Ashadh-end 2074, shall be subject to:
(a) prohibition on declaration and distribution of cash dividend or bonus shares;
(b) prohibition on deposit mobilisation;
(c) prohibition on lending; and
(d) prohibition on branch expansion.
In addition, a bank or financial institution that fails to meet the prescribed minimum paid-up capital may be directed by this Bank to enter into a mandatory Merger/Acquisition process.
(3) Notwithstanding anything in this provision regarding the period for meeting paid-up capital, the following shall apply to problematic banks and financial institutions:
(a) an institution declared problematic and subsequently released from problematic status shall meet the prescribed paid-up capital within two years from the date of release;
(b) an institution declared problematic and undergoing resolution may be released after meeting at least 25 percent of the prescribed minimum paid-up capital, including Call in Advance, and maintaining the minimum capital-fund ratio; it shall then meet the prescribed paid-up capital within two years from the date of release;
(c) among the directives issued by this Bank, relaxation of up to two years may be granted, on grounds of need and justification, in respect of the CD Ratio and the minimum lending ratios prescribed for specified sectors and the deprived class.
(4) For financial institutions previously licensed under the special arrangement with an area of operation limited to one district:
(a) Class “B” and “C” institutions established under the special establishment provisions of the Policy and Procedural Arrangements Relating to Establishment and Licensing of Banks/Financial Institutions, 2063, with a one-district area of operation shall maintain the prescribed minimum paid-up capital by Poush-end 2076;
(b) institutions failing to maintain the paid-up capital within the prescribed period shall be subject to the prescribed actions.
(5) Class “B” and “C” licensed financial institutions shall operate either at provincial or national level. A non-national Class “B” or “C” institution shall maintain its area of operation within one Province subject to:
(a) a Class “B” institution with paid-up capital of NPR 1.2 billion and a Class “C” institution with paid-up capital of NPR 500 million may, with approval of this Bank, operate throughout one Province;
(b) until the paid-up capital under paragraph (a) is met, the institution shall remain limited to its currently approved districts;
(c) an institution operating branches in more than one Province shall, by Ashadh-end 2077, sell, close or relocate such branches so that its entire area of operation is limited to one Province;
(d) a provincial-level institution that has met the prescribed paid-up capital shall not expand into the remaining districts of its Province until branches in other Provinces have been sold, closed or relocated;
(e) notwithstanding paragraphs (b) and (d), a Class “B” institution with paid-up capital of NPR 500 million and a Class “C” institution with paid-up capital of NPR 400 million may, with approval of this Bank, expand its area of operation to adjoining districts within one Province, not exceeding five districts in total;
(f) in the course of upgrading to provincial or national level, merger/consolidation or acquisition shall be prioritised for meeting the paid-up capital requirement.
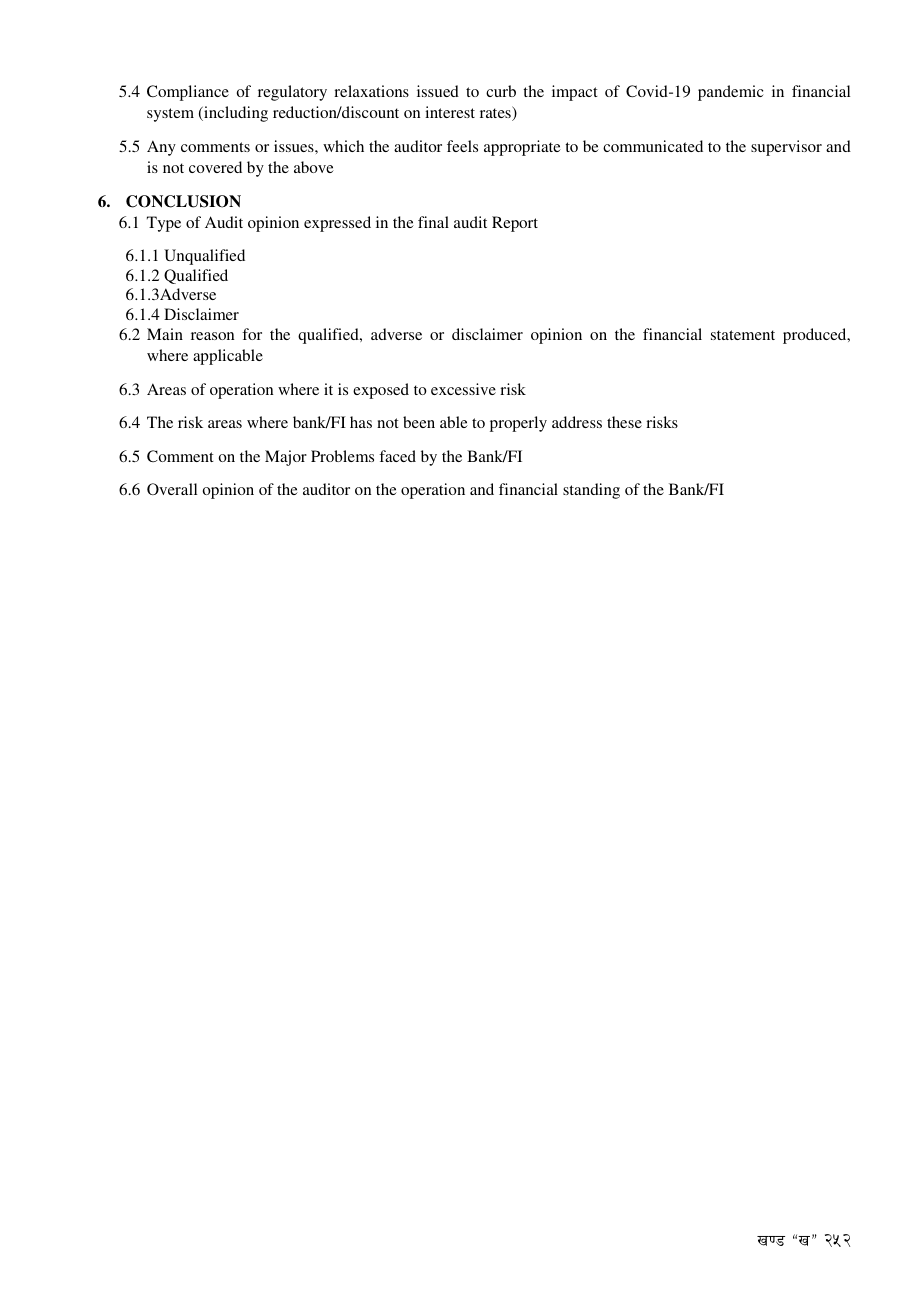
Long Form Audit Report लाई समय सापेक्ष र प्रभावकारी बनाउन आर्थिक वर्ष २०८१/८२ देखिको बाह्य लेखापरीक्षण प्रयोजनका लागि यसैसाथ संलग्न ढाँचा (अनुसूची २१.१) अनुसार लागू गरिएको छ । आफ्नो संस्थाको बाह्य लेखापरीक्षकबाट सोही ढाँचामा तयार गरिएको प्रतिवेदनलाई सोही रूपमै यस बैंकमा आइपुग्ने गरी पठाउने व्यवस्था गर्नु पर्नेछ ।
Controlled English translation
For external audits from FY 2081/82, the Long Form Audit Report shall use the attached Schedule 21.1 format. The institution shall arrange for the report prepared by its external auditor in that same format to reach this Bank.
पुँजी योजना प्रयोजनका लागि “चुक्ता पुँजी” भन्ने शब्दले साधारण शेयर वापतको चुक्ता पुँजी (बोनस शेयर तथा हकप्रद शेयर) लाई मात्र बुझाउने र सो चुक्ता पुँजीमा साधारण शेयरवापतको प्रस्तावित बोनस शेयरलाई समेत समावेश गर्न सकिनेछ ।
Controlled English translation
For purposes of a Capital Plan, “paid-up capital” means paid-up capital represented by ordinary shares, including bonus and rights shares; proposed bonus shares relating to ordinary shares may also be included.
यस बैंकबाट इजाजतपत्रप्राप्त संस्थाको आ-आफ्नो स्वामित्वमा रहेको नेपाल सरकारको ट्रेजरी बिल्स र विकास ऋणपत्रको धितोमा त्यस्ता ऋणपत्रहरुको अंकित मूल्यको ९० प्रतिशतसम्मले हुन आउने रकम प्रचलित बैंकदरमा अल्पकालीन स्थायी तरलता सुविधा (कर्जा) यस बैंकले उपलब्ध गराउन सक्ने छ ।
Controlled English translation
This Bank may provide a short-term Standing Liquidity Facility at the prevailing Bank Rate against Government of Nepal Treasury Bills and Development Bonds owned by the institution, up to 90 percent of face value.
इजाजतपत्रप्राप्त संस्थालाई खुला बजार कारोबार नियमावली र योग्यतासम्बन्धी कार्यविधिको शर्त तथा मापदण्डका आधारमा यस बैंकले स्थायी निक्षेप सुविधा उपलब्ध गराउन सक्नेछ ।
Controlled English translation
This Bank may provide the Standing Deposit Facility on the basis of the conditions and standards under the Open Market Transaction Regulations and applicable eligibility procedure.
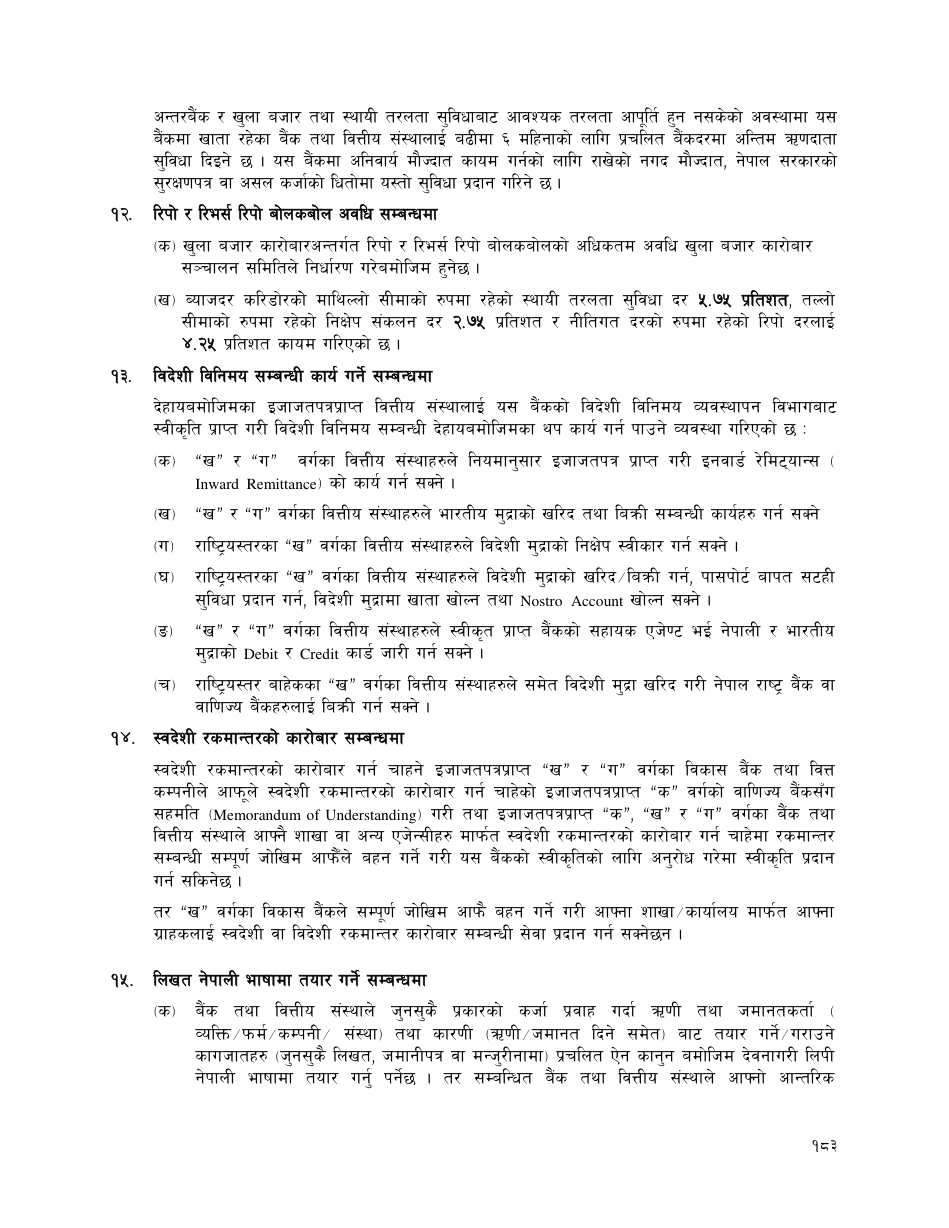
अन्तरबैंक र खुला बजार तथा स्थायी तरलता सुविधाबाट आवश्यक तरलता आपूर्ति हुन नसकेको अवस्थामा यस बैंकमा खाता रहेका बैंक तथा वित्तीय संस्थालाई बढीमा ६ महिनाको लागि प्रचलित बैंकदरमा अन्तिम ऋणदाता सुविधा दिइने छ । यस बैंकमा अनिवार्य मौज्दात कायम गर्नका लागि राखेको नगद मौज्दात, नेपाल सरकारको सुरक्षणपत्र वा अन्य कर्जाको सुरक्षण धितोमा यस्तो सुविधा प्रदान गरिने छ ।
Controlled English translation
Where required liquidity cannot be obtained through the interbank market, open-market operations or SLF, a bank or financial institution maintaining an account with this Bank may receive lender-of-last-resort support for up to six months at the prevailing Bank Rate against eligible cash balances, Government securities or other collateral.
(क) खुला बजार कारोबारअन्तर्गत रिपो र रिभर्स रिपो बोलकबोलको अधिकतम अवधि खुला बजार कारोबार सञ्चालन समितिले निर्धारण गरेबमोजिम हुनेछ ।
(ख) ब्याजदर करिडोरको माथिल्लो सीमाको रुपमा रहेको स्थायी तरलता सुविधा दर ५.७५ प्रतिशत, तल्लो सीमाको रुपमा रहेको निक्षेप संकलन दर २.७५ प्रतिशत र नीतिगत दरको रुपमा रहेको रिपो दरलाई ४.२५ प्रतिशत कायम गरिएको छ ।
Controlled English translation
(a) The maximum tenor of repo and reverse-repo auctions shall be as determined by the Open Market Transaction Operation Committee.
(b) The SLF rate is 5.75 percent, the deposit-collection rate 2.75 percent and the policy repo rate 4.25 percent.
देहायबमोजिमका इजाजतपत्रप्राप्त वित्तीय संस्थालाई यस बैंकको विदेशी विनिमय व्यवस्थापन विभागबाट स्वीकृति प्राप्त गरी विदेशी विनिमय सम्बन्धी देहायबमोजिमका थप कार्य गर्न पाउने व्यवस्था गरिएको छ:
(क) “ख” र “ग” वर्गका वित्तीय संस्थाहरुले नियमानुसार इजाजतपत्र प्राप्त गरी Inward Remittance को कार्य गर्न सक्ने ।
(ख) “ख” र “ग” वर्गका वित्तीय संस्थाहरुले भारतीय मुद्राको खरिद तथा बिक्री सम्बन्धी कार्यहरु गर्न सक्ने ।
(ग) राष्ट्रियस्तरका “ख” वर्गका वित्तीय संस्थाहरुले विदेशी मुद्राको निक्षेप स्वीकार गर्न सक्ने ।
(घ) राष्ट्रियस्तरका “ख” वर्गका वित्तीय संस्थाहरुले विदेशी मुद्राको खरिद/बिक्री गर्न, पासपोर्ट वापत सटही सुविधा प्रदान गर्न, विदेशी मुद्रामा खाता खोल्न तथा Nostro Account खोल्न सक्ने ।
(ङ) “ख” र “ग” वर्गका वित्तीय संस्थाहरुले स्वीकृति प्राप्त बैंकको सहायक एजेन्ट भई नेपाली र भारतीय मुद्राको Debit र Credit Card जारी गर्न सक्ने ।
(च) राष्ट्रियस्तर बाहेकका “ख” वर्गका वित्तीय संस्थाहरुले समेत विदेशी मुद्रा खरिद गरी नेपाल राष्ट्र बैंक वा वाणिज्य बैंकहरुलाई बिक्री गर्न सक्ने ।
Controlled English translation
Subject to approval of the Foreign Exchange Management Department:
(a) Class “B” and “C” institutions may obtain the prescribed licence and conduct Inward Remittance;
(b) they may purchase and sell Indian currency;
(c) national-level Class “B” institutions may accept foreign-currency deposits;
(d) national-level Class “B” institutions may buy/sell foreign currency, provide passport exchange facilities, open foreign-currency accounts and Nostro Accounts;
(e) Class “B” and “C” institutions may act as sub-agents of an approved bank and issue Debit and Credit Cards in Nepali and Indian currency;
(f) non-national Class “B” institutions may purchase foreign currency and sell it to Nepal Rastra Bank or commercial banks.
स्वदेशी रकमान्तरको कारोबार गर्न चाहने इजाजतपत्रप्राप्त “ख” र “ग” वर्गका विकास बैंक तथा वित्त कम्पनीले आफ्नो स्वदेशी रकमान्तरको कारोबार गर्न चाहेको इजाजतपत्रप्राप्त “क” वर्गको वाणिज्य बैंकसँग सहमति (Memorandum of Understanding) गरी तथा इजाजतपत्रप्राप्त “क”, “ख” र “ग” वर्गका बैंक तथा वित्तीय संस्थाले आफ्नै शाखा वा अन्य एजेन्टहरु मार्फत स्वदेशी रकमान्तरको कारोबार गर्न चाहेमा रकमान्तर सम्बन्धी सम्पूर्ण जोखिम आफैंले वहन गर्ने गरी राष्ट्र बैंकको स्वीकृतिको लागि अनुरोध पेश गर्न सक्नेछन् ।
तर “ख” वर्गका विकास बैंकले सम्पूर्ण जोखिम आफैंले वहन गर्ने गरी आफ्ना शाखा/कार्यालय मार्फत आफ्ना ग्राहकहरुलाई स्वदेशी वा विदेशी रकमान्तर कारोबार सम्बन्धी सेवा प्रदान गर्न सक्नेछन् ।
Controlled English translation
A Class “B” development bank or Class “C” finance company may conduct domestic remittance business through an MOU with a Class “A” commercial bank, and Class “A”, “B” and “C” institutions may request approval to conduct domestic remittance through their own branches or agents while bearing all related risks.
A Class “B” development bank may, bearing all risks itself, provide domestic or foreign remittance services to its customers through its own branches/offices.
(क) बैंक तथा वित्तीय संस्थाले जुनसुकै प्रकारको कर्जा प्रवाह गर्दा ऋणी तथा जमानतकर्ता (व्यक्ति/फर्म/कम्पनी/संस्था) तथा कारणी (ऋणी/जमानत दिने समेत) बाट तयार गर्ने/गराउने कागजातहरु (जुनसुकै लिखत, जमानतनामा वा मञ्जुरीनामा) प्रचलित ऐन कानुन बमोजिम देवनागरी लिपि नेपाली भाषामा तयार गर्नु पर्नेछ । त्यसरी नेपाली भाषामा तयार गरिएको लिखतहरु अंग्रेजी भाषामा अनुवाद गरी अभिलेखमा राख्न भने पाइने छ ।
विदेशी नागरिकहरुसँग हुने कारोबारमा र विदेशी बैंकिङ कारोबारमा मात्र प्रयोग हुने लिखतहरु (जस्तै: प्रतितपत्र) को हकमा भने नेपाली भाषामा तयार गर्न अनिवार्य गरिएको छैन ।
बैंक तथा वित्तीय संस्थाले कर्जासँग सम्बन्धित ऋण प्रस्ताव पत्र (Offer Letter), कर्जा तमसुक (Loan Deed), धितोबन्धक लिखत (Mortgage Deed), Hypothecation Agreement र Trust Receipt Agreement अनिवार्यरुपमा देवनागरी लिपि नेपाली भाषामा तयार गर्नुपर्नेछ र Consortium Loan Agreement, Letter of Assignment, Letter of Guarantee को हकमा हाललाई अंग्रेजी भाषामा समेत तयार गर्न सकिने छ । साथै, यी कागजातहरुलाई पनि क्रमिक रुपमा नेपाली भाषामा तयार गर्ने संस्थागत व्यवस्था गर्नुपर्नेछ ।
लिखत/जमानीपत्र तयार गर्दा जमानी रकम, ऋणको अवधि, ऋणको प्रयोजन, प्रमुख ऋणी, साक्षी, जमानतकर्ताको नाम, ठेगाना, सो को सनाखत लगायतका विषयहरु तथा अन्य प्रकारका लिखतहरुमा समेत देहायबमोजिमका विषयहरुलाई यथोचित स्थानमा अनिवार्य रुपमा उल्लेख गर्नु पर्नेछ ।
लिखतमा स्पष्टसँग उल्लेख हुनुपर्ने विषय :
(१) सम्बन्धित व्यक्तिको नाम, ठेगाना, मिति, व्यक्तिको हकमा नागरिकता/पासपोर्ट नम्बर तथा तीन पुस्ते,
(२) म्याद, अवधि, प्रयोजन,
(३) सम्बन्धित व्यक्तिको सम्बन्धमा बैंक तथा वित्तीय संस्थाद्वारा सनाखत,
(४) रकम,
(५) साक्षी (Witness),
(६) हस्ताक्षर पहिचान गर्ने प्रयोजनको लागि सम्बन्धित कारणीको नाम,
(७) अन्य आवश्यक देखिएका विषयहरु ।
(ख) इजाजतपत्रप्राप्त संस्थाले अन्तर्राष्ट्रिय कारोबारमा प्रयोग हुने बाहेकका पत्राचार, चेक/भौचर लगायत अन्य कागजातहरु देवनागरी लिपि नेपाली भाषामा समेत उपलब्ध हुने व्यवस्था अनिवार्य रुपमा गर्नु गराउनु पर्नेछ ।
Controlled English translation
(a) Whenever a bank or financial institution extends any type of credit, documents prepared or caused to be prepared by the borrower and guarantor (person/firm/company/institution) and by the executing party (including the borrower/guarantor), including any deed, guarantee deed or consent deed, shall be prepared in Nepali in Devanagari script in accordance with prevailing law. Documents so prepared in Nepali may also be translated into English and retained in the records.
Documents used only in transactions with foreign citizens or in foreign banking transactions, such as letters of credit, are not required to be prepared in Nepali.
A bank or financial institution shall mandatorily prepare in Nepali in Devanagari script the Offer Letter, Loan Deed, Mortgage Deed, Hypothecation Agreement and Trust Receipt Agreement relating to credit. For the time being, Consortium Loan Agreements, Letters of Assignment and Letters of Guarantee may also be prepared in English. Institutional arrangements shall progressively be made to prepare these documents in Nepali as well.
When preparing a deed/guarantee document, the guarantee amount, loan period, purpose of the loan, principal borrower, witnesses, name and address of the guarantor and identification particulars, and in other deeds the following matters, shall be mandatorily stated in the appropriate place.
Matters to be clearly stated in the deed:
(1) name, address and date of the concerned person and, in the case of an individual, citizenship/passport number and three-generation particulars;
(2) term, period and purpose;
(3) identification of the concerned person by the bank or financial institution;
(4) amount;
(5) witness;
(6) name of the concerned executing person for purposes of identifying the signature;
(7) other matters considered necessary.
(b) A licensed institution shall mandatorily arrange that correspondence, cheques/vouchers and other documents, except those used in international transactions, are also available in Nepali in Devanagari script.
SWIFT (Society for Worldwide Interbank Financial Telecommunication) प्रविधि जडान गरेका बैंक तथा वित्तीय संस्थाले SWIFT Message को माध्यमबाट यस बैंकसँग कारोबार गर्दा देहायबमोजिम गरिएको छ :
क. यस्तो कारोबारका लागि आइतबारदेखि बिहीबारसम्म अपरान्ह ३:०० बजेसम्म रकमान्तरको लागि अनुरोध भई आएमा सोही दिन रकमान्तर गरिने ।
ख. अपरान्ह ३:०० बजे पछि, रकमान्तरको लागि अनुरोध भई आएको अवस्थामा सो दिन पछिको अर्को कार्य दिनमा रकमान्तर गरिने ।
ग. शुक्रवार दिनको १२:०० बजेसम्म रकमान्तरको लागि अनुरोध भई आएमा सोही दिन रकमान्तर गरिने ।
घ. शुक्रवार दिनको १२:०० बजे पछि रकमान्तरको लागि अनुरोध भई आएको अवस्थामा सो दिन पछिको अर्को कार्य दिनमा रकमान्तर गरिने ।
Controlled English translation
A bank or financial institution connected to SWIFT (Society for Worldwide Interbank Financial Telecommunication) shall, when transacting with this Bank through a SWIFT Message, follow:
(a) where a remittance request is received by 3:00 p.m. Sunday through Thursday, the remittance shall be made on the same day;
(b) where the request is received after 3:00 p.m., the remittance shall be made on the next working day;
(c) where the request is received by 12:00 noon on Friday, the remittance shall be made on the same day;
(d) where the request is received after 12:00 noon on Friday, the remittance shall be made on the next working day.
नेपालबाट विदेशमा पुँजीगत लगानी गर्ने गरी पुँजी खाता खुल्ला नगरिएतापनि इजाजतपत्रप्राप्त “क” वर्गका वाणिज्य बैंकहरुले आफ्नो प्रबन्धपत्रमा उल्लेखित विषयमा यस बैंकको पूर्व स्वीकृति लिई विदेशमा पुँजीगत लगानी नहुने गरी विदेशी बैंक तथा वित्तीय संस्थाहरुलाई गैरकोषीय आधारमा प्राविधिक सेवा (Technical Service) प्रदान गर्न सक्नेछन् ।
Controlled English translation
Although the capital account has not been opened so as to permit capital investment abroad from Nepal, a Class “A” commercial bank may, with prior approval of this Bank and in relation to matters stated in its memorandum, provide Technical Services to foreign banks and financial institutions on a non-fund-based basis without making capital investment abroad.
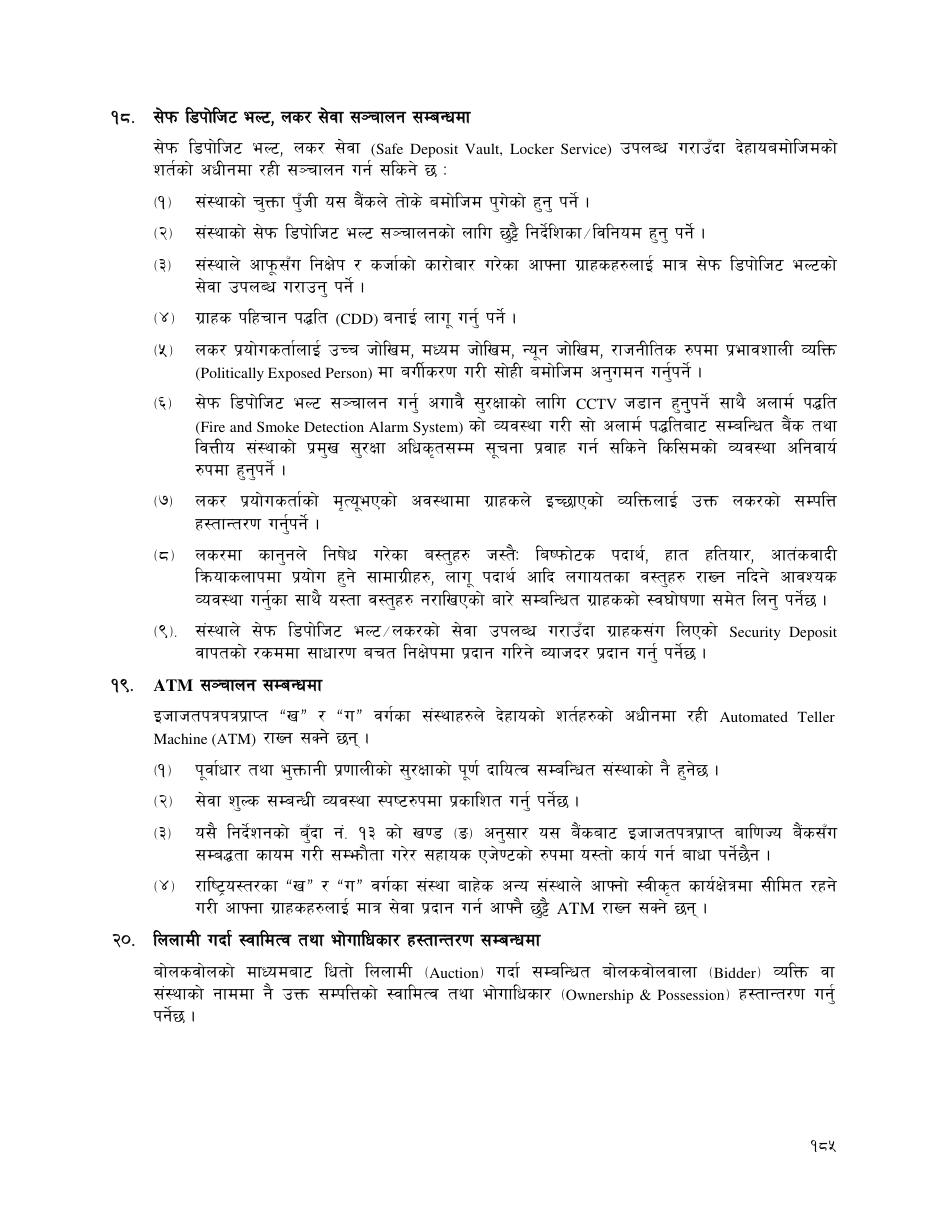
सेफ डिपोजिट भल्ट, लकर सेवा (Safe Deposit Vault, Locker Service) उपलब्ध गराउँदा देहायबमोजिमको शर्तको अधीनमा रही सञ्चालन गर्न सकिने छ :
(१) संस्थाको चुक्ता पुँजी यस बैंकले तोके बमोजिम पुगेको हुनु पर्ने ।
(२) संस्थाको सेफ डिपोजिट भल्ट सञ्चालनको लागि छुट्टै निर्देशिका/विनियम हुनु पर्ने ।
(३) संस्थाले आफूसँग निक्षेप र कर्जाको कारोबार गरेका आफ्ना ग्राहकहरुलाई मात्र सेफ डिपोजिट भल्टको सेवा उपलब्ध गराउनु पर्ने ।
(४) ग्राहक पहिचान पद्धति (CDD) बनाई लागू गर्नु पर्ने ।
(५) लकर प्रयोगकर्तालाई उच्च जोखिम, मध्यम जोखिम, न्यून जोखिम, राजनीतिक रुपमा प्रभावशाली व्यक्ति (Politically Exposed Person) मा वर्गीकरण गरी सोही बमोजिम अनुगमन गर्नु पर्ने ।
(६) सेफ डिपोजिट भल्ट सञ्चालन गर्नु अगावै सुरक्षाको लागि CCTV जडान हुनुपर्ने साथै अलार्म पद्धति (Fire and Smoke Detection Alarm System) को व्यवस्था गरी सो अलार्म पद्धतिबाट सम्बन्धित बैंक तथा वित्तीय संस्थाको प्रमुख सुरक्षा अधिकृतसम्म सूचना प्रवाह गर्न सकिने किसिमको व्यवस्था अनिवार्य रुपमा हुनुपर्ने ।
(७) लकर प्रयोगकर्ताको मृत्यु भएको अवस्थामा ग्राहकले इच्छाएको व्यक्तिलाई उक्त लकरको सम्पत्ति हस्तान्तरण गर्नुपर्ने ।
(८) लकरमा कानुनले निषेध गरेका वस्तुहरु जस्तै: विस्फोटक पदार्थ, हात हतियार, आतंकवादी क्रियाकलापमा प्रयोग हुने सामाग्रीहरु, लागू पदार्थ आदि लगायतका वस्तुहरु राख्न नदिने आवश्यक व्यवस्था गर्नुपर्ने साथै यस्ता वस्तुहरु नराखिएको बारे सम्बन्धित ग्राहकबाट स्वघोषणा समेत लिनुपर्ने ।
(९) संस्थाले सेफ डिपोजिट भल्ट/लकरको सेवा उपलब्ध गराउँदा ग्राहकसँग लिएको Security Deposit वापतको रकममा साधारण बचत निक्षेपमा प्रदान गरिने ब्याजदर प्रदान गर्नु पर्नेछ ।
Controlled English translation
Safe Deposit Vault / Locker Service may be operated subject to the following conditions:
(1) the institution shall have met the paid-up capital prescribed by this Bank;
(2) the institution shall have separate directives/regulations for operation of the Safe Deposit Vault;
(3) the service shall be provided only to the institution’s own customers who maintain deposit or credit transactions with it;
(4) a Customer Due Diligence (CDD) system shall be established and implemented;
(5) locker users shall be classified as high risk, medium risk, low risk or Politically Exposed Persons and monitored accordingly;
(6) CCTV shall be installed before operation, together with a Fire and Smoke Detection Alarm System capable of transmitting an alert to the chief security officer of the concerned bank or financial institution;
(7) on the death of a locker user, the locker property shall be transferred to the person nominated by the customer;
(8) arrangements shall prevent prohibited items such as explosives, weapons, materials used in terrorist activities and narcotic substances from being stored, and a self-declaration shall be obtained from the customer confirming that such items are not stored;
(9) the Security Deposit taken from a customer for the service shall earn the interest rate provided on an ordinary savings deposit.
इजाजतपत्रप्राप्त “ख” र “ग” वर्गका संस्थाहरुले देहायको शर्तहरुको अधीनमा रही Automated Teller Machine (ATM) राख्न सक्ने छन् ।
(१) पूर्वाधार तथा भुक्तानी प्रणालीको सुरक्षाको पूर्ण दायित्व सम्बन्धित संस्थाको नै हुनेछ ।
(२) सेवा शुल्क सम्बन्धी व्यवस्था स्पष्ट रुपमा प्रकाशित गर्नु पर्नेछ ।
(३) यसै निर्देशनको बुँदा नं. १३ को खण्ड (ङ) अनुसार यस बैंकबाट इजाजतपत्रप्राप्त वाणिज्य बैंकसँग सम्झौता कायम गरी सम्झौता गरेर सहायक एजेन्टको रुपमा यस्तो कार्य गर्न बाधा परेको मानिने छैन ।
(४) राष्ट्रियस्तरका “ख” र “ग” वर्गका संस्था बाहेक अन्य संस्थाले आफ्नो स्वीकृत कार्यक्षेत्रमा सीमित रहने गरी आफ्ना ग्राहकहरुलाई मात्र सेवा प्रदान गर्न आफैले छुट्टै ATM राख्न सक्ने छन् ।
Controlled English translation
Class “B” and “C” licensed institutions may operate Automated Teller Machines (ATMs) subject to:
(1) full responsibility for the security of infrastructure and the payment system resting with the concerned institution;
(2) clear publication of service-charge arrangements;
(3) nothing preventing the institution from performing this activity as a sub-agent under an agreement with a commercial bank licensed by this Bank pursuant to Clause 13(e);
(4) institutions other than national-level Class “B” and “C” institutions may maintain their own separate ATMs only within their approved area of operation and only to serve their own customers.
बोलकबोलको माध्यमबाट धितो लिलामी (Auction) गर्दा सम्बन्धित बोलकबोलवाला (Bidder) व्यक्ति वा संस्थाको नाममा नै उक्त सम्पत्तिको स्वामित्व तथा भोगाधिकार (Ownership & Possession) हस्तान्तरण गर्नु पर्नेछ ।
Controlled English translation
When collateral is auctioned through bidding, ownership and possession of the property shall be transferred in the name of the concerned successful bidder person or institution.
इजाजतपत्रप्राप्त संस्थाहरुको साधारण शेयर तथा संस्थापक शेयरमा कारवाहीमा परेका व्यक्ति र निजको एकाघर परिवारले लगानी गरेको अवस्थामा त्यस्ता साधारण/संस्थापक शेयरहरु जफत गरी लिलाम गर्ने र त्यसरी प्राप्त हुन आउने रकम कर्जा चुक्ता गर्ने प्रयोजनका लागि उपयोग गर्नु पर्नेछ ।
Controlled English translation
Where a person subject to action, or a member of that person’s same-household family, has invested in ordinary shares or promoter shares of a licensed institution, such ordinary/promoter shares shall be seized and auctioned and the proceeds shall be used for repayment of credit.
इजाजतपत्रप्राप्त संस्थाहरुको साइनबोर्ड तथा लेटरहेड हेर्दा स्पष्ट रुपमा कुन वर्ग तथा कति जिल्लामा कार्य क्षेत्र भएको वित्तीय संस्था हो भनी छुट्याउन कठिन भई सर्वसाधारण जनतामा भ्रम पर्न सक्ने अवस्था देखिएको हुँदा यस बैंकबाट इजाजतपत्रप्राप्त संस्थाहरुले आफ्नो साइनबोर्ड तथा लेटरहेडमा संस्थाको नामको ठीक तल अनिवार्यरुपमा कोष्ठकमा देहायबमोजिमको वर्गीकरण उल्लेख गर्नु/गराउनु पर्नेछ ।
इजाजतपत्रप्राप्त संस्था | उल्लेख गर्नु पर्ने वाक्यांश
इजाजतपत्रप्राप्त “क” वर्गका संस्थाहरुले | नेपाल राष्ट्र बैंकबाट “क” वर्गको इजाजतपत्रप्राप्त संस्था
इजाजतपत्रप्राप्त “ख” वर्गका संस्थाहरुले | नेपाल राष्ट्र बैंकबाट “ख” वर्गको इजाजतपत्रप्राप्त संस्था (..... जिल्ला कार्य क्षेत्र भएको)
इजाजतपत्रप्राप्त “ग” वर्गका संस्थाहरुले | नेपाल राष्ट्र बैंकबाट “ग” वर्गको इजाजतपत्रप्राप्त संस्था (..... जिल्ला कार्य क्षेत्र भएको)
नोट: राष्ट्रियस्तरका वित्तीय संस्थाहरुले कार्यक्षेत्र सम्बन्धी विवरण उल्लेख गर्न अनिवार्य हुने छैन ।
Controlled English translation
Because signboards and letterheads may otherwise make it difficult for the public to identify the licence class and district area of operation of a financial institution, licensed institutions shall mandatorily state immediately below the institution’s name, in brackets, the following:
Licensed institution | Required wording
Class “A” | Institution licensed by Nepal Rastra Bank as Class “A”
Class “B” | Institution licensed by Nepal Rastra Bank as Class “B” (area of operation: ..... districts)
Class “C” | Institution licensed by Nepal Rastra Bank as Class “C” (area of operation: ..... districts)
Note: National-level financial institutions are not required to state the area-of-operation particulars.
(१) इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाले रु. ५ लाख वा सोभन्दा बढीको रकम भुक्तानी गर्दा अनिवार्य रुपमा एकाउन्टपेयी चेक मार्फत वा सम्बन्धित व्यक्तिको खातामा मात्र भुक्तानी गर्नु पर्नेछ । साथै, फर्म, कम्पनी, संस्था वा कार्यालयको नाममा खिचिएका चेकहरुको भुक्तानी समेत एकाउन्टपेयी हुनु पर्नेछ । तर, देहायको अवस्थामा उल्लेखित सीमाभन्दा बढीको रकम नगद भुक्तानी गर्न बाधा पर्ने छैन:
(क) कुनै निक्षेपकर्ता वा बचतकर्ताले कुनै खास खातामा रहेको जम्मा रकम भुक्तानी लिन दिएको निवेदनको व्यहोरा र कारण मनासिब देखिएमा त्यस्तो निक्षेपकर्ता वा बचतकर्तालाई उल्लेखित सीमाभन्दा बढी नगद भुक्तानी गर्न ।
(बैंक तथा वित्तीय संस्थाले यस व्यवस्था बमोजिम नगद भुक्तानी दिएको मासिक विवरण अर्धवार्षिक गर्नु पर्नेछ ।)
प्रष्टीकरण:
यस प्रयोजनका लागि प्राथमिकताप्राप्त पूर्वाधार आयोजनाहरु जस्तै जलविद्युत, सडक, सञ्चार जस्ता क्षेत्रहरुमा कर्मचारी तथा श्रमिकहरुको पारिश्रमिक, ज्याला भुक्तानी गर्न, नेपाल सरकारका विभिन्न निकाय तथा विभिन्न आयोजनाहरुमा आवश्यक मालसामानहरुको आपूर्ति गर्न, नेपाल सरकारलाई बुझाउनु पर्ने राजस्व भुक्तानी गर्न, कानुनी कारोबारको सिलसिलामा बिगो/धरौटी/जमानत रकम जम्मा गर्न, पेन्सन रकम भुक्तानी गर्न, नेपाल सरकार मार्फत राष्ट्रिय विपत्तिको राहतमा गर्ने राहत, अनुदान वा सहायता वितरण गर्न, विप्रेषण कम्पनी/एजेन्टहरुले विप्रेषण प्राप्त गर्ने व्यक्तिहरुलाई रकम भुक्तानी गर्न, बचत तथा ऋण सहकारी संस्थालाई आफ्ना सदस्यहरुसँगको दैनिक कारोबारको भुक्तानी गर्न निवेदन लिई उल्लेखित सीमाभन्दा बढी नगद भुक्तानी दिन सकिनेछ । यस अनुसार भुक्तानी भएको रकमको विवरण सम्बन्धित बैंक तथा वित्तीय संस्थामा बुझाउनु पर्नेछ ।
(ख) यस बैंकबाट इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाबीच दैनिक कारोबार सञ्चालनका लागि नगद कारोबार गर्न ।
(२) बैंक वा वित्तीय संस्थाले खिच्ने चेकको अग्रभागको माथिपट्टिको खाली स्थानमा अनिवार्यरुपमा चेक राइटर, चेक पञ्च, चेक प्रोटेक्टर वा रिबन राइटर लगाउनु पर्नेछ ।
(३) विनिमय अधिकार पत्र ऐन, २०३४ को दफा ६ मा भएको व्यवस्था बमोजिम कुनै पनि चेकमा अंक र अक्षरमा रकम फरक परेमा अक्षरमा लेखिए अनुसारको रकमलाई मान्यता दिनु पर्नेछ ।
(४) चेकको अग्रभागमा रेखाङ्कन (Crossing) वा रेखाङ्कन सम्बन्धी छाप र मुन्द्राको छाप बाहेक अन्य कुनै किसिमको छाप लगाएको चेकको भुक्तानी गर्न सम्बन्धित संस्था बाध्य हुने छैन ।
(५) च्यातिएका, मसी लागेका, केरेमेट भएका चेकको भुक्तानी गर्न सम्बन्धित संस्था बाध्य हुने छैन ।
(६) भुक्तानीको लागि प्राप्त चेक नेपाली वा अंग्रेजी मध्ये कुनै एक भाषामा मात्र स्पष्ट रुपमा लेखिएको हुनुपर्नेछ ।
(७) संस्थाको नाममा खिचिएका चेक सम्बन्धित संस्था आफैले खातामा जम्मा गर्न पठाउँदा सम्बन्धित संस्थाको प्रष्ट बुझिने छाप चेकको पछाडि अनिवार्य रुपमा लगाएको हुनुपर्नेछ । तर सम्बन्धित संस्थाको लागि अन्य व्यक्ति, फर्म, कम्पनी वा संस्थाले त्यस्तो चेक खातामा जम्मा गरिदिँदा भने छाप लगाउन अनिवार्य हुने छैन ।
(८) किस्तावारी मार्फत प्राप्त नेपाल राष्ट्र बैंकका चेकको रकम जसको नाममा चेक खिचिएको हो, उसैको नामको खातामा जम्मा गरिदिनुपर्नेछ ।
(९) यस बैंकबाट जारी इलेक्ट्रोनिक क्लियरिङ सम्बन्धमा जारी निर्देशन तथा मार्गदर्शनहरुको पालना नभएका चेकहरुको क्लियरिङ तथा भुक्तानी गर्न सम्बन्धित संस्था बाध्य हुने छैन ।
Controlled English translation
(1) When a licensed bank or financial institution makes payment of NPR 500,000 or more, payment shall mandatorily be made through an account-payee cheque or only to the account of the concerned person. Cheques drawn in the name of a firm, company, institution or office shall likewise be account-payee. However, cash above the stated limit may be paid in the following circumstances:
(a) where a depositor or saver applies for payment of an amount held in a particular account and the circumstances and reasons stated in the application are considered reasonable.
The bank or financial institution shall maintain half-yearly particulars of monthly cash payments made under this provision.
Explanation:
For this purpose, cash exceeding the stated limit may, upon application, be paid for employee and labour remuneration/wages in priority infrastructure projects such as hydropower, roads and communications; supply of goods to Government bodies and projects; payment of Government revenue; deposit of amounts relating to legal proceedings, security or guarantees; pension payments; national-disaster relief, grants or assistance distributed through the Government; remittance payments by remittance companies/agents; and daily member transactions of savings and credit cooperatives, as listed in the preceding Nepali provision. Details of amounts so paid shall be submitted to the concerned bank or financial institution.
(b) cash transactions for daily business between banks and financial institutions licensed by this Bank.
(2) A cheque drawn by a bank or financial institution shall mandatorily use a cheque writer, cheque punch, cheque protector or ribbon writer in the blank area at the upper front of the cheque.
(3) Pursuant to Section 6 of the Negotiable Instruments Act, 2034, where the amount in figures differs from the amount in words, the amount written in words shall prevail.
(4) A bank or financial institution is not obliged to pay a cheque bearing on its face a stamp other than a Crossing/crossing-related stamp or the customary institutional stamp.
(5) A bank or financial institution is not obliged to pay a torn, ink-stained or altered cheque.
(6) A cheque presented for payment shall be clearly written entirely in either Nepali or English.
(7) Where a cheque drawn in the name of an institution is deposited by that institution itself, a clearly identifiable stamp of the institution shall mandatorily be affixed to the reverse. Where another person, firm, company or institution deposits it on behalf of the concerned institution, the stamp is not mandatory.
(8) The proceeds of a Nepal Rastra Bank cheque received through the specified mechanism shall be credited to the account of the person in whose name the cheque is drawn.
(9) A bank or financial institution is not obliged to clear or pay a cheque that does not comply with the electronic-clearing directives and guidelines issued by this Bank.
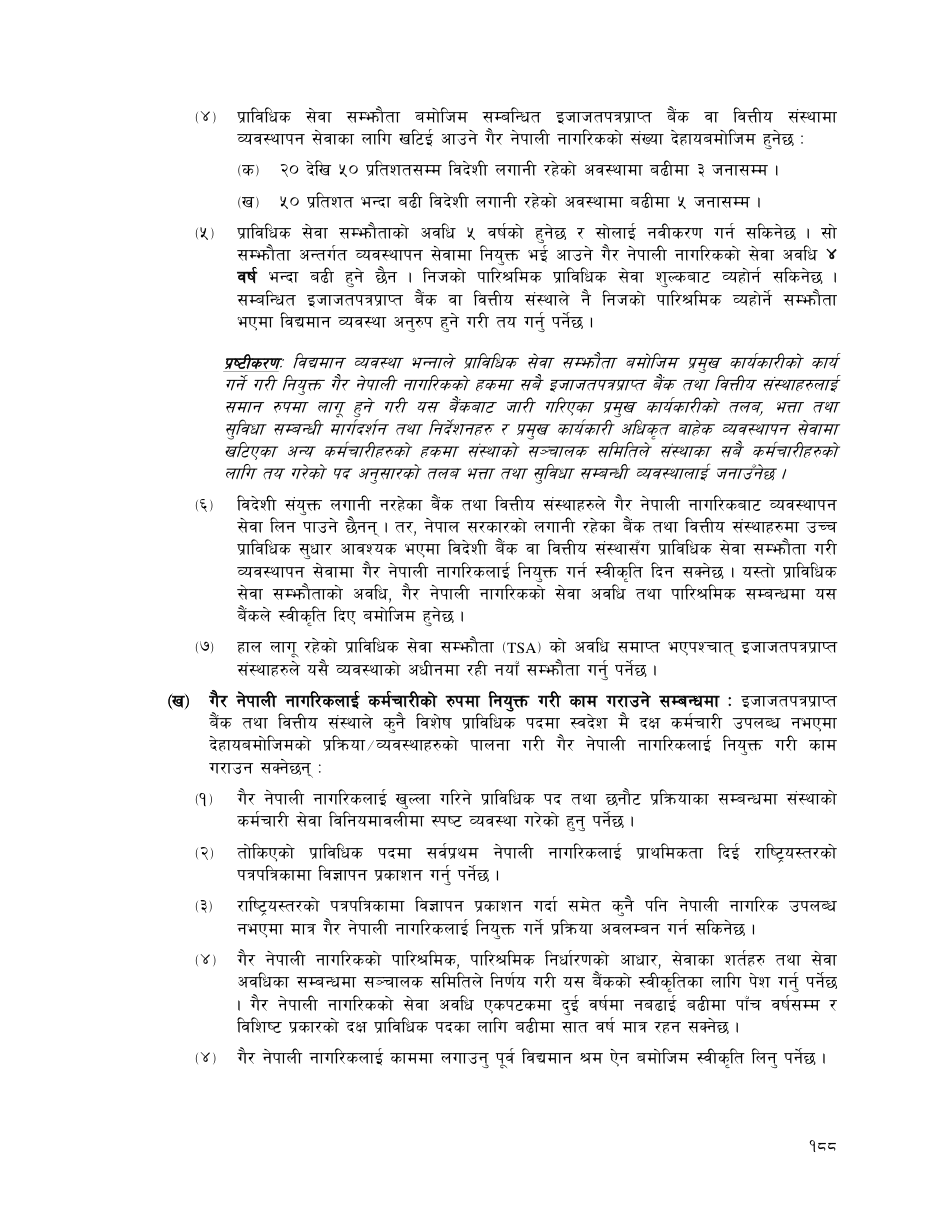
इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाले देहायबमोजिमका व्यवस्थाको अधीनमा रही गैर नेपाली नागरिकहरुलाई नियुक्त गरी काम गराउन सक्नेछन् :
(क) गैर नेपाली नागरिकबाट व्यवस्थापन सेवा लिने सम्बन्धमा : इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाहरुले निम्न बमोजिमको प्राविधिक सेवा सम्झौता (Technical Service Agreement, TSA) गरी गैर नेपाली नागरिकबाट व्यवस्थापन सेवा लिन सक्नेछन् ।
(१) विदेशी संयुक्त लगानीमा सञ्चालित बैंक तथा वित्तीय संस्थाहरुले विदेशी लगानीकर्ता (Joint Venture Partner) सँग प्राविधिक सेवा सम्झौता (Technical Service Agreement, TSA) गरी प्रचलित इजाजतपत्र जारी निर्देशिका लगायत प्रचलित कानूनबमोजिम स्वीकृति लिएर मात्र व्यवस्थापन सेवा लिनु पर्नेछ ।
(२) प्राविधिक सेवा सम्झौता (TSA) मा निम्न विषयहरु खुलाउनु पर्नेछ ।
(क) प्राविधिक सेवा सम्झौता अन्तर्गत व्यवस्थापन सेवा लिने पद र संख्या ।
(ख) प्राविधिक सेवा प्रदान गर्ने विषय तथा योजनाहरु ।
(ग) प्राविधिक सेवा सम्झौताको अवधि तथा शुल्क ।
(घ) व्यवस्थापन सेवामा खटिई आउने गैर नेपाली नागरिकको पारिश्रमिक तथा सुविधा ।
(ङ) व्यवस्थापन सेवामा खटिई आउने गैर नेपाली नागरिकको पारिश्रमिक तथा सुविधा व्यहोर्ने स्रोत ।
(च) प्राविधिक सेवामा खटिई आउने गैर नेपाली नागरिकको सेवा अवधि ।
(छ) प्राविधिक सेवा सम्झौता बमोजिम कार्य नभएमा सोको क्षतिपूर्तिको व्यवस्था ।
(ज) अन्य आवश्यक विषय ।
(३) प्राविधिक सेवा सम्झौता (TSA) अन्तर्गत खटिई आउने गैर नेपाली नागरिकहरुको हकमा विद्यमान श्रम ऐन तथा नियमावली अनुसार श्रम स्वीकृति लिनुपर्ने व्यवस्था रहेकोले सोही बमोजिम स्वीकृति लिएर मात्र काम गर्नु/गराउनु पर्नेछ ।
(४) प्राविधिक सेवा सम्झौता बमोजिम सम्बन्धित इजाजतपत्रप्राप्त बैंक वा वित्तीय संस्थामा व्यवस्थापन सेवाका लागि खटिई आउने गैर नेपाली नागरिकको संख्या देहायबमोजिम हुनेछ :
(क) २० देखि ५० प्रतिशतसम्म विदेशी लगानी रहेको अवस्थामा बढीमा ३ जनासम्म ।
(ख) ५० प्रतिशत भन्दा बढी विदेशी लगानी रहेको अवस्थामा बढीमा ५ जनासम्म ।
(५) प्राविधिक सेवा सम्झौताको अवधि ५ वर्षको हुनेछ र सालैपिच्छे नवीकरण गर्न सकिनेछ । सो सम्झौता अन्तर्गत व्यवस्थापन सेवामा नियुक्त भई आउने गैर नेपाली नागरिकको सेवा अवधि ४ वर्ष भन्दा बढी हुने छैन । निजको पारिश्रमिक प्राविधिक सेवा शुल्कबाट व्यहोर्न सकिनेछ । सम्बन्धित इजाजतपत्रप्राप्त बैंक वा वित्तीय संस्थाले नै निजको पारिश्रमिक व्यहोर्ने सम्झौता भएमा विद्यमान व्यवस्था अनुरुप हुने गरी तय गर्नु पर्नेछ ।
(६) विदेशी संयुक्त लगानी नरहेका बैंक तथा वित्तीय संस्थाहरुले गैर नेपाली नागरिकबाट व्यवस्थापन सेवा लिन पाउने छैनन् । तर, नेपाल सरकारको लगानी रहेका बैंक तथा वित्तीय संस्थाहरुमा उच्च प्राविधिक सुधार आवश्यक भएमा विदेशी बैंक वा वित्तीय संस्थासँग प्राविधिक सेवा सम्झौता गरी व्यवस्थापन सेवामा गैर नेपाली नागरिकलाई नियुक्त गर्न सकिनेछ । यसका लागि सम्बन्धित बैंक वा वित्तीय संस्थाले गरेको प्राविधिक सेवा सम्झौताको अवधि, गैर नेपाली नागरिकको सेवा अवधि तथा पारिश्रमिक सम्बन्धमा यस बैंकले स्वीकृति दिए बमोजिम हुनेछ ।
(७) हाल लागू रहेको प्राविधिक सेवा सम्झौता (TSA) को अवधि समाप्त भएपश्चात् इजाजतपत्रप्राप्त संस्थाहरुले यसै व्यवस्थाको अधीनमा रही नयाँ सम्झौता गर्नु पर्नेछ ।
(ख) गैर नेपाली नागरिकलाई कर्मचारीको रुपमा नियुक्त गरी काम गराउन सक्ने सम्बन्धमा : इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाले कुनै विशेष प्राविधिक पदमा स्वदेशमै दक्ष कर्मचारी उपलब्ध नभएमा देहायबमोजिमको प्रक्रिया/व्यवस्थाहरुको पालना गरी गैर नेपाली नागरिकलाई नियुक्त गरी काम गराउन सक्नेछन् :
(१) गैर नेपाली नागरिकलाई खुल्ला गरिने प्राविधिक पद तथा छनौट प्रक्रियाका सम्बन्धमा संस्थाको कर्मचारी सेवा विनियमावलीमा स्पष्ट व्यवस्था गरेको हुनु पर्नेछ ।
(२) तोकिएको प्राविधिक पदमा सर्वप्रथम नेपाली नागरिकलाई प्राथमिकता दिई राष्ट्रियस्तरको पत्रपत्रिकामा विज्ञापन प्रकाशन गर्नु पर्नेछ ।
(३) राष्ट्रियस्तरको पत्रपत्रिकामा विज्ञापन प्रकाशन गर्दा समेत कुनै पनि नेपाली नागरिक उपलब्ध नभएमा मात्र गैर नेपाली नागरिकलाई नियुक्त गर्ने प्रक्रिया अवलम्बन गर्न सकिनेछ ।
(४) गैर नेपाली नागरिकको पारिश्रमिक, पारिश्रमिक निर्धारणको आधार, सेवाका शर्तहरु तथा सेवा अवधिका सम्बन्धमा सञ्चालक समितिले निर्णय गरी यस बैंकको स्वीकृतिका लागि पेश गर्नुपर्नेछ । गैर नेपाली नागरिकको सेवा अवधि एकपटकमा दुई वर्षमा नबढाई बढीमा पाँच वर्षसम्म र विशिष्ट प्रकारको दक्ष प्राविधिक पदका लागि बढीमा सात वर्ष मात्र रहन सक्नेछ ।
(५) गैर नेपाली नागरिकलाई काममा लगाउनु पूर्व विद्यमान श्रम ऐन बमोजिम स्वीकृति लिनु पर्नेछ ।
(६) इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाहरुले तोकिएको प्राविधिक पद बाहेक अन्य पदमा गैर नेपाली नागरिकलाई नियुक्त गरी काम गराउन पाउने छैनन् ।
Controlled English translation
A licensed bank or financial institution may appoint and employ non-Nepali citizens subject to the following provisions.
(a) Management services from non-Nepali citizens:
(1) A bank or financial institution operating with foreign joint investment may enter into a Technical Service Agreement (TSA) with the foreign investor (Joint Venture Partner) and obtain management services only after obtaining approval in accordance with prevailing licensing directives and law.
(2) The TSA shall state:
(a) the positions and number of persons through whom management services will be obtained;
(b) the subjects and plans for which technical services will be provided;
(c) the term and fee of the TSA;
(d) remuneration and facilities of non-Nepali citizens deployed for management service;
(e) the source from which such remuneration and facilities will be borne;
(f) the service period of the non-Nepali citizen;
(g) compensation arrangements if the TSA is not performed; and
(h) other necessary matters.
(3) Non-Nepali citizens deployed under a TSA shall obtain labour approval under prevailing labour law and regulations before being employed.
(4) The maximum number of non-Nepali citizens deployed for management services shall be:
(a) up to three persons where foreign investment is from 20 percent to 50 percent;
(b) up to five persons where foreign investment exceeds 50 percent.
(5) The TSA shall have a term of five years and may be renewed annually. A non-Nepali citizen appointed for management service under the TSA shall not serve for more than four years. Remuneration may be borne from the technical-service fee. Where the licensed institution itself bears the remuneration, it shall be fixed in accordance with prevailing arrangements.
(6) Banks and financial institutions without foreign joint investment shall not obtain management services from non-Nepali citizens. However, where a bank or financial institution with Government of Nepal investment requires significant technical reform, it may enter into a TSA with a foreign bank or financial institution and appoint non-Nepali citizens for management services, subject to approval of the TSA period, service period and remuneration by this Bank.
(7) After expiry of a currently applicable TSA, the licensed institution shall enter into a new agreement subject to this provision.
(b) Appointment of non-Nepali citizens as employees:
Where skilled personnel are not available domestically for a specialised technical position, a licensed bank or financial institution may appoint a non-Nepali citizen subject to:
(1) clear provisions in its Staff Service Regulations regarding the technical position and selection process;
(2) first giving priority to Nepali citizens and publishing a national-level vacancy notice;
(3) proceeding with appointment of a non-Nepali citizen only where no suitable Nepali citizen is available even after such publication;
(4) Board determination of remuneration, basis of remuneration, service conditions and service period, followed by submission for approval of this Bank; service shall not exceed two years at a time, five years in aggregate, or seven years for a highly specialised technical position;
(5) obtaining labour approval under prevailing labour law before employment; and
(6) not appointing non-Nepali citizens to positions other than the specified technical positions.
इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाहरुले रुग्ण उद्योगहरुको अभिलेख व्यवस्थापन, अनुगमन र समस्या समाधानमा सहयोग पुर्याउने प्रयोजनका लागि कर्जा विभाग अन्तर्गत एउटा छुट्टै रुग्ण उद्योग हेर्ने डेस्क तोक्नु पर्नेछ ।
Controlled English translation
Licensed banks and financial institutions shall designate a separate desk under the credit department for record management, monitoring and assistance in resolving problems of sick industries.
(क) इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाहरुले लघु, साना र मझौला उद्योगमा कर्जा प्रवाह तथा पहुँच वृद्धिको लागि कर्जा विभागअन्तर्गत एउटा छुट्टै डेस्क स्थापना गर्नु पर्नेछ ।
(ख) कृषि, लघु तथा घरेलु क्षेत्रमा कर्जा प्रवाहलाई थप प्रोत्साहित गर्न गाउँपालिका तथा नगरपालिकाको सरकारी कारोबार सञ्चालन गर्ने वाणिज्य बैंकका शाखाहरुमा कृषि, लघु तथा घरेलु कर्जासम्बन्धी फोकल डेस्कको स्थापना गर्नु पर्नेछ ।
Controlled English translation
(a) Licensed banks and financial institutions shall establish a separate desk under the credit department to increase the flow of and access to credit for micro, small and medium enterprises.
(b) To further promote lending to agriculture, micro and cottage sectors, commercial-bank branches conducting Government transactions for Rural Municipalities and Municipalities shall establish an agriculture, micro and cottage credit focal desk.
(क) नेपाल राष्ट्र बैंक ऐन, २०५८ को दफा ४९ र ५० मा भएको व्यवस्था अनुसार इजाजतपत्रप्राप्त “क”, “ख”, “ग” वर्गका बैंक तथा वित्तीय संस्थालाई नेपाल राष्ट्र बैंक, पुनर्कर्जा कार्यविधि, २०७७ मा उल्लिखित व्यवस्थाको अधीनमा रही पुनर्कर्जा सुविधा उपलब्ध गराइनेछ ।
(ख) बैंक तथा वित्तीय संस्थाले पुनर्कर्जा प्राप्त गरेका ऋणीको विवरण आफ्नो वेबसाइटमार्फत त्रैमासिक रुपमा सार्वजनिक गर्नु पर्नेछ ।
Controlled English translation
(a) Pursuant to Sections 49 and 50 of the Nepal Rastra Bank Act, 2058, refinance facilities shall be made available to Class “A”, “B” and “C” licensed banks and financial institutions subject to the Nepal Rastra Bank Refinance Procedure, 2077.
(b) A bank or financial institution shall publish quarterly on its website details of borrowers who have received refinance.
(क) नेपाल सरकार, मन्त्रिपरिषद्को मिति २०७७/०७/२७ को निर्णयबाट स्वीकृत “व्यवसायिक निरन्तरता कर्जा प्रवाह कार्यविधि, २०७७” मा उल्लिखित व्यवस्थाहरु तथा देहायबमोजिम प्रक्रिया पूरा गरी बैंक तथा वित्तीय संस्थाले व्यवसायिक निरन्तरता कर्जा प्रवाह गर्नु पर्नेछ :-
१) कार्यविधिको दफा ६ को उपदफा १ को व्यवस्था अनुसार देहायबमोजिमको व्यवसायिक निरन्तरता कर्जा सीमा स्वीकृत गर्नु पर्नेछ :-
(अ) अति प्रभावित क्षेत्र: श्रमिक वा कर्मचारीको वार्षिक पारिश्रमिक तथा सोको ५० प्रतिशत थप (व्यवसाय निरन्तरताको लागि) गरी कुल रकम वा अधिकतम दश करोड रुपैयाँसम्म ।
(आ) मध्यम प्रभावित क्षेत्र: श्रमिक वा कर्मचारीको वार्षिक पारिश्रमिक तथा सोको ५० प्रतिशत थप (व्यवसाय निरन्तरताको लागि) गरी कुल रकम वा अधिकतम सात करोड रुपैयाँसम्म ।
(इ) न्यून प्रभावित क्षेत्र: श्रमिक वा कर्मचारीको वार्षिक पारिश्रमिक तथा सोको ५० प्रतिशत थप (व्यवसाय निरन्तरताको लागि) गरी कुल रकम वा अधिकतम पाँच करोड रुपैयाँसम्म ।
२) यस्तो कर्जा आफ्नो प्राथमिक पुँजीको १० प्रतिशतसम्म मात्र प्रवाह गर्न सकिनेछ ।
३) सीमा स्वीकृत गर्दा कार्यविधिको दफा ६ को उपदफा २ को व्यवस्थाका साथै कार्यविधि बमोजिम प्रवाहित कुल कर्जाको ३० प्रतिशत रकम घरेलु, साना तथा मझौला उद्यमका लागि प्रवाह गर्नु पर्नेछ ।
४) यस्तो कर्जा प्रवाह गर्दा कर्जा सूचना शुल्क लगायत तेस्रो पक्षलाई भुक्तानी गर्नुपर्ने शुल्क बाहेक अन्य कुनै पनि किसिमको सेवा शुल्क लिन पाइने छैन ।
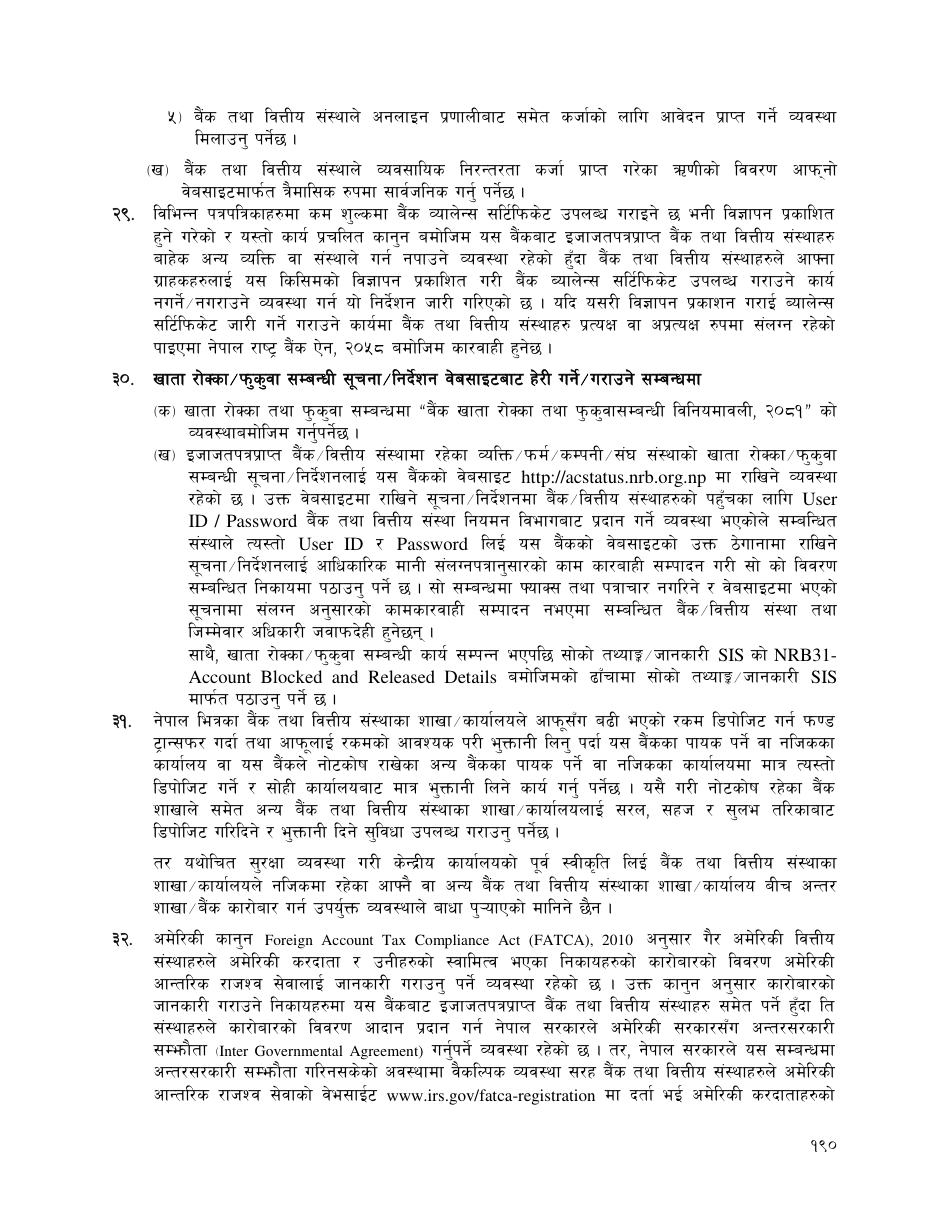
५) बैंक तथा वित्तीय संस्थाले अनलाइन प्रणालीबाट समेत कर्जाको लागि आवेदन प्राप्त गर्ने व्यवस्था मिलाउनु पर्नेछ ।
(ख) बैंक तथा वित्तीय संस्थाले व्यवसायिक निरन्तरता कर्जा प्राप्त गरेका ऋणीको विवरण आफ्नो वेबसाइटमार्फत त्रैमासिक रुपमा सार्वजनिक गर्नु पर्नेछ ।
Controlled English translation
(a) Banks and financial institutions shall extend Business Continuity Loans after completing the procedures under the “Business Continuity Loan Procedure, 2077” approved by the Government of Nepal, Council of Ministers, by decision dated 2077/07/27:
1) Credit limits under Section 6(1) shall be approved as follows:
(a) severely affected sector: annual remuneration of labourers/employees plus 50 percent for business continuity, or a maximum of NPR 100 million;
(b) moderately affected sector: annual remuneration plus 50 percent, or a maximum of NPR 70 million;
(c) less affected sector: annual remuneration plus 50 percent, or a maximum of NPR 50 million.
2) Such credit may be extended only up to 10 percent of the institution’s Tier 1 capital.
3) In addition to Section 6(2), 30 percent of total credit under the Procedure shall be directed to cottage, small and medium enterprises.
4) No service charge other than third-party charges, including credit-information fees, shall be collected.
5) Banks and financial institutions shall arrange to receive loan applications through an online system.
(b) Banks and financial institutions shall publish quarterly on their websites details of borrowers receiving Business Continuity Loans.
विभिन्न पत्रपत्रिकाहरुमा कम शुल्कमा बैंक ब्यालेन्स सर्टिफिकेट उपलब्ध गराइने छ भनी विज्ञापन प्रकाशित हुने गरेको र यस्तो कार्य प्रचलित कानुन बमोजिम यस बैंकबाट इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाहरु बाहेक अन्य व्यक्ति वा संस्थाले गर्न नपाउने व्यवस्था रहेको हुँदा बैंक तथा वित्तीय संस्थाहरुले आफ्ना ग्राहकहरुलाई यस किसिमको विज्ञापन प्रकाशित गराई बैंक ब्यालेन्स सर्टिफिकेट उपलब्ध गराउने कार्य नगर्न/नगराउने व्यवस्था गर्न यो निर्देशन जारी गरिएको छ । यदि यसरी विज्ञापन प्रकाशन गराई ब्यालेन्स सर्टिफिकेट जारी गर्ने/गराउने कार्यमा बैंक तथा वित्तीय संस्थाहरु प्रत्यक्ष वा अप्रत्यक्ष रुपमा संलग्न रहेको पाइएमा नेपाल राष्ट्र बैंक ऐन, २०५८ बमोजिम कारवाही हुनेछ ।
Controlled English translation
Advertisements have been published claiming that bank balance certificates can be obtained for low fees. As such activity may not be carried out under prevailing law by persons or institutions other than banks and financial institutions licensed by this Bank, banks and financial institutions shall ensure that their customers do not arrange such advertisements or obtain bank balance certificates through such arrangements. Where a bank or financial institution is found directly or indirectly involved in publication of such advertisements or issuance of such balance certificates, action shall be taken under the Nepal Rastra Bank Act, 2058.
(क) खाता रोक्का तथा फुकुवा सम्बन्धमा “बैंक खाता रोक्का तथा फुकुवासम्बन्धी विनियमावली, २०८१” को व्यवस्थाबमोजिम गर्नु/गराउनु पर्नेछ ।
(ख) इजाजतपत्रप्राप्त बैंक/वित्तीय संस्थामा रहेका व्यक्ति/फर्म/कम्पनी/संघ संस्थाको खाता रोक्का/फुकुवा सम्बन्धी सूचना/निर्देशनहरु यस बैंकको वेबसाइट http://aestatus.nrb.org.np मा राखिने व्यवस्था रहेको हुँदा उक्त वेबसाइटमा राखिने सूचना/निर्देशनमा बैंक/वित्तीय संस्थाको पहुँचका लागि User ID/Password प्रदान गरिनेछ । सम्बन्धित संस्थाले उक्त प्रणाली प्रयोग गरी आफ्नो तोकिएको कर्मचारीमार्फत आवश्यक काम कारवाही सम्पन्न गरी सोको विवरण सम्बन्धित निकायमा पठाउनु पर्नेछ । वेबसाइटमार्फत प्राप्त सूचना/निर्देशन अनुसारको काम कारवाही सम्पन्न नगरेमा सम्बन्धित बैंक/वित्तीय संस्था तथा जिम्मेवार कर्मचारीलाई कारवाही हुनेछ ।
साथै, खाता रोक्का/फुकुवा सम्बन्धी कार्य सम्पन्न भएपछि सोको तथ्याङ्क/जानकारी SIS को NRB31-Account Blocked and Released Details बमोजिमको ढाँचामा SIS मार्फत पेश गर्नु पर्नेछ ।
Controlled English translation
(a) Account freezing and release shall be carried out in accordance with the Bank Account Freeze and Release Regulations, 2081.
(b) Freeze/release notices and instructions concerning accounts of persons, firms, companies and associations held with licensed banks/financial institutions are made available through http://aestatus.nrb.org.np. User IDs/passwords shall be provided for access. The concerned institution shall use the system, act through designated staff and send the required details to the concerned authority. Failure to implement the website notice/instruction shall result in action against the institution and the responsible employee.
After completion of freeze/release action, information shall be submitted through SIS in the NRB31 — Account Blocked and Released Details format.
नेपाल भित्रका बैंक तथा वित्तीय संस्थाका शाखा/कार्यालयले आफूसँग बढी भएको रकम डिपोजिट गर्न फण्ड ट्रान्सफर गर्दा तथा आफूलाई रकमको आवश्यक परी भुक्तानी लिनु पर्दा यस बैंकका पायक पर्ने वा नजिकका कार्यालयमा गई रकम बैंकको रोहवरमा जम्मा/भुक्तानी गर्न वा नजिकका बैंकबाट डिपोजिट गरी सोही कार्यालयबाट मात्र भुक्तानी लिने कार्य गर्नु पर्नेछ । यसै गरी तोकिएको बैंक शाखाले समेत अन्य बैंक तथा वित्तीय संस्थाका शाखा/कार्यालयलाई सरल, सहज र सुलभ तरिकाबाट डिपोजिट/भुक्तानी दिने सुविधा उपलब्ध गराउनु पर्नेछ ।
तर पर्याप्त सुरक्षा व्यवस्था गरी केन्द्रीय कार्यालयको पूर्व स्वीकृति लिई बैंक तथा वित्तीय संस्थाका शाखा/कार्यालयले नजिकका अन्य बैंक वा आफ्नै बैंक तथा वित्तीय संस्थाका शाखा/कार्यालयबीच अन्तर शाखा/बैंक कारोबार गर्न उपर्युक्त व्यवस्थाले बाधा पुर्याएको मानिने छैन ।
Controlled English translation
Branches/offices of banks and financial institutions in Nepal shall follow the prescribed arrangements for depositing excess cash or obtaining required cash through a convenient/nearby office of this Bank or through the designated nearby bank/office. The designated bank branch shall provide other banks and financial institutions with simple, convenient and accessible deposit/payment facilities.
However, with adequate security arrangements and prior approval of the central office, nothing in this provision prevents inter-branch/inter-bank transactions with nearby banks or branches/offices of the same bank or financial institution.
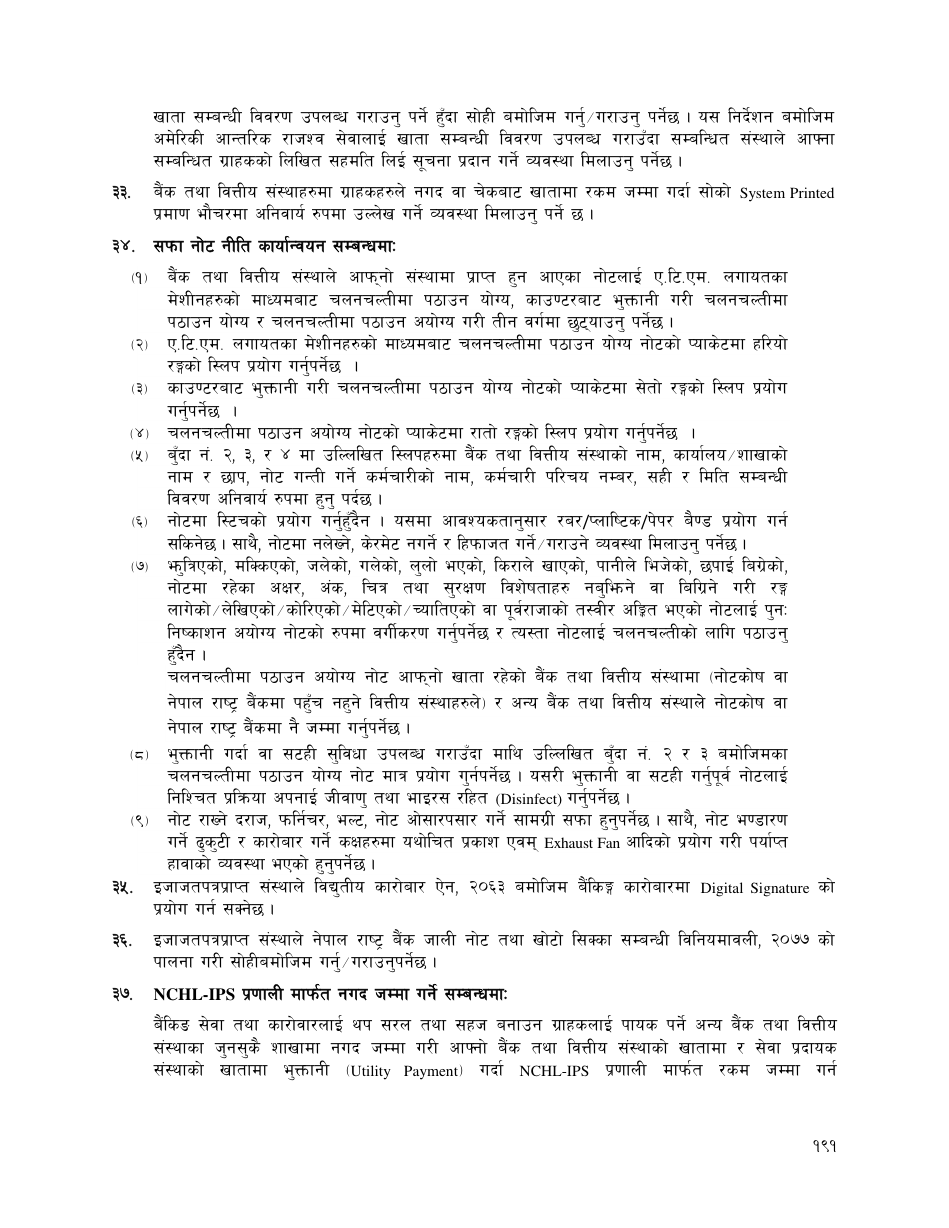
अमेरिकी कानून Foreign Account Tax Compliance Act (FATCA), 2010 अनुसार गैर अमेरिकी वित्तीय संस्थाले अमेरिकी करदाता र उनीहरुको स्वामित्व भएका निकायहरुको कारोबारको विवरण अमेरिकी आन्तरिक राजस्व सेवालाई जानकारी गराउनु पर्ने व्यवस्था रहेको छ । उक्त कानुन अनुसार कारोबारको जानकारी गराउने निकायहरुमा यस बैंकबाट इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाहरु समेत पर्ने हुँदा नेपाल सरकार र अमेरिकी सरकारबीच अन्तरसरकारी सम्झौता (Inter Governmental Agreement) नभएको अवस्थामा बैंक तथा वित्तीय संस्थाहरुले अमेरिकी आन्तरिक राजस्व सेवाको वेबसाइट www.irs.gov/fatca-registration मा दर्ता भई अमेरिकी करदाताहरुको खाता सम्बन्धी विवरण उपलब्ध गराउनु पर्नेछ । यस निर्देशन बमोजिम अमेरिकी आन्तरिक राजस्व सेवालाई खाता सम्बन्धी विवरण उपलब्ध गराउँदा सम्बन्धित संस्थाले आफ्ना सम्बन्धित ग्राहकको लिखित सहमति लिई सूचना प्रदान गर्ने व्यवस्था मिलाउनु पर्नेछ ।
Controlled English translation
Under the United States Foreign Account Tax Compliance Act (FATCA), 2010, non-U.S. financial institutions are required to report information concerning U.S. taxpayers and entities owned by them to the U.S. Internal Revenue Service. As banks and financial institutions licensed by this Bank are reporting institutions and, where there is no applicable Inter Governmental Agreement between Nepal and the United States, such institutions shall register at www.irs.gov/fatca-registration and provide the required U.S.-taxpayer account information. When providing account information under this Directive, the institution shall obtain the written consent of the concerned customer before disclosure.
बैंक तथा वित्तीय संस्थाहरुमा ग्राहकहरुले नगद वा चेकबाट खातामा रकम जम्मा गर्दा सोको System Printed प्रमाण भौचरमा अनिवार्य रुपमा उल्लेख गर्ने व्यवस्था मिलाउनु पर्नेछ ।
Controlled English translation
When customers deposit cash or cheques into an account with a bank or financial institution, arrangements shall be made so that System Printed evidence of the transaction is mandatorily stated on the voucher.
(१) बैंक तथा वित्तीय संस्थाले आफ्नो संस्थामा प्राप्त हुन आएका नोटलाई ए.टी.एम. लगायतका मेसिनहरुको माध्यमबाट चलनचल्तीमा पठाउन योग्य, काउन्टरबाट भुक्तानी गरी चलनचल्तीमा पठाउन योग्य र चलनचल्तीमा पठाउन अयोग्य गरी तीन वर्गमा छुट्याउनु पर्नेछ ।
(२) ए.टी.एम. लगायतका मेसिनहरुको माध्यमबाट चलनचल्तीमा पठाउन योग्य नोटको प्याकेटमा हरियो रङको स्लिप प्रयोग गर्नुपर्नेछ ।
(३) काउन्टरबाट भुक्तानी गरी चलनचल्तीमा पठाउन योग्य नोटको प्याकेटमा सेतो रङको स्लिप प्रयोग गर्नुपर्नेछ ।
(४) चलनचल्तीमा पठाउन अयोग्य नोटको प्याकेटमा रातो रङको स्लिप प्रयोग गर्नुपर्नेछ ।
(५) बुँदा नं. २, ३ र ४ मा उल्लिखित स्लिपहरुमा बैंक तथा वित्तीय संस्थाको नाम, कार्यालय/शाखाको नाम र छाप, नोट गणना गर्ने कर्मचारीको नाम, कर्मचारी परिचय नम्बर, सही र मिति सम्बन्धी विवरण अनिवार्य रुपमा हुनुपर्नेछ ।
(६) नोटमा स्टिचको प्रयोग गर्नुहुँदैन । आवश्यकतानुसार रबर/प्लास्टिक/पेपर ब्यान्ड प्रयोग गर्न सकिनेछ । नोटमा नलेख्ने, केरेमेट नगर्ने र बिगार नगर्ने/गराउने व्यवस्था मिलाउनु पर्नेछ ।
(७) भिजेको, मक्किएको, जलेको, गलेको, लुग्गिएको, किराले खाएको, पानीले भिजेको, छुट्टिएको, नोटमा रहेका अक्षर, अंक, चित्र तथा सुरक्षा विशेषताहरु नबुझिने वा बिग्रिने गरी रङ लागेको/लेखिएको/कोरिएको/भेटिएको/च्यातिएको वा अनुचित तस्वीर अंकित भएको नोटलाई पुनः निष्काशन अयोग्य नोटको रुपमा वर्गीकरण गर्नुपर्नेछ र त्यस्ता नोटलाई चलनचल्तीको लागि पठाउनु हुँदैन । चलनचल्तीमा पठाउन अयोग्य नोट आफ्नो खाता रहेको बैंक तथा वित्तीय संस्था वा नोटकोष/नेपाल राष्ट्र बैंकमा पठाउनु पर्नेछ ।
(८) भुक्तानी गर्दा वा सटही सुविधा उपलब्ध गराउँदा माथि उल्लिखित बुँदा नं. २ र ३ बमोजिमका चलनचल्तीमा पठाउन योग्य नोट मात्र प्रयोग गर्नुपर्नेछ । यसरी भुक्तानी वा सटही गर्नुपर्ने नोटलाई निश्चित प्रक्रिया अपनाई जीवाणु तथा भाइरसरहित (Disinfect) गर्नुपर्नेछ ।
(९) नोट राख्ने दराज, फर्निचर, भल्ट, नोट ओसारपसार गर्ने सामग्री सफा राख्नु पर्नेछ । साथै नोट भण्डारण गर्ने ढुकुटी र कारोबार गर्ने कक्षहरुमा यथोचित प्रकाश एवम् Exhaust Fan आदि प्रयोग गरी पर्याप्त हावाको व्यवस्था भएको हुनुपर्नेछ ।
Controlled English translation
(1) Banks and financial institutions shall classify notes received into three categories: fit for circulation through ATMs and other machines; fit for circulation through counter payment; and unfit for circulation.
(2) A green slip shall be used on packages of notes fit for ATM/machine circulation.
(3) A white slip shall be used on packages of notes fit for counter circulation.
(4) A red slip shall be used on packages of notes unfit for circulation.
(5) The slips under items 2–4 shall state the name of the bank/financial institution, office/branch name and stamp, the name and employee ID of the note-counting employee, signature and date.
(6) Notes shall not be stapled. Rubber/plastic/paper bands may be used as necessary. Arrangements shall prevent writing, erasing, marking or damaging notes.
(7) Wet, rotten, burned, decayed, mutilated, insect-damaged, water-damaged, separated, defaced or torn notes, notes whose letters, figures, pictures or security features are unclear, or notes bearing inappropriate pictures shall be classified as unfit for reissue and shall not be circulated. Such notes shall be sent to the account-maintaining bank/financial institution, note chest or Nepal Rastra Bank.
(8) Only notes fit under items 2 and 3 shall be used for payment or exchange, and such notes shall be disinfected through an appropriate process.
(9) Drawers, furniture, vaults and materials used for transport of notes shall be kept clean, and note-storage vaults and transaction rooms shall have adequate lighting and ventilation, including Exhaust Fans where appropriate.
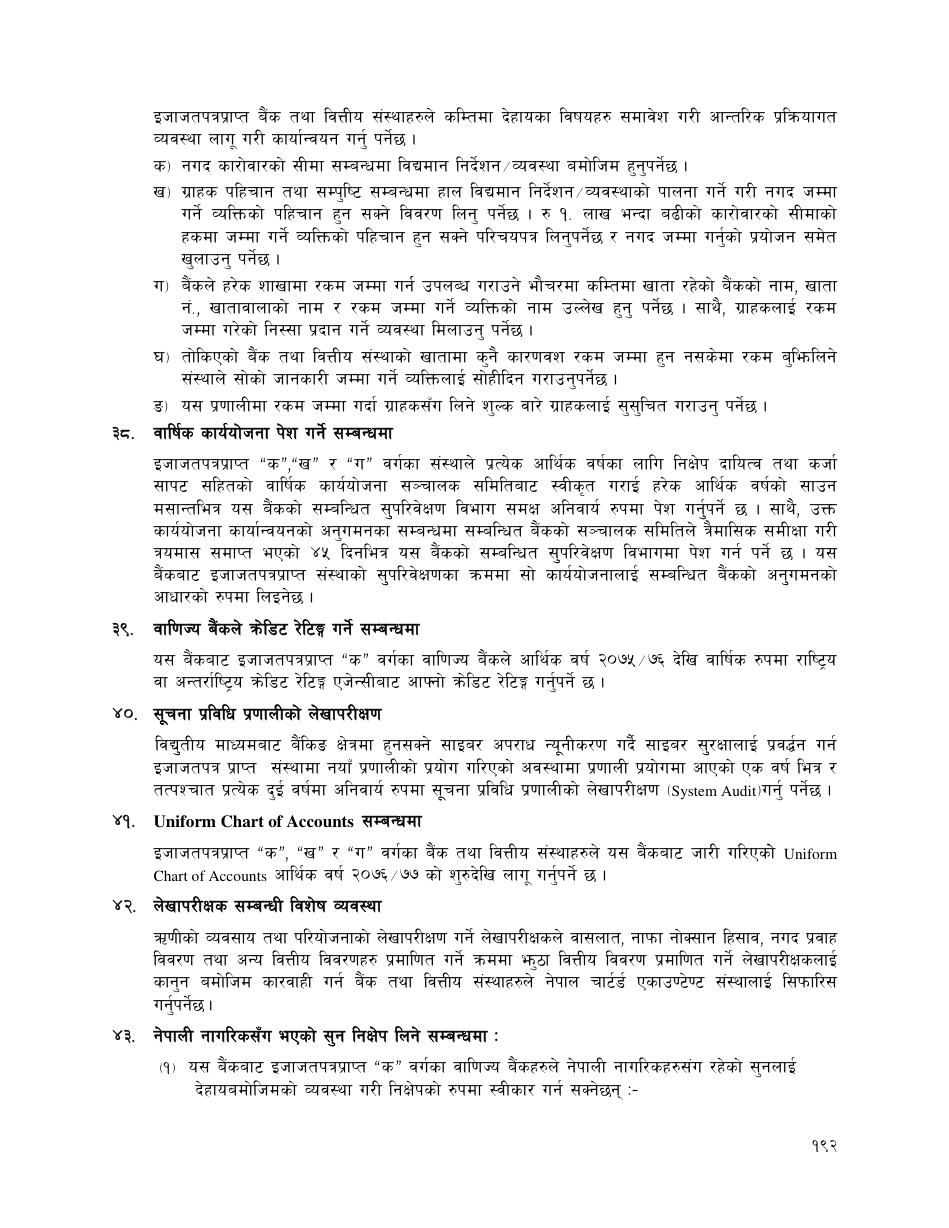
बैंकिङ सेवा तथा कारोबारलाई थप सरल तथा सहज बनाउन ग्राहकलाई पायक पर्ने अन्य बैंक तथा वित्तीय संस्थाका जुनसुकै शाखामा नगद जम्मा गरी आफ्नो बैंक तथा वित्तीय संस्थाको खातामा र सेवा प्रदायक संस्थाको खातामा भुक्तानी (Utility Payment) गर्दा NCHL-IPS प्रणाली मार्फत रकम जम्मा गर्न इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाहरुले कम्तीमा देहायका विषयहरु समावेश गरी आन्तरिक प्रक्रियागत व्यवस्था लागू गरी कार्यान्वयन गर्नु पर्नेछ :
(क) नगद कारोबारको सीमा सम्बन्धमा विद्यमान निर्देशन/व्यवस्था बमोजिम हुने ।
(ख) ग्राहक पहिचान तथा सम्पुष्टि सम्बन्धमा विद्यमान निर्देशन/व्यवस्थाको पालना गरी नगद जम्मा गर्ने व्यक्तिको पहिचान हुन सक्ने परिचयपत्र लिने र नगद जम्माको प्रयोजन खुलाउने ।
(ग) बैंकको हरेक शाखामा रकम जम्मा गर्न उपलब्ध गराउने भौचरमा कम्तीमा खाता रहेको बैंकको नाम, खाता नं., खातावालाको नाम र रकम जम्मा गर्ने व्यक्तिको नाम उल्लेख हुने र ग्राहकलाई रकम जम्मा गरेको निस्सा प्रदान गर्ने व्यवस्था ।
(घ) तोकिएको बैंक तथा वित्तीय संस्थाको खातामा कुनै कारणवश रकम जम्मा हुन नसकेको अवस्थामा सोको जानकारी जम्मा गर्ने व्यक्तिलाई सोही दिन गराउने ।
(ङ) यस प्रणालीमा रकम जम्मा गर्दा ग्राहकसँग लिने शुल्कबारे ग्राहकलाई सुसूचित गराउने ।
Controlled English translation
Licensed banks and financial institutions shall implement internal procedures for cash deposits through NCHL-IPS at any convenient branch of another bank/financial institution for credit to the customer’s own bank/financial-institution account or for Utility Payment to a service-provider account, covering at least:
(a) cash-transaction limits in accordance with prevailing directives;
(b) customer/depositor identification and verification, including an identity document and disclosure of the purpose of the deposit;
(c) a voucher stating at least the account-holding bank, account number, account-holder name and name of the cash depositor, together with a receipt;
(d) same-day notification where the amount cannot for any reason be credited to the designated bank/financial-institution account;
(e) informing customers of fees charged for use of the system.
इजाजतपत्रप्राप्त “क”, “ख” र “ग” वर्गका संस्थाले प्रत्येक आर्थिक वर्षका लागि निक्षेप दायित्व तथा कर्जा सापट सहितको वार्षिक कार्ययोजना सञ्चालक समितिबाट स्वीकृत गराई हरेक आर्थिक वर्षको साउन मसान्तभित्र यस बैंकको सम्बन्धित सुपरिवेक्षण विभाग समक्ष अनिवार्य रुपमा पेश गर्नु पर्नेछ । साथै, उक्त कार्ययोजना कार्यान्वयनको अनुगमनका सम्बन्धमा सम्बन्धित बैंकको सञ्चालक समितिले त्रैमासिक समीक्षा गरी त्रैमास समाप्त भएको ४५ दिनभित्र यस बैंकको सम्बन्धित सुपरिवेक्षण विभागमा पेश गर्नु पर्नेछ । यस बैंकबाट इजाजतपत्रप्राप्त संस्थाको सुपरिवेक्षणका क्रममा सो कार्ययोजनालाई सम्बन्धित बैंकको अनुगमनको आधारको रुपमा लिइनेछ ।
Controlled English translation
Each Class “A”, “B” and “C” institution shall prepare an annual work plan for each fiscal year covering deposit liabilities and loans/advances, obtain approval of the Board of Directors and submit it mandatorily to the concerned Supervision Department by Shrawan-end. The Board shall review implementation quarterly and submit the review within 45 days after quarter-end. The work plan shall serve as a basis of supervisory monitoring by this Bank.
यस बैंकबाट इजाजतपत्रप्राप्त “क” वर्गका वाणिज्य बैंकले आर्थिक वर्ष २०७५/७६ देखि वार्षिक रुपमा राष्ट्रिय वा अन्तर्राष्ट्रिय क्रेडिट रेटिङ एजेन्सीबाट आफ्नो क्रेडिट रेटिङ गराउनु पर्नेछ ।
Controlled English translation
A Class “A” commercial bank licensed by this Bank shall obtain an annual credit rating from a national or international credit-rating agency from FY 2075/76 onward.
विद्युतीय माध्यमबाट बैंकिङ क्षेत्रमा हुनसक्ने साइबर अपराध न्यूनीकरण गर्दै साइबर सुरक्षालाई प्रवर्द्धन गर्न इजाजतपत्रप्राप्त संस्थामा नयाँ प्रणालीको प्रयोग गरिएको अवस्थामा प्रणाली प्रयोगमा आएको एक वर्षभित्र र तत्पश्चात् प्रत्येक दुई वर्षमा अनिवार्य रुपमा सूचना प्रविधि प्रणालीको लेखापरीक्षण (System Audit) गर्नु पर्नेछ ।
Controlled English translation
To reduce cybercrime in banking through electronic channels and promote cybersecurity, where a licensed institution introduces a new system, it shall conduct an Information Technology System Audit within one year after the system comes into use and thereafter mandatorily every two years.
इजाजतपत्रप्राप्त “क”, “ख” र “ग” वर्गका बैंक तथा वित्तीय संस्थाहरुले यस बैंकबाट जारी गरिएको Uniform Chart of Accounts आर्थिक वर्ष २०७६/७७ को शुरूदेखि लागू गर्नु पर्नेछ ।
Controlled English translation
Class “A”, “B” and “C” licensed banks and financial institutions shall implement the Uniform Chart of Accounts issued by this Bank from the beginning of FY 2076/77.
ऋणीको व्यवसाय तथा परियोजनाको लेखापरीक्षण गर्ने लेखापरीक्षकले वासलात, नाफा नोक्सान हिसाब, नगद प्रवाह विवरण तथा अन्य वित्तीय विवरणहरु प्रमाणित गर्ने क्रममा झुट्टा वित्तीय विवरण प्रमाणित गरेमा बैंक तथा वित्तीय संस्थाहरुले त्यस्तो लेखापरीक्षकलाई कानुन बमोजिम कारवाही गर्न नेपाल चार्टर्ड एकाउन्टेन्ट्स संस्थालाई सिफारिस गर्नु पर्नेछ ।
Controlled English translation
Where an auditor auditing a borrower’s business/project certifies false balance sheets, profit-and-loss accounts, cash-flow statements or other financial statements, the bank or financial institution shall refer the auditor to the Institute of Chartered Accountants of Nepal for action in accordance with law.
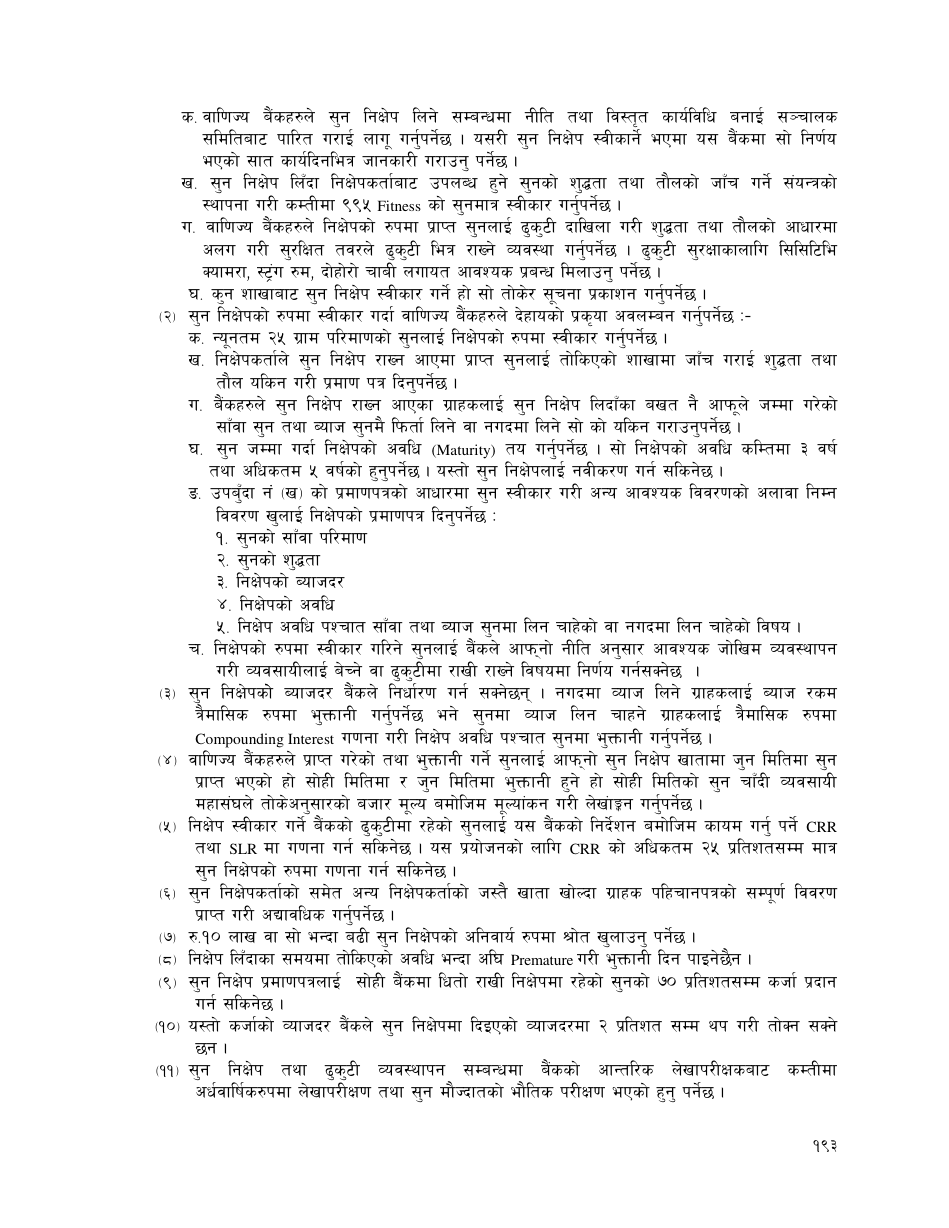
(१) यस बैंकबाट इजाजतपत्रप्राप्त “क” वर्गका वाणिज्य बैंकहरुले नेपाली नागरिकहरुसँग रहेको सुनलाई देहायबमोजिमको व्यवस्था गरी निक्षेपको रुपमा स्वीकार गर्न सक्नेछन् :
(क) सुन निक्षेप लिने सम्बन्धमा नीति तथा विस्तृत कार्यविधि बनाई सञ्चालक समितिबाट पारित गराई लागू गर्नु पर्नेछ र निर्णय भएको सात कार्यदिनभित्र यस बैंकलाई जानकारी गराउनु पर्नेछ ।
(ख) सुनको शुद्धता तथा तौल जाँच गर्ने संयन्त्र स्थापना गरी कम्तीमा ९९५ Fitness को सुन मात्र स्वीकार गर्नु पर्नेछ ।
(ग) प्राप्त सुनलाई ढुकुटी दाखिला गरी शुद्धता तथा तौलको आधारमा अलग गरी सुरक्षित तवरले भल्ट वा अन्य सुरक्षित स्थानमा राख्नु पर्नेछ; camera, strong room, दोहोरो चाबी लगायत आवश्यक सुरक्षा प्रबन्ध मिलाउनु पर्नेछ ।
(घ) कुन शाखाबाट सुन निक्षेप स्वीकार गर्ने हो सो तोकेर सूचना प्रकाशन गर्नु पर्नेछ ।
(२) सुन निक्षेपको रुपमा स्वीकार गर्दा :
(क) न्यूनतम २५ ग्राम सुन स्वीकार गर्नु पर्नेछ ।
(ख) तोकिएको शाखामा जाँच गरी शुद्धता तथा तौल यकिन गरी प्रमाणपत्र दिनु पर्नेछ ।
(ग) सुन वा ब्याज सुनमै फिर्ता लिने वा नगदमा लिने भन्ने विकल्प प्रारम्भमै यकिन गराउनु पर्नेछ ।
(घ) निक्षेप अवधि कम्तीमा ३ वर्ष र अधिकतम ५ वर्षको हुनुपर्नेछ; नवीकरण गर्न सकिनेछ ।
(ङ) प्रमाणपत्रमा सुनको स्रोत/परिमाण, शुद्धता, ब्याजदर, अवधि र साँवा तथा ब्याज सुन वा नगदमा लिने विषय उल्लेख गर्नु पर्नेछ ।
(च) बैंकले आफ्नो नीति अनुसार जोखिम व्यवस्थापन गरी सुन व्यवसायीलाई बेच्न वा ढुकुटीमा राख्न सक्नेछ ।
(३) ब्याजदर बैंकले निर्धारण गर्न सक्नेछ । नगद ब्याज त्रैमासिक भुक्तानी गर्नुपर्नेछ; सुनमा ब्याज लिन चाहनेलाई त्रैमासिक Compounding Interest गणना गरी अवधि पश्चात् सुनमा भुक्तानी गर्नु पर्नेछ ।
(४) प्राप्त तथा भुक्तानी हुने सुनलाई सम्बन्धित मितिको सुन चाँदी व्यवसायी महासंघले तोकेको बजार मूल्यमा मूल्याङ्कन गरी लेखांकन गर्नुपर्नेछ ।
(५) ढुकुटीमा रहेको सुनलाई निर्देशित सीमा भित्र CRR तथा SLR मा गणना गर्न सकिनेछ; CRR प्रयोजनका लागि अधिकतम २५ प्रतिशतसम्म मात्र सुन निक्षेप गणना गर्न सकिनेछ ।
(६) सुन निक्षेपकर्ताको पूर्ण KYC/CDD विवरण प्राप्त गरी अध्यावधिक गर्नुपर्नेछ ।
(७) रु. १० लाख वा सोभन्दा बढी सुन निक्षेपको स्रोत अनिवार्य रुपमा खुलाउनु पर्नेछ ।
(८) अवधि अगावै Premature भुक्तानी दिन पाइने छैन ।
(९) सुन निक्षेप प्रमाणपत्र धितो राखी सुनको मूल्यको ७० प्रतिशतसम्म कर्जा दिन सकिनेछ ।
(१०) यस्तो कर्जाको ब्याजदर सुन निक्षेपमा दिइएको ब्याजदरमा २ प्रतिशतसम्म थप गरी निर्धारण गर्न सकिनेछ ।
(११) सुन निक्षेप तथा ढुकुटी व्यवस्थापन सम्बन्धमा आन्तरिक लेखापरीक्षकबाट कम्तीमा अर्धवार्षिक रुपमा लेखापरीक्षण तथा भौतिक परीक्षण हुनुपर्नेछ ।
(१२) यस बैंकले समय समयमा पूर्व सूचना दिएर वा नदिई निरीक्षण/सुपरिवेक्षण गर्न सक्नेछ ।
(१३) अनुसूची २१.३ तथा २१.४ बमोजिमको विवरण महिना समाप्त भएको ७ दिनभित्र बैंक सुपरिवेक्षण विभागमा पेश गर्नु पर्नेछ ।
Controlled English translation
(1) Class “A” commercial banks may accept gold held by Nepali citizens as deposits subject to:
(a) Board-approved policy and detailed procedures, with information provided to this Bank within seven working days of the decision;
(b) testing mechanisms for purity and weight, accepting only gold of at least 995 fineness;
(c) secure vault/strong-room arrangements, segregation by purity and weight, and necessary controls including cameras and dual keys;
(d) publication of the branches authorised to accept gold deposits.
(2) When accepting gold deposits:
(a) minimum quantity: 25 grams;
(b) testing at the designated branch and issuance of a certificate confirming purity and weight;
(c) the customer shall choose at the outset whether principal/interest will be returned in gold or cash;
(d) the deposit term shall be at least three years and not more than five years, and may be renewed;
(e) the certificate shall state source/quantity, purity, interest rate, term and whether principal/interest will be received in gold or cash;
(f) the bank may, subject to its policy and risk management, sell accepted gold to dealers or keep it in the vault.
(3) The bank may determine the interest rate. Cash interest shall be paid quarterly; where interest is to be received in gold, Compounding Interest shall be calculated quarterly and paid in gold after maturity.
(4) Gold received and payable shall be accounted for at the market value prescribed by the relevant bullion federation on the respective date.
(5) Gold in the vault may be counted toward CRR and SLR within limits prescribed by this Bank; for CRR, gold deposits may be counted up to a maximum of 25 percent.
(6) Full KYC/CDD information shall be obtained and updated.
(7) The source of gold deposits of NPR 1 million or more shall be mandatorily disclosed.
(8) Premature repayment shall not be permitted.
(9) Credit up to 70 percent of the gold value may be granted against the gold-deposit certificate.
(10) The lending rate may be fixed at up to 2 percentage points above the interest rate paid on the gold deposit.
(11) Gold deposits and vault management shall be audited by the internal auditor at least half-yearly, including physical verification.
(12) This Bank may inspect/supervise the activity with or without prior notice.
(13) Statements under Schedules 21.3 and 21.4 shall be submitted to the Bank Supervision Department within seven days after month-end.
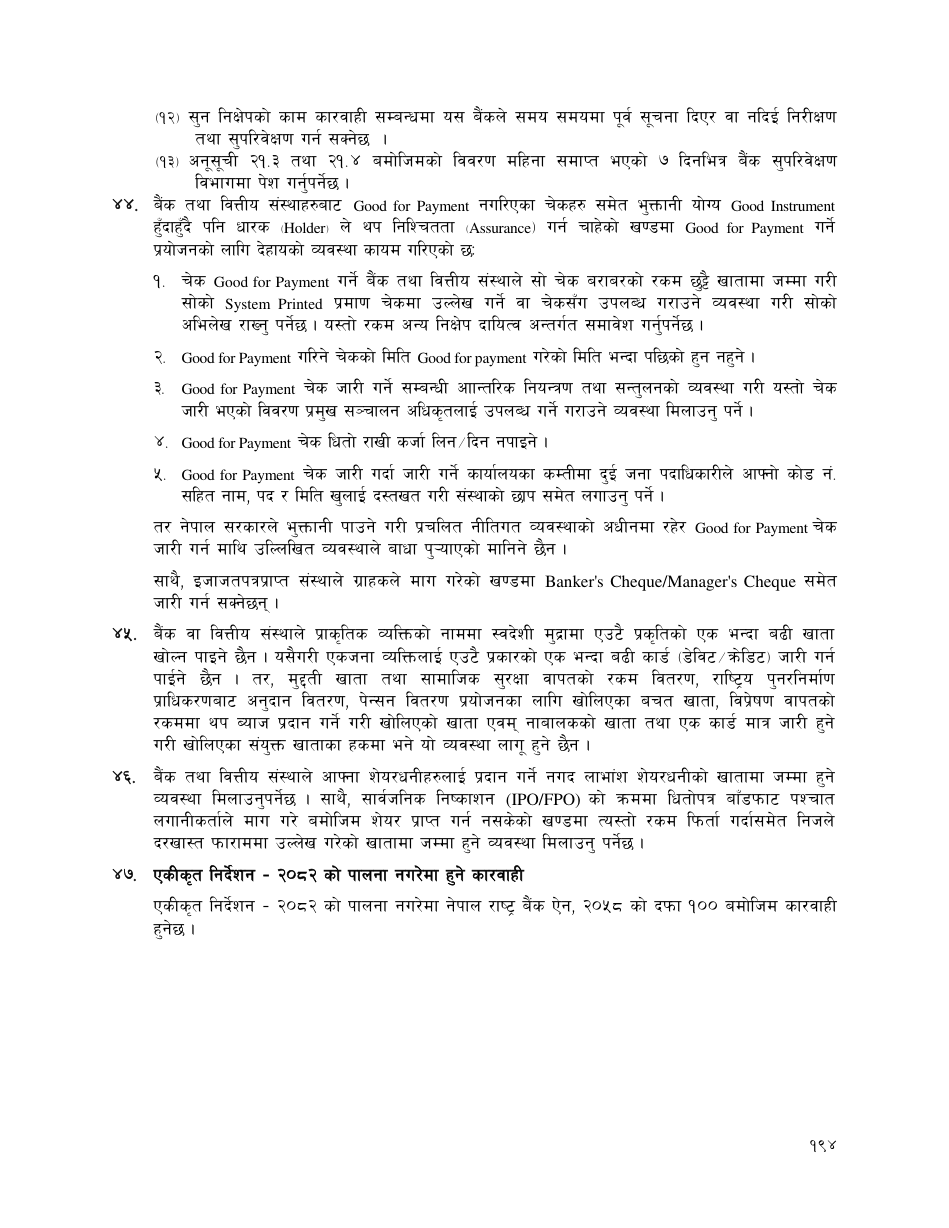
बैंक तथा वित्तीय संस्थाहरुबाट Good for Payment नगरिएका चेकहरु समेत भुक्तानी योग्य Good Instrument हुँदैगर्दा पनि धारक (Holder) ले थप निश्चितता (Assurance) गर्न चाहेको खण्डमा Good for Payment गर्न प्रयोगको लागि देहायका व्यवस्था कायम गरिएको छ :
१. चेक Good for Payment गर्ने बैंक तथा वित्तीय संस्थाले सो चेक बराबरको रकम छुट्टै खातामा जम्मा गरी सोको System Printed प्रमाण चेकमा उल्लेख गर्ने वा चेकसँग उपलब्ध गराउने व्यवस्था गरी सोको अभिलेख राख्नु पर्नेछ । यस्तो रकम अन्य निक्षेप दायित्व अन्तर्गत समावेश गर्नु पर्नेछ ।
२. Good for Payment गरिने चेकको मिति Good for Payment गरेको मिति भन्दा पछिको हुन नहुने ।
३. Good for Payment चेक जारी गर्ने सम्बन्धी आन्तरिक नियन्त्रण तथा सन्तुलनको व्यवस्था गरी यस्तो चेक जारी भएको विवरण प्रमुख सञ्चालन अधिकृतलाई उपलब्ध गराई गराउने व्यवस्था मिलाउनु पर्ने ।
४. Good for Payment चेक धितो राखी कर्जा लिन/दिन नपाइने ।
५. Good for Payment चेक जारी गर्दा जारी गर्ने कार्यालयका कम्तीमा दुई जना पदाधिकारीले आफ्नो कोड नं. सहित नाम, पद र मिति खुलाई दस्तखत गरी संस्थाको छाप समेत लगाउनु पर्ने ।
तर नेपाल सरकारले भुक्तानी पाउने गरी प्रचलित नीतिगत व्यवस्थाको अधीनमा रहेर Good for Payment चेक जारी गर्न माथि उल्लिखित व्यवस्थाले बाधा पुर्याएको मानिने छैन ।
साथै, इजाजतपत्रप्राप्त संस्थाले ग्राहकले माग गरेको खण्डमा Banker’s Cheque/Manager’s Cheque समेत जारी गर्न सक्नेछन् ।
Controlled English translation
Where the holder seeks additional assurance even though an unmarked cheque is otherwise a valid payable instrument, a Good for Payment cheque shall comply with:
1. the bank/financial institution shall place an amount equal to the cheque in a separate account, provide System Printed evidence on or with the cheque and maintain records; the amount shall be included under other deposit liabilities;
2. the cheque date shall not be later than the date on which it is marked Good for Payment;
3. internal-control and balancing arrangements shall be maintained and issuance details made available to the Chief Operating Officer;
4. no credit shall be taken or granted against a Good for Payment cheque;
5. at least two officers of the issuing office shall sign, stating code number, name, designation and date, and affix the institution’s seal.
These requirements do not prevent issuance of a Good for Payment cheque payable to the Government of Nepal under prevailing policy. A licensed institution may also issue a Banker’s Cheque/Manager’s Cheque at a customer’s request.
बैंक वा वित्तीय संस्थाले प्राकृतिक व्यक्तिको नाममा स्वदेशी मुद्रामा एउटै प्रकृतिको एक भन्दा बढी खाता खोल्न पाउने छैन । यसैगरी एकजना व्यक्तिलाई एउटै प्रकारको एक भन्दा बढी कार्ड (डेबिट/क्रेडिट) जारी गर्न पाइने छैन ।
तर, मुद्दती खाता तथा सामाजिक सुरक्षा वापतको रकम वितरण, राष्ट्रिय पुनर्निर्माण प्राधिकरणको अनुदान वितरण, पेन्सन वितरण प्रयोजनका खाता र व्यक्तिको नाममा तोकिएको विशेष प्रयोजनको खाता, नाबालकको खाता तथा एक कार्ड मात्र जारी हुने गरी खोलिएका संयुक्त खाताको हकमा यो व्यवस्था लागू हुने छैन ।
Controlled English translation
A bank or financial institution shall not open more than one domestic-currency account of the same nature in the name of a natural person, nor issue more than one card of the same type (debit/credit) to one person.
The restriction does not apply to fixed deposits, accounts for distribution of social-security payments, National Reconstruction Authority grants or pensions, specified special-purpose accounts, accounts of minors, or joint accounts structured so that only one card is issued.
बैंक तथा वित्तीय संस्थाले आफ्ना शेयरधनीहरुलाई प्रदान गर्ने नगद लाभांश शेयरधनीको खातामा जम्मा हुने व्यवस्था मिलाउनु पर्नेछ । साथै, सार्वजनिक निष्काशन (IPO/FPO) को क्रममा लगानीकर्ताले माग गरे बमोजिम शेयर प्राप्त गर्न नसकेको खण्डमा त्यस्तो रकम फिर्ता गर्दाखेरि निजको दरखास्त फाराममा उल्लेख गरेको खातामा जम्मा हुने व्यवस्था मिलाउनु पर्नेछ ।
Controlled English translation
A bank or financial institution shall arrange for cash dividends payable to shareholders to be credited to the shareholder’s account. Where an investor does not receive the shares applied for in an IPO/FPO, the refundable amount shall be credited to the account stated in the application form.
Structured schedules and forms are presented in the supplied order without altering their content.
Source Mode: exact-source-image-pages
Source Images
image185.png
image186.png
image187.png
image188.png
image189.png
image190.png
image191.png
image192.png
image193.png
image194.png
image195.png
Language: English — official source template
Cover Fields
Institution name
Year ended Ashad / corresponding July
Auditor / Audit Firm
Outline
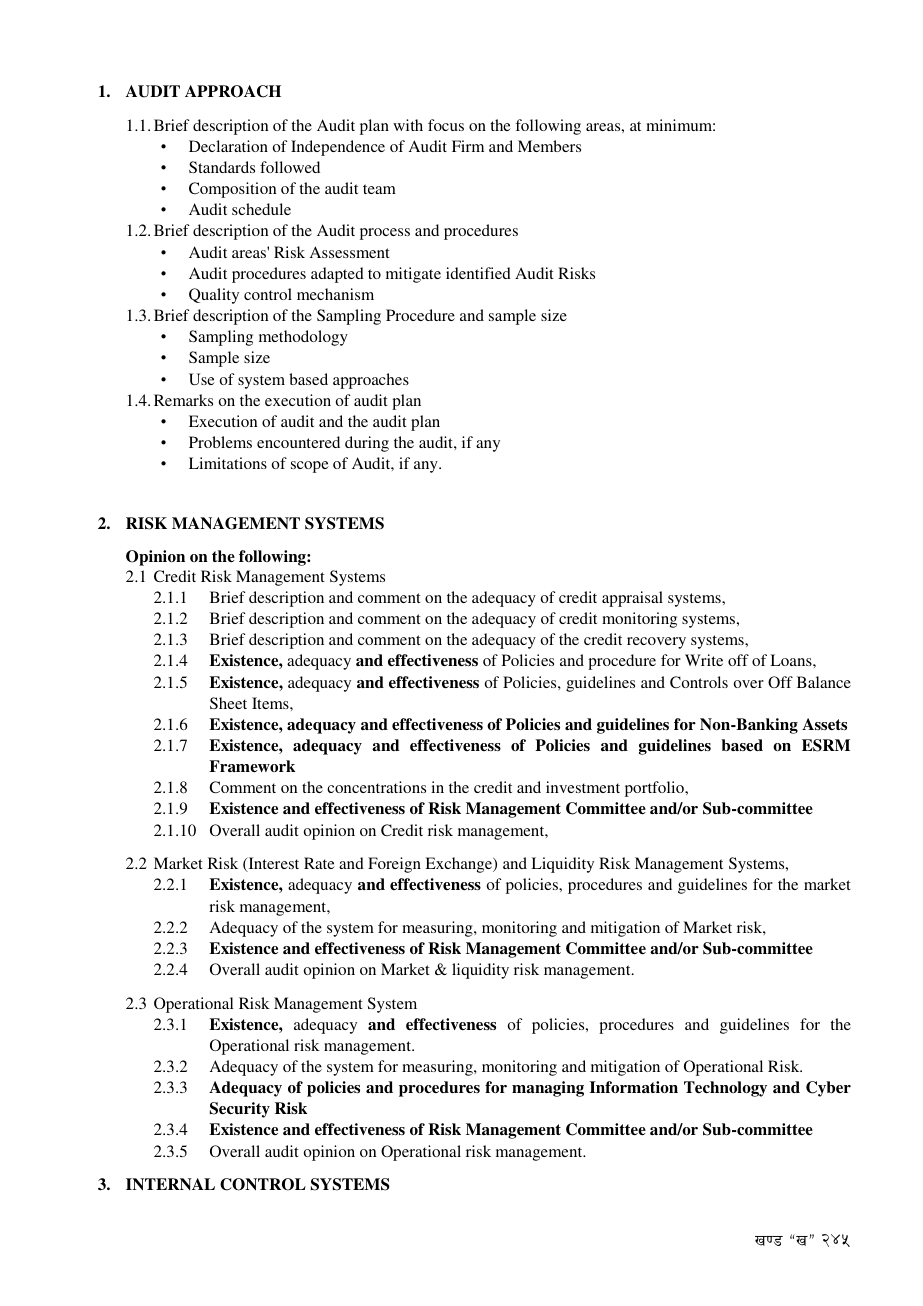
1. AUDIT APPROACH
2. RISK MANAGEMENT SYSTEMS
3. INTERNAL CONTROL SYSTEMS
Corporate Governance / Board and Management
Capital Adequacy and Capital Management
Asset Quality / Credit Portfolio and Loan Classification
Earnings / Profitability
Liquidity and Market Risk
Information Technology / Cyber Security
AML/CFT and Compliance
Other regulatory observations and auditor certification
Publication Rule: These pages are already an official English audit-report template. Preserve/render the source pages without rewording. The outline is navigational only.
Original Nepali text is authoritative. English is a controlled facilitative translation and is not an official Nepal Rastra Bank translation.
In case of inconsistency, ambiguity or difference, the official Nepali Directive and applicable Nepal Rastra Bank circulars prevail.
C.M. & Associates is not affiliated with, approved by or endorsed by Nepal Rastra Bank. This material is provided for information and reference only and does not constitute legal, regulatory, tax or professional advice.
Technical controls cannot guarantee prevention of screenshots or copying.