Directive 15ब्याजदर सम्बन्धी व्यवस्थाProvisions Relating to Interest Rates
Original/reproduced Nepali source controls; English is a controlled facilitative translation.
Applicability Class A licensed institutions; Class B licensed institutions; Class C licensed institutions
Classification PASS WITH EXPLICIT SOURCE GAP
Updated-through statement Circular No. 1 (A/B/C), FY 2083/84 dated 27 Aug 2026: Schedule 15.1 amendment recorded; exact wording not reproduced.
Rendering basis Render web-normalized sections and canonical supplemental objects exactly. Canonical reviewed JSON is authoritative for web/PDF. Do not OCR or rewrite legal text.
नेपाली मूल पाठ
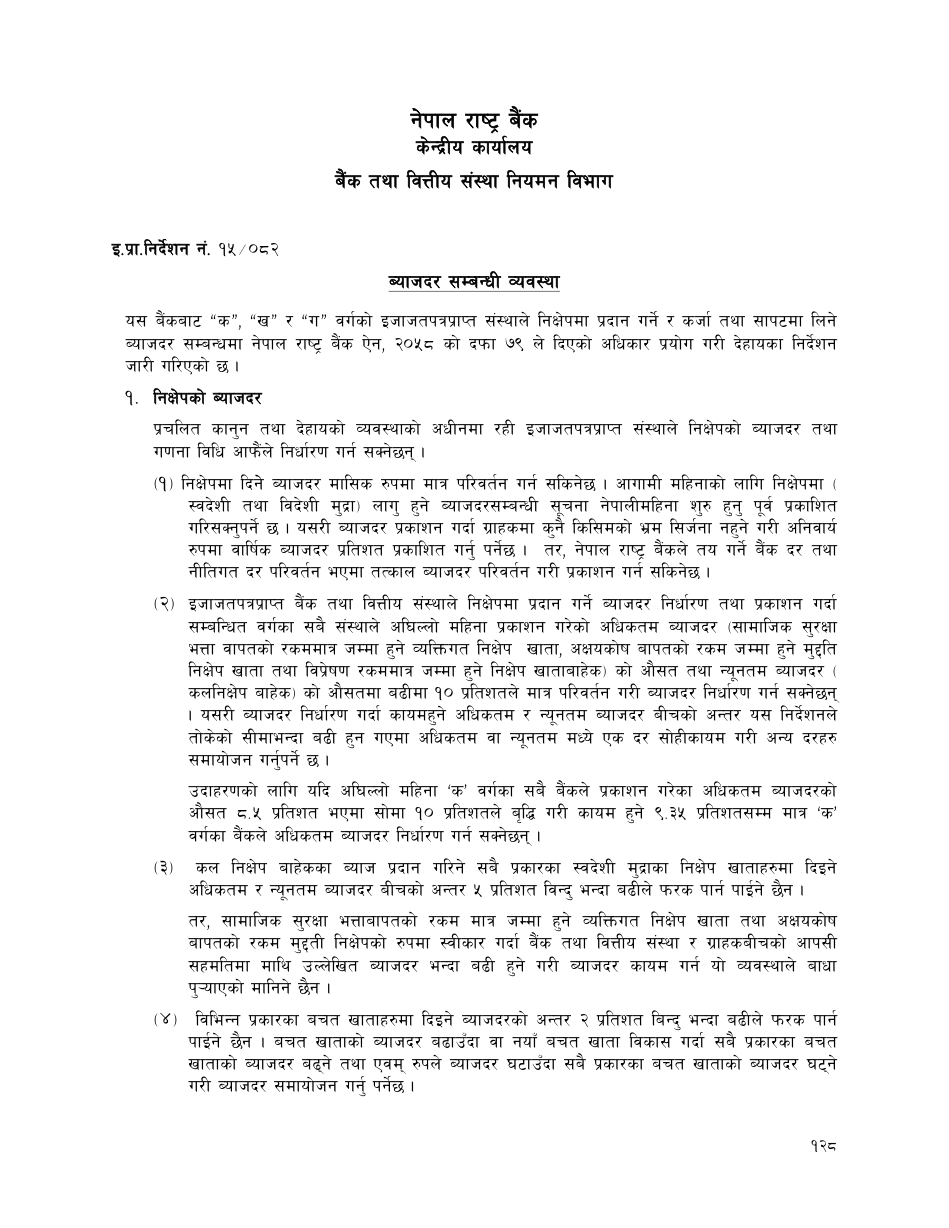
यस बैंकबाट “क”, “ख” र “ग” वर्गको इजाजतपत्रप्राप्त संस्थाले निक्षेपमा प्रदान गर्ने र कर्जा तथा सापटमा लिने ब्याजदर सम्बन्धमा नेपाल राष्ट्र बैंक ऐन, २०५८ को दफा ७९ ले दिएको अधिकार प्रयोग गरी देहायका निर्देशन जारी गरिएको छ ।
Controlled English translation
In exercise of the authority conferred by Section 79 of the Nepal Rastra Bank Act, 2058, the following directives are issued in relation to interest paid on deposits and interest charged on loans and advances by Class “A”, “B” and “C” licensed institutions.
प्रचलित कानुन तथा देहायको व्यवस्थाको अधीनमा रही इजाजतपत्रप्राप्त संस्थाले निक्षेपको ब्याजदर तथा गणना विधि आफैले निर्धारण गर्न सक्नेछन् ।
(१) निक्षेपमा दिने ब्याजदर मासिक रूपमा मात्र परिवर्तन गर्न सकिनेछ । आगामी महिनाको लागि निक्षेपमा (स्वदेशी तथा विदेशी मुद्रा) लागू हुने ब्याजदरसम्बन्धी सूचना नेपाली महिना शुरू हुनु पूर्व प्रकाशन गरिसक्नुपर्नेछ । यसरी ब्याजदर प्रकाशन गर्दा ग्राहकमा कुनै किसिमको भ्रम सिर्जना नहुने गरी अनिवार्य रूपमा वार्षिक ब्याजदर प्रतिशत प्रकाशित गर्नु पर्नेछ । तर, नेपाल राष्ट्र बैंकले तय गर्ने बैंक दर तथा नीतिगत दर परिवर्तन भएमा तत्काल ब्याजदर परिवर्तन गरी प्रकाशन गर्न सकिनेछ ।
(२) इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाले निक्षेपमा प्रदान गर्ने ब्याजदर निर्धारण तथा प्रकाशन गर्दा सम्बन्धित वर्गका सबै संस्थाले अघिल्लो महिना प्रकाशन गरेको अधिकतम ब्याजदर (सामाजिक सुरक्षा भत्ता वापतको रकममात्र जम्मा हुने व्यक्तिगत निक्षेप खाता, अक्षयकोष वापतको रकम जम्मा हुने मुद्दती निक्षेप खाता तथा विप्रेषण रकममात्र जम्मा हुने निक्षेप खाताबाहेक) को औसत तथा न्यूनतम ब्याजदर (कल निक्षेप बाहेक) को औसतमा बढीमा १० प्रतिशतले मात्र परिवर्तन गरी ब्याजदर निर्धारण गर्न सक्नेछन् । यसरी ब्याजदर निर्धारण गर्दा कायम हुने अधिकतम र न्यूनतम ब्याजदर बीचको अन्तर यस निर्देशनले तोकेको सीमाभन्दा बढी हुन गएमा अधिकतम वा न्यूनतम मध्ये एक दर सोही कायम गरी अन्य दरहरु समायोजन गर्नुपर्नेछ ।
उदाहरणको लागि यदि अघिल्लो महिना “क” वर्गका सबै बैंकले प्रकाशन गरेको अधिकतम ब्याजदरको औसत ८.५ प्रतिशत भएमा सोमा १० प्रतिशतले वृद्धि गरी कायम हुने ९.३५ प्रतिशतसम्म मात्र “क” वर्गको बैंकले अधिकतम ब्याजदर निर्धारण गर्न सक्नेछन् ।
(३) कल निक्षेप बाहेकका ब्याज प्रदान गरिने सबै प्रकारका स्वदेशी मुद्रा निक्षेप खाताहरुमा दिइने अधिकतम र न्यूनतम ब्याजदर बीचको अन्तर ५ प्रतिशत बिन्दु भन्दा बढीले फरक पार्न पाइने छैन ।
तर, सामाजिक सुरक्षा भत्तावापतको रकम मात्र जम्मा हुने व्यक्तिगत निक्षेप खाता तथा अक्षयकोष वापतको रकम मुद्दती निक्षेपको रुपमा स्वीकार गर्दा बैंक तथा वित्तीय संस्था र ग्राहकबीचको आपसी सहमतिमा माथि उल्लिखित ब्याजदर भन्दा बढी हुने गरी ब्याजदर कायम गर्न यो व्यवस्थाले बाधा पुर्याएको मानिने छैन ।
(४) विभिन्न प्रकारका बचत खाताहरुमा दिइने ब्याजदरको अन्तर २ प्रतिशत बिन्दु भन्दा बढीले फरक पार्न पाइने छैन । बचत खाताको ब्याजदर बढाउँदा वा नयाँ बचत खाता विकास गर्दा सबै प्रकारका बचत खाताको ब्याजदर बढ्ने तथा एवम् रुपले ब्याजदर घटाउँदा सबै प्रकारका बचत खाताको ब्याजदर घट्ने गरी ब्याजदर समायोजन गर्नु पर्नेछ ।
(५) वैदेशिक रोजगारीमा रहेका नेपालीको बैंकिङ प्रणालीबाट प्राप्त हुने विप्रेषण रकम बैंक तथा वित्तीय संस्थाहरुमा खोलिएको वा खोलिने विप्रेषण (रेमिट्यान्स) बचत खातामा निक्षेप राखेमा, सो खाताबाट रकमान्तर गरी खोलिएको मुद्दती खातामा तथा वैदेशिक रोजगारीमा रहेका नेपालीले परिवारको नाममा पठाएको विप्रेषण रकम निक्षेपको परिचय/सबुत लिएमा कम्तीमा १ प्रतिशत बिन्दुले थप गरी ब्याजदर प्रदान गर्नु पर्नेछ । यस्तो निक्षेपको ब्याजदर उपबुँदा ४ र उपबुँदा ५ मा उल्लिखित ब्याजदर बीचको अन्तर गणना गर्दा छुट प्रदान गरिएको छ ।
(६) माग तथा अन्य सूचनामा आधारित निक्षेप (Call Deposit) मा बचत निक्षेपमा प्रदान गरिने न्यूनतम ब्याजदरको पचास प्रतिशत भन्दा बढी ब्याज प्रदान गर्न पाइने छैन । यस्तो खाताहरुमा चेक जारी गर्न पाइने छैन ।
(७) ३ महिना भन्दा कम समयावधिको व्यक्तिगत मुद्दती निक्षेप तथा ६ महिना भन्दा कम समयावधिको संस्थागत मुद्दती निक्षेप स्वीकार गर्न पाइने छैन । साथै, मुद्दती निक्षेपको समयावधि समाप्त नहुँदै पूर्वनिर्धारित ब्याजदर कायम रहने गरी ग्राहकले चाहेको बखत रकम झिक्न मिल्ने प्रकृतिको मुद्दती निक्षेप स्वीकार गर्न पाइने छैन । संस्थागत मुद्दती निक्षेपको हकमा ६ महिना व्यतीत हुन अगावै कुनै पनि रकम भुक्तानी/फिर्ता (Pre mature) गर्न पाइने छैन ।
(८) ब्याज प्रदान गरिने खाता कुनै पनि कारणले निष्क्रिय हुन गएमा समेत निक्षेपकर्ताले पाउनुपर्ने ब्याज प्रदान गर्नुपर्नेछ ।
Controlled English translation
Subject to prevailing law and the following provisions, a licensed institution may itself determine the interest rate on deposits and the method of calculation.
(1) The interest rate payable on deposits may be changed only monthly. Notice of the interest rates applicable to deposits (domestic and foreign currency) for the coming month shall be published before the commencement of the Nepali month. When publishing the interest rate, the annual interest-rate percentage shall mandatorily be published in a manner that does not create any confusion for customers. However, if the Bank Rate or policy rate determined by Nepal Rastra Bank changes, the interest rate may be changed and published immediately.
(2) When determining and publishing deposit interest rates, a licensed bank or financial institution may determine the interest rate by changing by not more than 10 percent the average maximum interest rate published in the previous month by all institutions of the relevant class (excluding individual deposit accounts in which only social-security allowance is deposited, fixed deposit accounts in which endowment-fund amounts are deposited, and deposit accounts in which only remittance amounts are deposited) and the average minimum interest rate (excluding call deposits). If, in determining the interest rate in this manner, the difference between the resulting maximum and minimum rates exceeds the limit prescribed by this Directive, either the maximum or minimum rate shall be maintained unchanged and the other rates shall be adjusted.
For example, if the average maximum interest rate published in the previous month by all Class “A” banks is 8.5 percent, a Class “A” bank may determine its maximum interest rate only up to 9.35 percent, being the rate obtained by increasing that average by 10 percent.
(3) For all types of domestic-currency deposit accounts bearing interest other than call deposits, the difference between the maximum and minimum interest rates shall not exceed 5 percentage points.
However, where only social-security allowance is deposited in an individual deposit account, or where an endowment-fund amount is accepted as a fixed deposit, nothing in this provision shall prevent a bank or financial institution and the customer from mutually agreeing to an interest rate higher than the above rate.
(4) The difference among interest rates provided on different types of savings accounts shall not exceed 2 percentage points. When increasing the interest rate on savings accounts or developing a new savings account, interest rates on all types of savings accounts shall increase correspondingly; similarly, when reducing interest rates, the rates on all types of savings accounts shall be adjusted downward.
(5) Where remittance received through the banking system from a Nepali in foreign employment is deposited in a remittance savings account opened or to be opened with a bank or financial institution, in a fixed account opened by transferring funds from such account, or where remittance sent by a Nepali in foreign employment in the name of a family member is deposited upon obtaining identification/evidence of the remittance, an additional interest rate of at least 1 percentage point shall be provided. Such deposits are exempt when calculating the interest-rate difference referred to in sub-clauses 4 and 5.
(6) On demand and other notice-based deposits (Call Deposit), interest exceeding fifty percent of the minimum interest rate provided on savings deposits shall not be paid. Cheques shall not be issued on such accounts.
(7) Individual fixed deposits with a term of less than three months and institutional fixed deposits with a term of less than six months shall not be accepted. A fixed deposit shall not be accepted on terms that allow the customer to withdraw funds before expiry of the fixed-deposit period while retaining the predetermined interest rate. In the case of an institutional fixed deposit, no amount shall be paid/refunded (Pre mature) before six months have elapsed.
(8) Even where an interest-bearing account becomes inactive for any reason, the interest due to the depositor shall be provided.
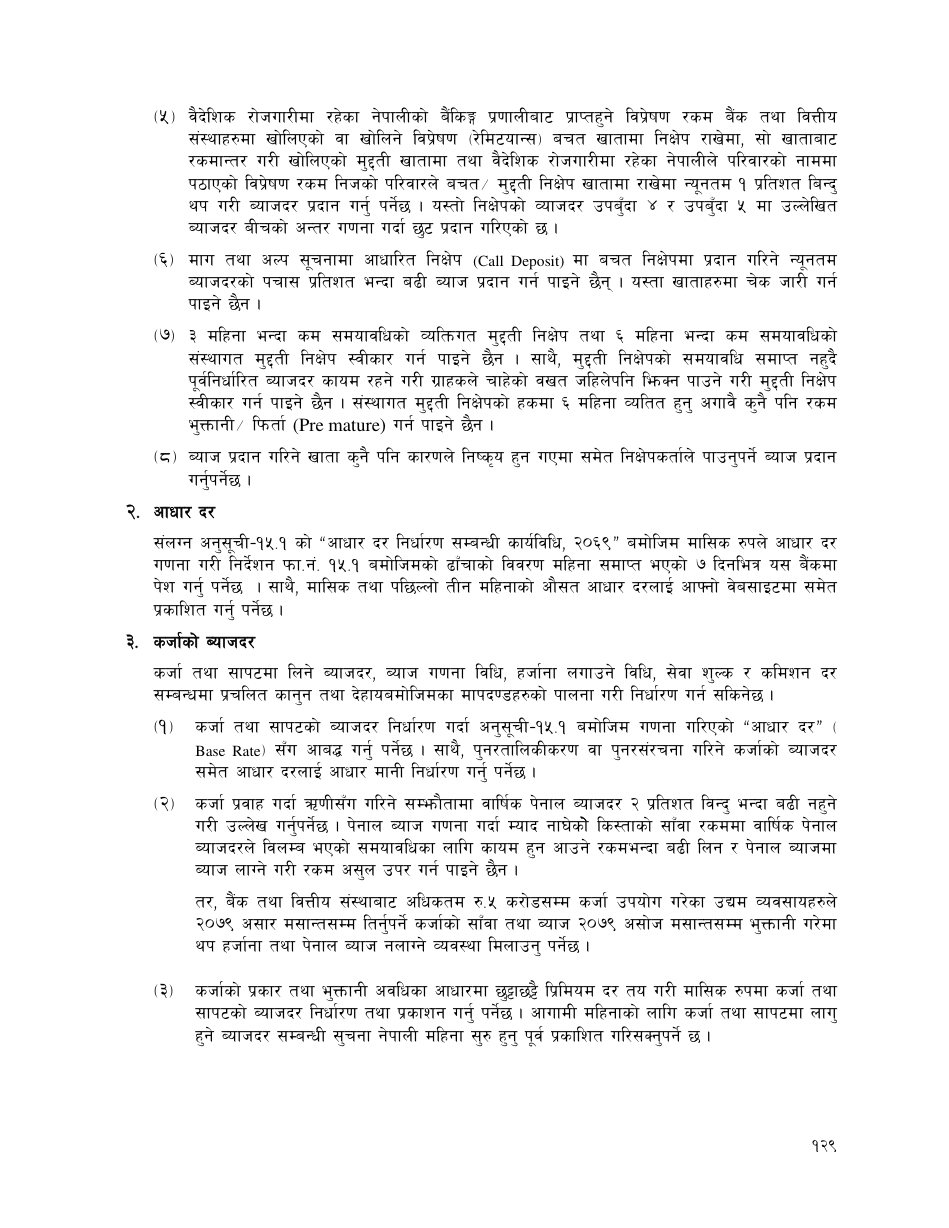
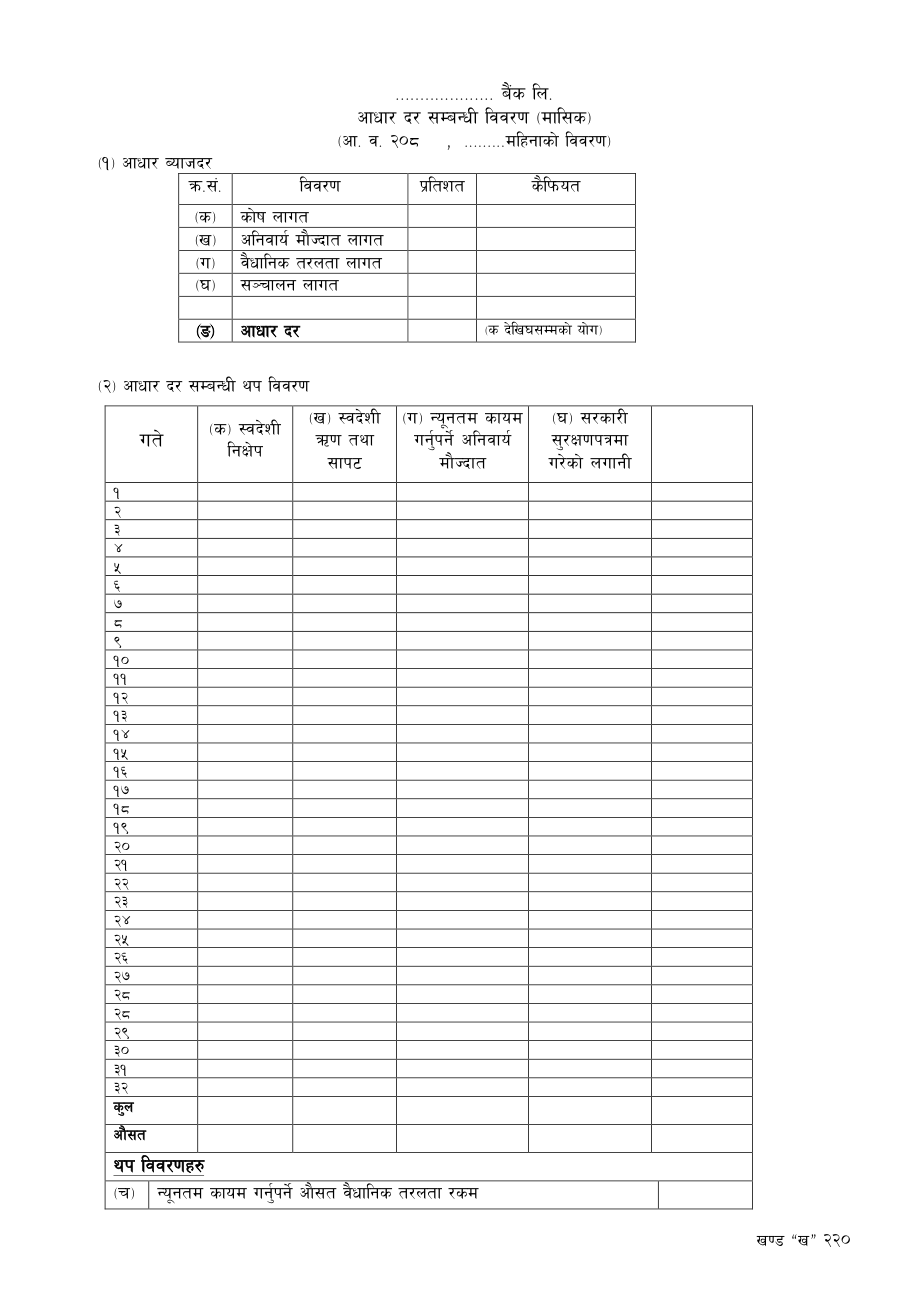
संलग्न अनुसूची-१५.१ को “आधार दर निर्धारण सम्बन्धी कार्यविधि, २०६९” बमोजिम मासिक रूपमा आधार दर गणना गरी निर्देशन फा.नं. १५.१ बमोजिमको ढाँचाको विवरण मासिक रूपमा प्रत्येक महिना यस बैंकमा पेश गर्नु पर्नेछ । साथै, मासिक तथा पछिल्लो तीन महिनाको औसत आधार दरलाई आफ्नो वेबसाइटमा समेत प्रकाशित गर्नु पर्नेछ ।
Controlled English translation
The Base Rate shall be calculated monthly in accordance with the attached Schedule 15.1, “Procedure Relating to Determination of Base Rate, 2069”, and a monthly statement in the format of Directive Form No. 15.1 shall be submitted to this Bank every month. The monthly Base Rate and the average Base Rate for the latest three months shall also be published on the institution’s website.
कर्जा तथा सापटमा लिने ब्याजदर, ब्याज गणना विधि, हर्जाना लगाउने विधि, सेवा शुल्क र कमिशन दर सम्बन्धमा प्रचलित कानुन तथा देहायबमोजिमका मापदण्डहरुको पालना गरी निर्धारण गर्न सकिनेछ ।
(१) कर्जा तथा सापटको ब्याजदर निर्धारण गर्दा अनुसूची-१५.१ बमोजिम गणना गरिएको “आधार दर” (Base Rate) सँग आबद्ध गर्नु पर्नेछ । साथै, पुनर्तालिकीकरण वा पुनर्संरचना गरिने कर्जाको ब्याजदर समेत आधार दरलाई आधार मानी निर्धारण गर्नु पर्नेछ ।
(२) कर्जा प्रवाह गर्दा ऋणीसँग गरिने सम्झौतामा ऋणीसँग गरिने सम्झौतामा वार्षिक पेनाल ब्याजदर २ प्रतिशत बिन्दु भन्दा बढी नहुने गरी उल्लेख गर्नुपर्नेछ । पेनाल ब्याज लाग्ने समयावधिका लागि रकम तिर्नुपर्ने मितिले नतिरेको बाँकी रकममा वार्षिक पेनाल ब्याजदरले विलम्ब भएको समयावधिका लागि कायम हुन आउने रकमभन्दा बढी लिन र पेनाल ब्याजमा ब्याज लगाउने गरी रकम असुल उपर गर्न पाइने छैन ।
तर, बैंक तथा वित्तीय संस्थाबाट अधिकतम रु. ५.५ करोडसम्म कर्जा उपयोग गरेका उद्यम व्यवसायहरुले २०८० असार मसान्तसम्म तिर्नुपर्ने कर्जाको साँवा तथा ब्याज २०८० असोज मसान्तसम्म भुक्तानी गरेमा थप हर्जाना तथा पेनाल ब्याज नलगाउने व्यवस्था मिलाउनु पर्नेछ ।
(३) कर्जाको प्रकार तथा भुक्तानी अवधिका आधारमा छुट्टाछुट्टै प्रिमियम दर तय गरी मासिक रूपमा कर्जा तथा सापटको ब्याजदर निर्धारण तथा प्रकाशन गर्नु पर्नेछ । आगामी महिनाको लागि कर्जा तथा सापटमा लागू हुने ब्याजदर सम्बन्धी सूचना नेपाली महिना शुरू हुनु पूर्व प्रकाशन गरिसक्नु पर्नेछ ।
(४) ब्याजदर प्रकाशन गर्दा कर्जा शीर्षक अनुसार आधार दरमा थप गरिने प्रिमियम दर स्पष्ट रूपमा उल्लेख गर्नु पर्नेछ । प्रकाशित प्रिमियम दर वृद्धि गर्दा अर्धवार्षिक रूपमा गर्न सकिनेछ । तर, प्रिमियम दर घटाउनु पर्ने भएमा अर्धवार्षिक भन्दा कम समयावधिमा पनि प्रकाशित प्रिमियम दर घटाउन सकिनेछ ।
(५) कुनै व्यक्ति वा फर्मलाई प्रदान गरिने कर्जा तथा सापटको ब्याजदर निर्धारण गर्दा आधार दरमा थप गरिने प्रिमियम दर स्पष्ट रूपमा उल्लेख गर्नुपर्नेछ । उदाहरणका लागि कुनै ग्राहकलाई प्रदान गरिने कर्जाको ब्याजदर निर्धारण गर्दा आधार दरमा २ प्रतिशत बिन्दुले प्रिमियम थप गर्ने भएमा निम्नानुसार ब्याजदर तय गर्नु पर्नेछ:
कर्जाको ब्याजदर = आधार दर + २ प्रतिशत बिन्दु
(६) कुनैपनि कर्जा पछिल्लो तीन महिनाको औसत आधारदर भन्दा कम ब्याजदरमा प्रवाह गर्न पाइने छैन । तर, नेपाल सरकार/प्रदेश सरकार/स्थानीय तहले आफ्नो कार्यक्रम अन्तर्गतको कर्जाको लागि निश्चित दरमा सहुलियत दरको सहायता/अनुदान रकमलाई बैंक तथा वित्तीय संस्थामार्फत तोकिएको क्षेत्र एवं वर्गमा ऋण परिचालन हुने गरी सञ्चालन गरेको कार्यक्रम अन्तर्गतको कर्जा औसत आधारदर भन्दा कम ब्याजदरमा प्रवाह गर्न यस व्यवस्थाले बाधा पुर्याएको मानिने छैन ।
(७) कर्जा तथा सापटको ब्याजदर निर्धारण गर्दा एउटै प्रकृतिका कर्जा तथा सापटको ब्याजदर अन्तर २ प्रतिशत बिन्दुभन्दा बढीले फरक पार्न पाइने छैन ।
(८) बैंक तथा वित्तीय संस्थाहरुले प्रदान गर्ने सम्पूर्ण आवधिक प्रकृतिका कर्जाको परिवर्तनशील ब्याजदर (Adjustable Interest Rate) को साथै स्थिर ब्याजदर (Fixed Interest Rate) समेत प्रकाशन गर्नुपर्नेछ ।
(९) ऋणीलाई दिने कर्जा प्रस्ताव पत्र (Offer Letter) मा आधार दरमा थप गरिने प्रिमियम दर स्पष्ट रूपमा उल्लेख गर्नु पर्नेछ । प्रिमियम दर तय गर्दा कर्जाको लागि आवेदन प्राप्त हुँदाको बखत प्रकाशित प्रिमियम दर भन्दा बढी तय गर्न पाइने छैन ।
(१०) एकपटक प्रिमियम दर निर्धारण गरी ऋणीलाई दिने कर्जा प्रस्तावपत्रमा उल्लेख गरी कर्जा स्वीकृत गरे पश्चात् प्रिमियम दर वृद्धि गर्न वा कुनै किसिमको डिस्काउन्ट प्रदान गरी पुनः स्वतः वृद्धि हुने जस्ता योजना लागू गर्न पाइने छैन । तर, ऋणीले जुन उद्देश्यका लागि कर्जा लिएको हो सो उद्देश्यमा कर्जा प्रयोग नगरेको र बिनै सम्झौतामा सो सम्बन्धी व्यवस्था कर्जा सम्झौतामा उल्लेख भएको अवस्थामा कर्जा दुरुपयोगको हर्जाना दर थप गर्न यो व्यवस्थाले बाधा पुर्याएको मानिने छैन ।
(११) ऋणीको कर्जा सीमा थप गर्दा वा बैंक तथा वित्तीय संस्थाले प्रवाह गर्ने नयाँ कर्जाको हकमा नयाँ प्रकाशित प्रिमियम दर लागू हुनेछ ।
(१२) इजाजतपत्रप्राप्त संस्थाले कर्जा तथा सापटको ब्याजदर निर्धारण गर्ने क्रममा आधार दरमा थप गरिने प्रिमियम दर तय गर्दा ब्याजदर अन्तर सम्बन्धी यसै निर्देशनको बुँदा नं. ४ को व्यवस्थालाई पूर्ण रूपमा पालना गर्नु पर्नेछ ।
(१३) कर्जाको ब्याजदर परिवर्तन गर्दा पछिल्लो तीन महिनाको औसत आधार दरमा भएको घटबढको सीमासम्म मासिक रूपमा परिवर्तन गर्नुपर्नेछ ।
तर, पछिल्लो तीन महिनाको औसत आधार दरमा भएको परिवर्तनभन्दा बढीले ब्याजदर घटाउन, जुनसुकै अवस्थामा ब्याजदर वृद्धि गर्न वा ऋणी तथा बचतकर्ताको सहमतिको सीमामा राख्न यस व्यवस्थाले बाधा पुर्याएको छैन । यसरी पछिल्लो तीन महिनाको औसत आधार दरमा परिवर्तन हुँदा ब्याजदरमा परिवर्तन हुने/नहुने सम्बन्धमा ऋणीलाई offer letter मा स्पष्ट रूपमा उल्लेख गरी अनिवार्य जानकारी दिने व्यवस्था गर्नुपर्नेछ । परिवर्तनशील ब्याजदर आधार दरसँग आबद्ध गर्दा इजाजतपत्रप्राप्त संस्थाको Core Banking System मार्फत पछिल्लो तीन महिनाको औसत आधार दरमा भएको परिवर्तनअनुसार स्वतः ब्याजदर परिवर्तन हुने प्रणालीको व्यवस्था गर्नु पर्नेछ । साथै, ब्याजदर घटाउँदा वा वृद्धि गर्दा सबै ग्राहकले समान रूपमा सुविधा पाउने गरी व्यवस्था मिलाउनु पर्नेछ ।
(१४) इजाजतपत्रप्राप्त संस्थाले इ.प्रा. निर्देशन नं १७ (विपन्न वर्गमा प्रवाह गर्नुपर्ने कर्जा सम्बन्धी व्यवस्था) बमोजिम ज्येष्ठ नागरिक, दलित, मुक्त कमैया, वादी, हलिया, द्वन्द्व पीडित, एकल महिला तथा फरक ढंगले सक्षम व्यक्तिलाई प्रवाह गर्ने विपन्न वर्ग कर्जाको ब्याज दरमा कम्तीमा एक प्रतिशत बिन्दुले सहुलियत दिने व्यवस्था मिलाउनु पर्नेछ ।
(१५) व्यक्तिगत आवधिक कर्जाको ब्याजदर सम्बन्धी व्यवस्था:
(क) एक वर्ष भन्दा बढी भुक्तानी अवधि भएका व्यक्तिगत आवधिक कर्जाहरुको ब्याजदर परिवर्तन नहुने गरी स्थिर ब्याजदर कायम गर्नु पर्नेछ । यस प्रयोजनको लागि इजाजतपत्रप्राप्त संस्थाले एक वर्ष भन्दा बढी भुक्तानी अवधि भएका प्रत्येक व्यक्तिगत आवधिक कर्जाको ब्याजदर भुक्तानी अवधिभर परिवर्तन नहुने गरी स्थिर ब्याजदर (Fixed interest rate) निर्धारण गर्नुपर्नेछ ।
तर, ग्राहक स्वयंले इजाजतपत्रप्राप्त संस्थाको आधार दर परिवर्तन हुँदा परिवर्तन हुने परिवर्तनशील ब्याजदर (adjustable interest rate) मा कर्जा लिन चाहेमा ग्राहकको अनुरोधमा परिवर्तनशील ब्याजदर कायम गर्न यो व्यवस्थाले बाधा पुर्याएको मानिने छैन ।
(ख) यो व्यवस्था व्यक्तिको नाममा प्रवाह भएका/हुने घर कर्जा (home loan/housing loan), गाडी कर्जा (auto loan/vehicle loan/hirepurchase loan) लगायतका आवधिक कर्जाको हकमा ग्राहकको कर्जा स्वीकृत/भुक्तानी गर्दा लागू हुनेछ ।
(ग) यो निर्देशन जारी हुनुपूर्व मासिक/त्रैमासिक/आवधिक किस्तामा भुक्तानी हुने गरी व्यक्तिको नाममा प्रवाह भएका घर कर्जा (home loan/housing loan), गाडी कर्जा (auto loan/vehicle loan/hirepurchase loan) लगायतका आवधिक कर्जाको हकमा ग्राहकको अनुरोधमा स्थिर ब्याजदर कायम हुने गरी कर्जाका शर्तहरु परिवर्तन गर्नु पर्नेछ ।
(घ) यो व्यवस्थाको अनुपालनको लागि कर्जाका शर्त वा भुक्तानी तालिका वा किस्ता रकममा भएको परिवर्तनलाई पुनर्तालिकीकरण वा पुनर्संरचना मानिने छैन ।
(ङ) उपबुँदा (क) अनुसारको कर्जा अवधि भर परिवर्तन नहुने गरी नयाँ कर्जाको लागि तोकिएको स्थिर ब्याजदर (Fixed interest rate) अर्धवार्षिक रूपमा मात्र निर्धारण तथा प्रकाशन गर्नुपर्नेछ ।
(च) उपबुँदा (क) अनुसारको कर्जा अवधि भर परिवर्तन नहुने गरी प्रवाहित कर्जामा ऋणीसँगको लिखित सहमतिमा पहिलो पटक ७ वर्षमा र तत्पश्चात् प्रत्येक ५ वर्षमा ब्याजदर पुनरावलोकन गर्न सकिने छ । यसबाहेक अन्य जुनसुकै कारणबाट यस्ता कर्जाको ब्याज परिवर्तन गर्न पाइने छैन ।
(१६) इजाजतपत्रप्राप्त संस्थाहरुले मुद्दती निक्षेपकर्ता ग्राहकलाई सो मुद्दती निक्षेप रसिदको धितोमा कर्जा प्रदान गर्दा त्यस्तो कर्जामा लाग्ने ब्याजदर मुद्दती निक्षेपमा प्रदान गरिएको ब्याजदरमा के कति प्रतिशत बिन्दुले थप गरी तय गरिने हो वा आधार दरको आधारमा तय गर्ने हो भने के कति प्रिमियम थप गरी तय गरिने हो, सो सम्बन्धमा सम्बन्धित ग्राहकलाई मुद्दती निक्षेप खाता खोल्दाकै बखत जानकारी दिई निजको लिखित सहमति लिनुपर्नेछ । यस्तो सहमति पछि पुनः पुनः परिवर्तन गरी कर्जाको ब्याजदर कायम गर्न पाइने छैन ।
(१७) बैंक तथा वित्तीय संस्थाले लघुवित्त वित्तीय संस्थालाई विपन्न वर्ग कर्जा अन्तर्गत थोक कर्जा प्रवाह गर्दा आधार दरमा २ प्रतिशत बिन्दुसम्म मात्र प्रिमियम थप गरी ब्याजदर निर्धारण गर्नुपर्नेछ ।
Controlled English translation
Interest rates charged on loans and advances, the method of interest calculation, the method of imposing penal charges, service charges and commission rates may be determined in compliance with prevailing law and the following standards.
(1) When determining interest rates on loans and advances, the rate shall be linked to the “Base Rate” calculated in accordance with Schedule 15.1. The interest rate on a rescheduled or restructured loan shall also be determined on the basis of the Base Rate.
(2) The agreement entered into with the borrower when granting credit shall state a penal interest rate not exceeding 2 percentage points per annum. For the period in which penal interest applies, an amount exceeding the penal interest calculated on the unpaid outstanding amount from the due date for the period of delay shall not be charged, and interest shall not be charged on penal interest.
However, where an enterprise/business that has used credit of up to NPR 55 million from banks and financial institutions pays, by the end of Ashwin 2080, the principal and interest on the credit that were payable by the end of Ashadh 2080, arrangements shall be made not to impose any additional penalty or penal interest.
(3) Separate premium rates shall be fixed on the basis of the type of credit and repayment period, and the interest rates on loans and advances shall be determined and published monthly. Notice of the interest rates applicable for the coming month shall be published before the commencement of the Nepali month.
(4) When publishing interest rates, the premium rate to be added to the Base Rate for each loan heading shall be stated clearly. An increase in a published premium rate may be made half-yearly. Where the premium rate is to be reduced, the published premium rate may be reduced in a period shorter than half-yearly.
(5) When determining the interest rate on a loan or advance to a person or firm, the premium rate to be added to the Base Rate shall be clearly stated. For example, if a premium of 2 percentage points is to be added to the Base Rate in determining a customer’s lending rate:
Loan interest rate = Base Rate + 2 percentage points.
(6) No loan shall be extended at an interest rate below the average Base Rate for the latest three months. However, this provision shall not prevent lending below the average Base Rate under a programme of the Government of Nepal, a Provincial Government or a Local Level that provides concessional-rate assistance/subsidy through banks and financial institutions for lending to specified sectors and classes.
(7) In determining the interest rate on loans and advances, the difference in rates among loans and advances of the same nature shall not exceed 2 percentage points.
(8) Banks and financial institutions shall publish a Fixed Interest Rate in addition to the Adjustable Interest Rate for all term-type loans they provide.
(9) The Offer Letter issued to the borrower shall clearly state the premium rate to be added to the Base Rate. The premium rate fixed shall not exceed the premium rate published at the time the loan application was received.
(10) Once a premium rate has been fixed, stated in the loan offer and the loan approved, the premium rate shall not subsequently be increased, nor shall a scheme be applied under which a discount is provided and the rate subsequently increases automatically. However, where the borrower does not use the loan for the purpose for which it was obtained and the loan agreement contains a provision to that effect, nothing in this provision shall prevent adding a penalty rate for misuse of the loan.
(11) When a borrower’s credit limit is increased, or for a new loan extended by a bank or financial institution, the newly published premium rate shall apply.
(12) When a licensed institution determines the premium rate to be added to the Base Rate in determining the interest rate on loans and advances, it shall fully comply with Clause 4 of this Directive relating to the interest-rate spread.
(13) When changing a lending rate, it shall be changed monthly within the extent of the increase or decrease in the average Base Rate for the latest three months.
However, this provision shall not prevent reducing the interest rate by more than the change in the latest three-month average Base Rate, increasing the interest rate in circumstances otherwise permitted, or maintaining the rate within the limits agreed with borrowers and depositors. The borrower shall be mandatorily informed in the Offer Letter whether or not the rate will change when the latest three-month average Base Rate changes. When an adjustable interest rate is linked to the Base Rate, the licensed institution shall arrange a system through its Core Banking System so that the interest rate changes automatically according to changes in the latest three-month average Base Rate. When increasing or decreasing rates, arrangements shall ensure that all customers receive the benefit equally.
(14) A licensed institution shall provide at least a one-percentage-point concession in the interest rate on deprived-sector credit extended, pursuant to Directive No. 17, to senior citizens, Dalits, freed Kamaiyas, Badis, Haliyas, conflict-affected persons, single women and differently-abled persons.
(15) Provisions relating to the interest rate on individual term loans:
(a) An individual term loan with a repayment period exceeding one year shall carry a Fixed Interest Rate that does not change. For this purpose, a licensed institution shall determine for each individual term loan exceeding one year a Fixed Interest Rate that remains unchanged throughout the repayment period.
However, where the customer wishes to take the loan at an adjustable interest rate that changes when the licensed institution’s Base Rate changes, nothing shall prevent maintaining an adjustable interest rate at the customer’s request.
(b) This provision shall apply to term loans in the name of individuals, including home loans/housing loans and auto loans/vehicle loans/hire-purchase loans, when such credit is approved/disbursed.
(c) For home loans/housing loans, auto loans/vehicle loans/hire-purchase loans and other term loans already extended in the name of individuals before issuance of this Directive and repayable monthly/quarterly/periodically, the loan terms shall be changed at the customer’s request so as to maintain a Fixed Interest Rate.
(d) For compliance with this provision, a change in loan terms, repayment schedule or instalment amount shall not be treated as rescheduling or restructuring.
(e) The Fixed Interest Rate fixed for a new loan so as not to change throughout the loan period under paragraph (a) shall be determined and published only half-yearly.
(f) For a loan extended with a rate fixed for the entire loan period under paragraph (a), the interest rate may, with the borrower’s written consent, be reviewed for the first time after seven years and thereafter every five years. The interest rate on such loan shall not be changed for any other reason.
(16) When a licensed institution grants credit to a fixed-deposit customer against the fixed-deposit receipt, the customer shall, at the time the fixed-deposit account is opened, be informed in writing whether the lending rate will be determined by adding a specified number of percentage points to the interest rate provided on the fixed deposit, or by adding a specified premium to the Base Rate; the customer’s written consent shall be obtained. After such consent, the lending rate shall not be repeatedly changed.
(17) When a bank or financial institution provides wholesale credit to a microfinance financial institution under deprived-sector lending, the interest rate shall be determined by adding a premium of not more than 2 percentage points to the Base Rate.
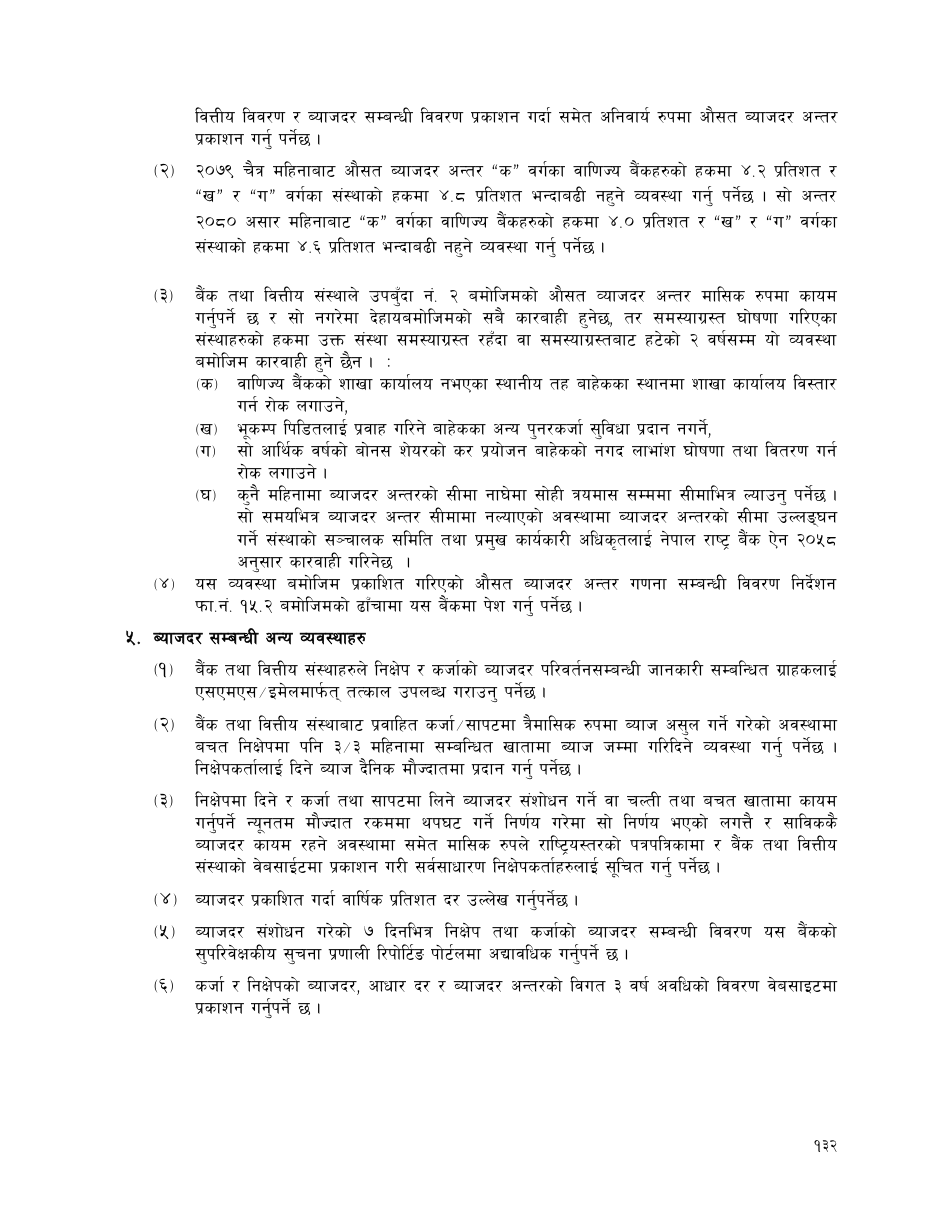
(१) निक्षेपमा दिने र कर्जा तथा सापटमा लिने ब्याजदर बीचको औसत अन्तर अनुसूची-१५.२ बमोजिमको सूत्रबाट प्रत्येक महिना गणना गरी आफ्नो वेबसाइटमा प्रकाशन गर्नु पर्नेछ । साथै प्रत्येक त्रैमासको वित्तीय विवरण र ब्याजदर सम्बन्धी विवरण प्रकाशन गर्दा समेत अनिवार्य रूपमा औसत ब्याजदर अन्तर प्रकाशन गर्नु पर्नेछ ।
(२) २०७९ चैत्र महिनाबाट औसत ब्याजदर अन्तर “क” वर्गका वाणिज्य बैंकहरुको हकमा ४.२ प्रतिशत र “ख” र “ग” वर्गका संस्थाको हकमा ४.८ प्रतिशत भन्दा बढी नहुने व्यवस्था गर्नु पर्नेछ । सो अन्तर २०८० असार महिनाबाट “क” वर्गका वाणिज्य बैंकहरुको हकमा ४.० प्रतिशत र “ख” र “ग” वर्गका संस्थाको हकमा ४.६ प्रतिशत भन्दा बढी नहुने व्यवस्था गर्नु पर्नेछ ।
(३) बैंक तथा वित्तीय संस्थाले उपबुँदा नं. २ बमोजिमको औसत ब्याजदर अन्तर मासिक रूपमा कायम गर्नुपर्नेछ र सो नगरेमा देहायबमोजिमको सबै कारवाही हुनेछ, तर मध्यावधिमा घोषणा गरिएका संस्थाहरुको हकमा उक्त संस्था समस्याग्रस्त रहे वा समस्याग्रस्तबाट हटेको २ वर्षसम्म यो व्यवस्था बमोजिम कारवाही हुने छैन:
(क) वाणिज्य बैंकको शाखा कार्यालय नभएका स्थानीय तह बाहेकका स्थानमा शाखा कार्यालय विस्तार गर्न रोक लगाउने,
(ख) भूकम्प पीडितलाई प्रवाह गरिने बाहेकका अन्य पुनरकर्जा सुविधा प्रदान नगर्ने,
(ग) सो आर्थिक वर्षको बोनस शेयरको कर प्रयोजन बाहेकको नगद लाभांश घोषणा तथा वितरण गर्न रोक लगाउने ।
(घ) कुनै महिनामा ब्याजदर अन्तरको सीमा नाघेमा सोही त्रैमास सम्ममा सीमाभित्र ल्याउनु पर्नेछ । सो समयभित्र ब्याजदर अन्तर सीमाभित्र नल्याएको अवस्थामा ब्याजदर अन्तरको सीमा उल्लङ्घन गर्ने संस्थाको सञ्चालक समिति तथा प्रमुख कार्यकारी अधिकृतलाई नेपाल राष्ट्र बैंक ऐन २०५८ अनुसार कारवाही गरिनेछ ।
(४) यस व्यवस्था बमोजिम प्रकाशित गरिएको औसत ब्याजदर अन्तर गणना सम्बन्धी विवरण निर्देशन फा.नं. १५.२ बमोजिमको ढाँचामा यस बैंकमा पेश गर्नु पर्नेछ ।
Controlled English translation
(1) The average spread between interest paid on deposits and interest charged on loans and advances shall be calculated every month using the formula in Schedule 15.2 and published on the institution’s website. The average interest-rate spread shall also be published mandatorily when publishing each quarterly financial statement and interest-rate-related statement.
(2) From Chaitra 2079, the average interest-rate spread shall not exceed 4.2 percent for Class “A” commercial banks and 4.8 percent for Class “B” and “C” institutions. From Ashadh 2080, the spread shall not exceed 4.0 percent for Class “A” commercial banks and 4.6 percent for Class “B” and “C” institutions.
(3) A bank or financial institution shall maintain the average interest-rate spread referred to in sub-clause (2) on a monthly basis; if it fails to do so, all of the following actions shall apply. However, in the case of an institution declared problematic, such action shall not apply while the institution remains problematic or for two years after it is released from problematic status:
(a) prohibition on branch expansion at locations other than Local Levels without a commercial-bank branch;
(b) no refinance facility other than refinance provided to earthquake-affected persons;
(c) prohibition on declaration and distribution of cash dividends, except cash dividend for tax purposes in respect of bonus shares for that fiscal year;
(d) where the spread limit is exceeded in any month, it shall be brought within the limit by the end of the same quarter. If the spread is not brought within the limit within that period, action shall be taken under the Nepal Rastra Bank Act, 2058 against the Board of Directors and Chief Executive Officer of the institution violating the spread limit.
(4) The statement relating to calculation of the average interest-rate spread published under this provision shall be submitted to this Bank in the format of Directive Form No. 15.2.
(१) बैंक तथा वित्तीय संस्थाहरुले निक्षेप र कर्जाको ब्याजदर परिवर्तनसम्बन्धी जानकारी सम्बन्धित ग्राहकलाई एसएमएस/इमेलमार्फत तत्काल उपलब्ध गराउनु पर्नेछ ।
(२) बैंक तथा वित्तीय संस्थाबाट प्रवाहित कर्जा/सापटमा त्रैमासिक रूपमा ब्याज असुल गर्ने गरेको अवस्थामा बचत निक्षेपमा पनि ३/३ महिनामा सम्बन्धित खातामा ब्याज जम्मा गरिदिने व्यवस्था गर्नु पर्नेछ । निक्षेपकर्तालाई दिने ब्याज दैनिक मौज्दातमा प्रदान गर्नु पर्नेछ ।
(३) निक्षेपमा दिने र कर्जा तथा सापटमा लिने ब्याजदर संशोधन गर्ने वा बचत तथा बचत खातामा कायम गर्नुपर्ने न्यूनतम मौज्दात रकममा थपघट गर्ने निर्णय गरेमा सो निर्णय भएको लगत्तै र साविककै ब्याजदर कायम रहने अवस्थामा समेत मासिक रूपमा राष्ट्रियस्तरको पत्रपत्रिका र बैंक तथा वित्तीय संस्थाको वेबसाइटमा प्रकाशन गरी सर्वसाधारण निक्षेपकर्तालाई सूचित गर्नु पर्नेछ ।
(४) ब्याजदर प्रकाशित गर्दा वार्षिक प्रतिशत दर उल्लेख गर्नुपर्नेछ ।
(५) ब्याजदर संशोधन गरेको ७ दिनभित्र निक्षेप तथा कर्जाको ब्याजदर सम्बन्धी विवरण यस बैंकको सुपरिवेक्षकीय सूचना प्रणाली रिपोर्टिङ पोर्टलमा अध्यावधिक गराउनुपर्नेछ ।
(६) कर्जा र निक्षेपको ब्याजदर, आधार दर र ब्याजदर अन्तरको विगत ३ वर्ष अवधिको विवरण वेबसाइटमा प्रकाशन गर्नुपर्ने छ ।
Controlled English translation
(1) Banks and financial institutions shall immediately provide the concerned customer, by SMS/email, information relating to changes in deposit and lending rates.
(2) Where interest on loans/advances is collected quarterly, arrangements shall also be made to credit interest to the relevant savings-deposit account every three months. Interest payable to depositors shall be provided on the daily balance.
(3) Where a decision is made to revise deposit or lending rates, or to increase or decrease the minimum balance required in a savings account, such decision shall be published immediately; and even where the existing interest rate continues unchanged, the rate shall be published monthly in a national-level newspaper and on the website of the bank or financial institution so as to inform depositors.
(4) When publishing interest rates, the annual percentage rate shall be stated.
(5) Within seven days after revision of an interest rate, details relating to deposit and lending rates shall be updated in this Bank’s Supervisory Information System reporting portal.
(6) Details of lending and deposit rates, the Base Rate and the interest-rate spread for the preceding three-year period shall be published on the website.
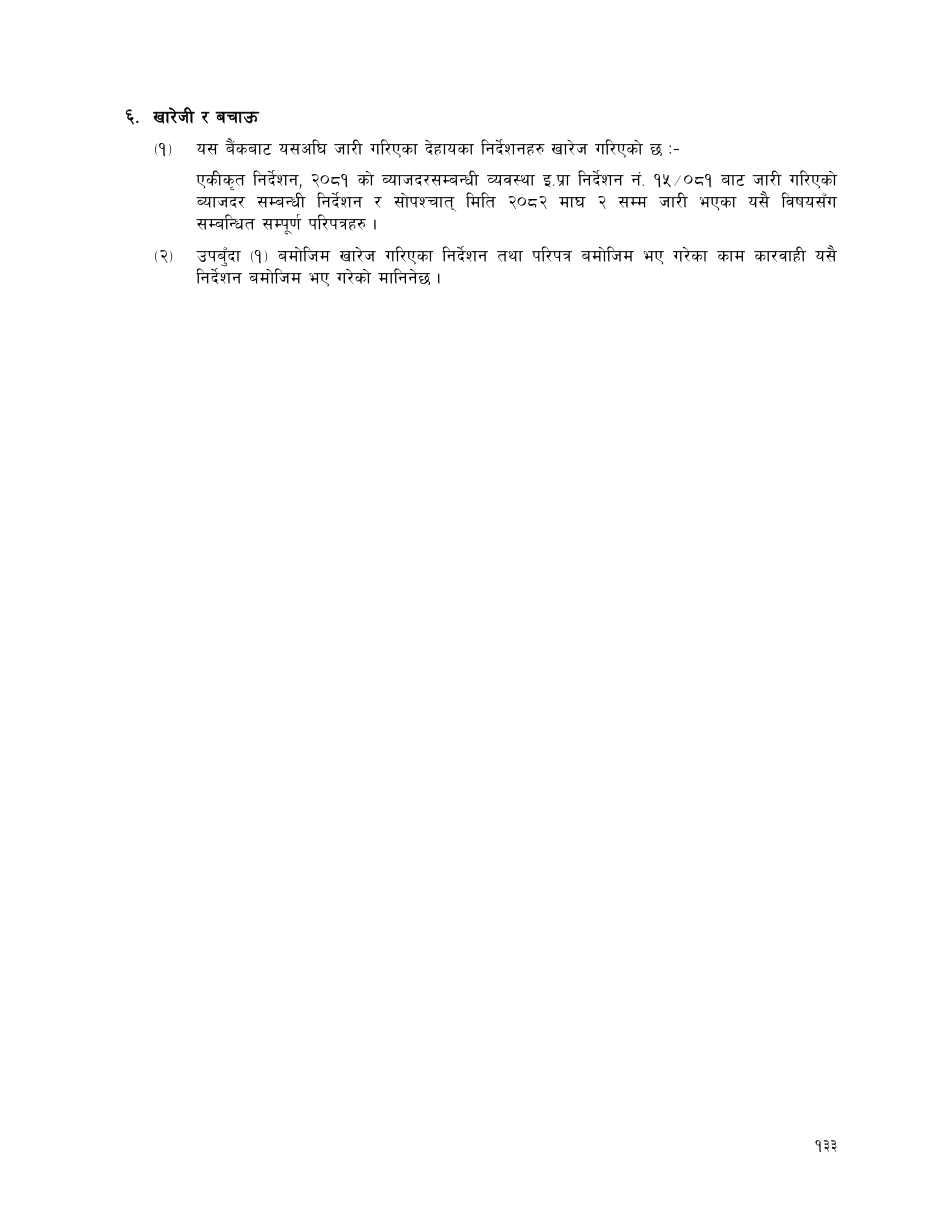
(१) यस बैंकबाट यसअघि जारी गरिएका देहायका निर्देशनहरु खारेज गरिएको छ :-
एकीकृत निर्देशन, २०८१ को ब्याजदरसम्बन्धी व्यवस्था इ.प्रा निर्देशन नं. १५/०८१ बाट जारी गरिएको ब्याजदर सम्बन्धी निर्देशन र सोपश्चात् मिति २०८२ माघ २ सम्म जारी भएका यसै विषयसँग सम्बन्धित सम्पूर्ण परिपत्रहरु ।
(२) उपबुँदा (१) बमोजिम खारेज गरिएका निर्देशन तथा परिपत्र बमोजिम भए गरेका काम कारवाही यसै निर्देशन बमोजिम भए गरेको मानिनेछ ।
Controlled English translation
(1) The following directives previously issued by this Bank are hereby repealed:
the directive relating to interest rates issued as Directive No. 15/081 under the interest-rate provisions of the Unified Directives, 2081, and all circulars relating to the same subject issued thereafter up to Magh 2, 2082.
(2) Any acts or actions done or taken pursuant to the directives and circulars repealed under sub-clause (1) shall be deemed to have been done or taken pursuant to this Directive.
Structured schedules and forms are presented in the supplied order without altering their content.
Source Images
image98.png
image99.png
Source Pages
218
219
Formula
नेपाली मूल पाठ
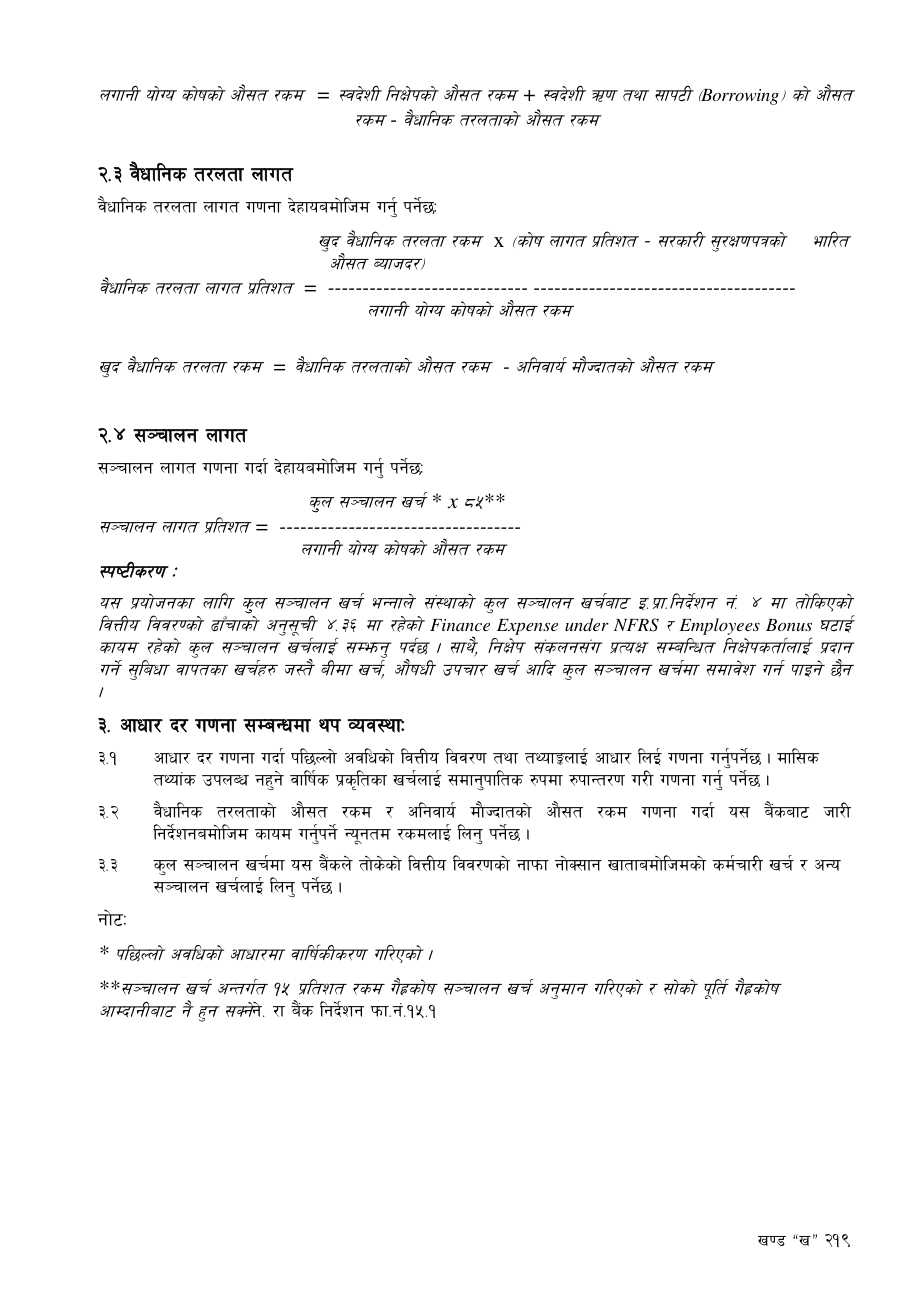
आधार दर = कोष लागत प्रतिशत + अनिवार्य मौज्दात लागत प्रतिशत + वैधानिक तरलता लागत प्रतिशत + सञ्चालन लागत प्रतिशत
Controlled English translation
Base Rate = Cost of Fund percentage + Compulsory Reserve Cost percentage + Statutory Liquidity Cost percentage + Operating Cost percentage
Components
Id
Ne
En
Formula
Formula
2.1
कोषको लागत (Cost of Fund)
Cost of Fund
कोष लागत प्रतिशत = स्वदेशी निक्षेप र ऋण तथा सापटीको भारित औसत ब्याजदर
Cost of Fund percentage = weighted average interest rate on domestic deposits and loans/borrowings
2.2
अनिवार्य मौज्दात लागत
Compulsory Reserve Cost
अनिवार्य मौज्दात लागत प्रतिशत = (अनिवार्य मौज्दातको औसत रकम × कोष लागत प्रतिशत) / लगानी योग्य कोषको औसत रकम
Compulsory Reserve Cost percentage = (average compulsory-reserve amount × Cost of Fund percentage) / average lendable-fund amount
2.3
वैधानिक तरलता लागत
Statutory Liquidity Cost
वैधानिक तरलता लागत प्रतिशत = [खुद वैधानिक तरलता रकम × (कोष लागत प्रतिशत - सरकारी सुरक्षणपत्रको भारित औसत ब्याजदर)] / लगानी योग्य कोषको औसत रकम
Statutory Liquidity Cost percentage = [net statutory-liquidity amount × (Cost of Fund percentage - weighted average interest rate on Government securities)] / average lendable-fund amount
2.4
सञ्चालन लागत
Operating Cost
सञ्चालन लागत प्रतिशत = (कुल सञ्चालन खर्च* × ८५%**) / लगानी योग्य कोषको औसत रकम
आधार दर गणना गर्दा पछिल्लो अवधिको वित्तीय विवरण तथा तथ्याङ्कलाई आधार लिई गणना गर्नुपर्नेछ । मासिक तथ्याङ्क उपलब्ध नहुने वार्षिक प्रकृतिका खर्चलाई समानुपातिक रुपमा रूपान्तरण गरी गणना गर्नु पर्नेछ ।
वैधानिक तरलताको औसत रकम र अनिवार्य मौज्दातको औसत रकम गणना गर्दा यस बैंकबाट जारी निर्देशनबमोजिम कायम गर्नुपर्ने न्यूनतम रकमलाई लिनु पर्नेछ ।
कुल सञ्चालन खर्चमा यस बैंकले तोकेको वित्तीय विवरणको नाफा नोक्सान खाताबमोजिमको कर्मचारी खर्च र अन्य सञ्चालन खर्चलाई लिनु पर्नेछ ।
Controlled English translation
Additional Rules
The Base Rate shall be calculated on the basis of the latest-period financial statements and data. Annual-type expenses for which monthly data are not available shall be converted proportionately.
When calculating average Statutory Liquidity and average Compulsory Reserve, the minimum amounts required under directives issued by this Bank shall be used.
Total operating expenses shall comprise employee expenses and other operating expenses according to the profit-and-loss account in the financial-statement format prescribed by this Bank.
Base Source Footnotes
* Annualised on the basis of the immediately preceding period in the original source.
** The original source estimates 15 percent of operating expense as attributable to non-fund-based business and therefore uses 85 percent for funded-business operating cost.
Later Amendment
Text
नेपाली मूल पाठ
परिपत्र नं. १ (क, ख, ग), २०८३/८४ (२७ अगस्ट २०२६) ले अनुसूची १५.१ को operating-cost calculation annualise गर्ने सूत्र स्पष्ट गरी non-fund-based कारोबारको operating expense अनुमान कुल आम्दानीको १५ प्रतिशतबाट १० प्रतिशतमा घटाएको छ।
Controlled English translation
Circular No. 1 (A, B and C), 2083/84 (27 August 2026), clarified the annualisation formula for operating cost in Schedule 15.1 and reduced the estimated operating expense for non-fund-based business from 15% to 10% of total income from that business.
Source Status: Supplied compilation amendment record; exact circular text is not reproduced in the base source images.
Publication Treatment: Display as an amendment note until the exact circular text supplied by NRB is available for verbatim consolidation; do not silently rewrite the original source image.
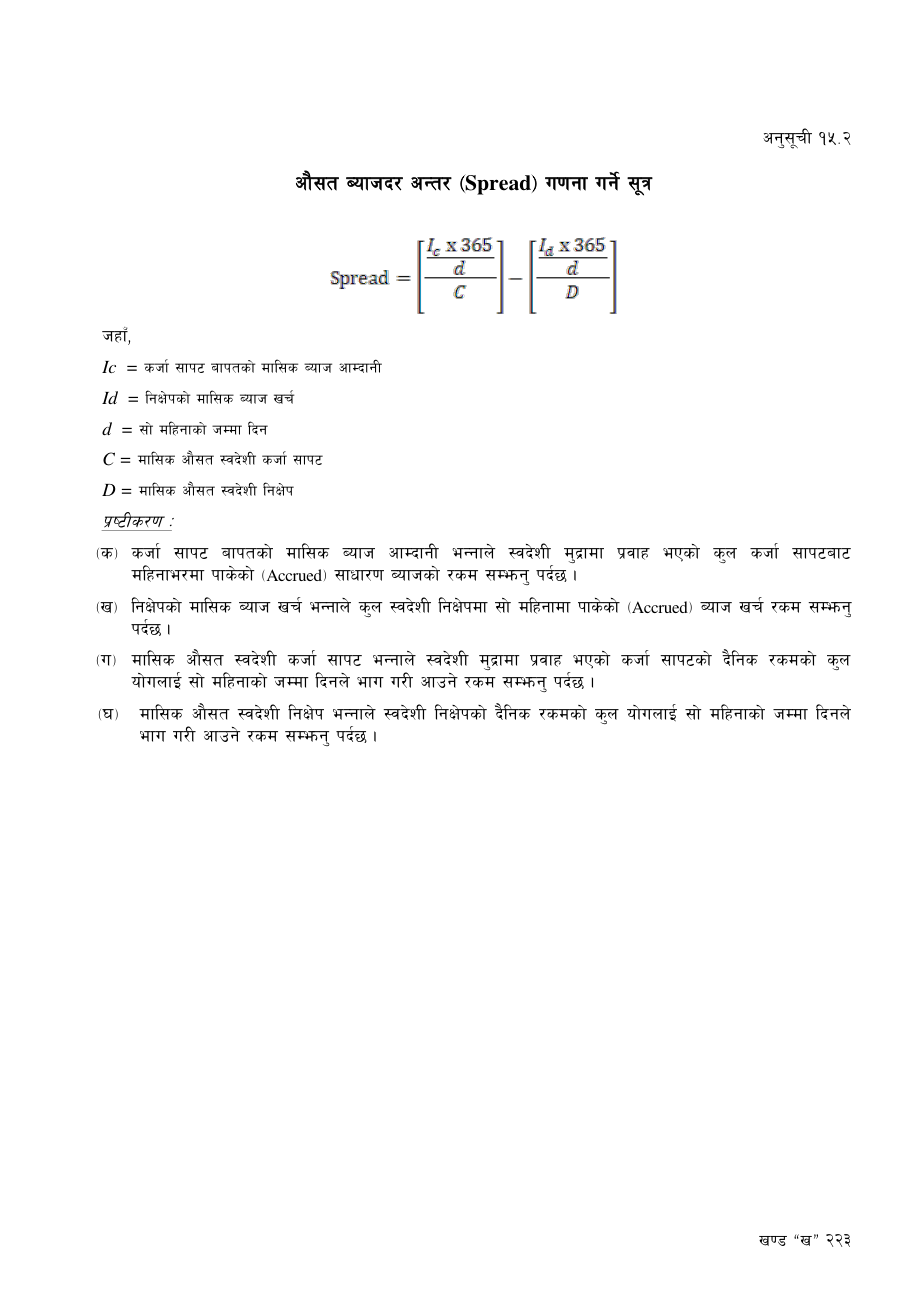
कर्जा सापट वापतको मासिक ब्याज आम्दानी भन्नाले स्वदेशी मुद्रामा प्रवाह भएको कुल कर्जा सापटबाट महिनाभरमा पाकेको (Accrued) आधारमा ब्याजको रकम सम्झनु पर्दछ ।
Monthly interest income from loans and advances means interest accrued during the month on total loans and advances extended in domestic currency.
निक्षेपको मासिक ब्याज खर्च भन्नाले कुल स्वदेशी निक्षेपमा सो महिनामा पाकेको (Accrued) ब्याज खर्च रकम सम्झनु पर्दछ ।
Monthly interest expense on deposits means interest expense accrued during the month on total domestic deposits.
मासिक औसत स्वदेशी कर्जा सापट भन्नाले स्वदेशी मुद्रामा प्रवाह भएको कर्जा सापटको दैनिक रकमको कुल योगलाई सो महिनाको जम्मा दिनले भाग गरी आउने रकम सम्झनु पर्दछ ।
Monthly average domestic loans and advances means the amount obtained by dividing the aggregate daily balance of loans and advances extended in domestic currency by the total number of days in the month.
मासिक औसत स्वदेशी निक्षेप भन्नाले स्वदेशी निक्षेपको दैनिक रकमको कुल योगलाई सो महिनाको जम्मा दिनले भाग गरी आउने रकम सम्झनु पर्दछ ।
Monthly average domestic deposits means the amount obtained by dividing the aggregate daily balance of domestic deposits by the total number of days in the month.
सरकारी सुरक्षणपत्रमा गरेको लगानीमा प्राप्त कुल ब्याज रकम
नाफा नोक्सान हिसाब बमोजिमको कुल सञ्चालन खर्च ((अ)+(आ))
कर्मचारी खर्च
अन्य सञ्चालन खर्च
आधार दर गणना प्रयोजनका लागि कुल सञ्चालन खर्च
कर्मचारी खर्च
अन्य सञ्चालन खर्च
नाफा नोक्सान हिसाब बमोजिम पछिल्लो महिनाको खुद नाफा/(नोक्सान)
Note
नेपाली मूल पाठ
यस प्रयोजनका लागि पछिल्लो महिनाको मात्र आम्दानी र खर्चको (खर्चको हकमा वार्षिकीकरण वा अनुमान गर्नु पर्ने भए सोही बमोजिमको पछिल्लो महिनाको खर्च) रकमलाई यसै फारामको बुँदा नं. (२) अन्तर्गतको थप विवरणमा उल्लेख गरी सोही बमोजिम आधार दर गणना गर्नु पर्नेछ ।
Controlled English translation
For this purpose, only the income and expenditure of the immediately preceding month (and, where expenditure is required to be annualised or estimated, the corresponding expenditure of that immediately preceding month) shall be reported in the additional details under item (2) of this form and the Base Rate shall be calculated accordingly.
Original Nepali text is authoritative. English is a controlled facilitative translation and is not an official Nepal Rastra Bank translation.
In case of inconsistency, ambiguity or difference, the official Nepali Directive and applicable Nepal Rastra Bank circulars prevail.
C.M. & Associates is not affiliated with, approved by or endorsed by Nepal Rastra Bank. This material is provided for information and reference only and does not constitute legal, regulatory, tax or professional advice.
Technical controls cannot guarantee prevention of screenshots or copying.