Directive 14शाखा/कार्यालय खोल्ने सम्बन्धी व्यवस्थाProvisions Relating to Opening Branches / Offices
Original/reproduced Nepali source controls; English is a controlled facilitative translation.
Applicability Class A licensed institutions; Class B licensed institutions; Class C licensed institutions
Classification PASS WITH EXPLICIT SOURCE GAP
Updated-through statement Circular No. 2 (A/B/C): Later amendment recorded; exact circular wording not reproduced.
Rendering basis Render web-normalized sections and canonical supplemental objects exactly. Canonical reviewed JSON is authoritative for web/PDF. Do not OCR or rewrite legal text.
नेपाली मूल पाठ
यस बैंकबाट “क”, “ख” र “ग” वर्गका इजाजतपत्रप्राप्त संस्थाको शाखा/कार्यालय खोल्ने व्यवस्थाका सम्बन्धमा नेपाल राष्ट्र बैंक ऐन, २०५८ को दफा ७९ ले दिएको अधिकार प्रयोग गरी देहायका निर्देशन जारी गरिएको छ :-
Controlled English translation
In exercise of the authority conferred by Section 79 of the Nepal Rastra Bank Act, 2058, the following directives are issued in relation to the opening of branches/offices by Class “A”, “B” and “C” licensed institutions.
(क) इजाजतपत्रप्राप्त संस्थाले महानगरपालिका र उप महानगरपालिकामा शाखा कार्यालय खोल्न यस बैंकको पूर्व स्वीकृति लिनुपर्नेछ । शाखा कार्यालय तथा एक्सटेन्सन काउन्टर खोली कारोबार शुरु गरेकै दिन उक्त शाखा तथा एक्सटेन्सन काउन्टर सम्बन्धी विवरण यस बैंकको रिपोर्टिङ पोर्टलमा र सुपरिवेक्षण सूचना प्रणाली रिपोर्टिङ पोर्टलमा अध्यावधिक गर्नु पर्नेछ ।
(ख) देहायको अवस्था पूरा गरेको इजाजतपत्रप्राप्त संस्थाले आफ्नो कार्यक्षेत्र भित्र नयाँ शाखा कार्यालय खोल्न सक्नेछ:
(अ) शाखा विस्तार गर्नका लागि प्रस्तावित स्थान वित्तीय रुपले सम्भाव्य रहेको स्थलगत अध्ययन प्रतिवेदन तयार गर्नु पर्ने ।
(आ) यस बैंकको नीतिगत व्यवस्था तथा निर्देशन बमोजिम तोकिएको न्यूनतम चुक्ता पुँजी कायम गरेको ।
(इ) यस बैंकबाट इजाजतपत्र प्रदान गर्दा तोकिएका शर्तहरु पूरा गर्नुका साथै शाखा खोल्नु अगाडिको त्रैमासिक वित्तीय विवरणमा यस बैंकले तोकेको पुँजीकोष कायम गरेको ।
(ई) शाखा कार्यालयमा सूचना आदान प्रदान गर्नको लागि नेटवर्किङ (Networking) गरी वा विद्युतीय माध्यमबाट केन्द्रीय कार्यालयमा सूचना प्रणालीमा तत्काल आवद्ध हुन सक्ने व्यवस्था गरेको ।
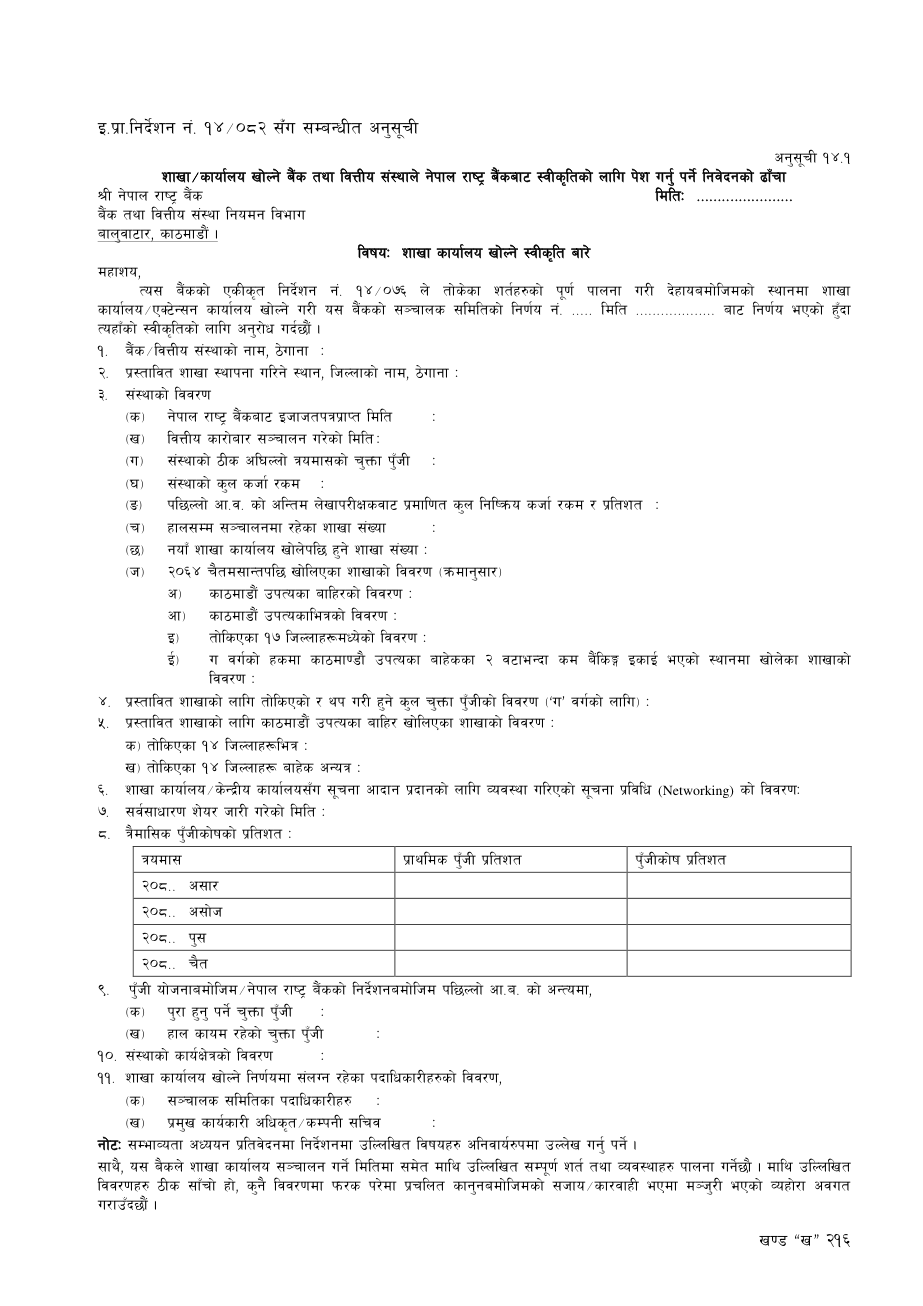
(उ) सम्बन्धित संस्थाको सञ्चालक समितिबाट शाखा कार्यालय स्थापना/सञ्चालन गर्ने सम्बन्धी निर्णय भएको हुनु पर्ने । सञ्चालक समितिले निर्णय गरेको मितिले १५ दिनभित्र यस बैंक समक्ष संलग्न अनुसूची १४.१ बमोजिमको ढाँचाको फाराम भरी स्वीकृतिको लागि आवेदन दिनु पर्नेछ । यस बैंकबाट स्वीकृति पाएको मितिले छ महिनाभित्रमा शाखा कार्यालय खोली कारोबार सञ्चालन गरी सक्नु पर्ने ।
(ग) माथि उल्लिखित शर्त तथा व्यवस्थाहरु पूरा नभएको अवस्थामा इजाजतपत्रप्राप्त संस्थालाई विशेष परिस्थितिमा कुनै स्थानमा शाखा स्थापना गर्न आवश्यक देखिएमा यस बैंकले स्वीकृति दिन सक्नेछ ।
(घ) शाखा विस्तार गर्ने स्वीकृति प्रदान गर्दा ग्रामीण क्षेत्रमा बैंकिङ कारोबार, वैदेशिक रोजगारी, विप्रेषण तथा उक्त बैंक वा वित्तीय संस्थाबाट कृषि, ऊर्जा, पर्यटन र लघु उद्यमको क्षेत्रमा कर्जा प्रवाह हुन सक्ने वृद्धिको स्थिति झल्कने गरी पेश गरिएको सम्भाव्यता अध्ययन प्रतिवेदन समेतलाई आधार बनाइनेछ । शाखा स्थापनाको लागि पेश गरिने सम्भाव्यता अध्ययन प्रतिवेदनमा प्रस्तावित शाखा स्थापनाको लागि हुने पुँजीगत तथा अन्य खर्चहरु, तीन वर्षभित्रमा सोही संस्थाको अन्तरशाखा ब्याज आम्दानी बाहेकका बैंकिङ कारोबारबाट प्रस्तावित शाखा मुनाफामा सञ्चालित हुन सक्ने आधार समेत समावेश गर्नु पर्नेछ ।
(ङ) काठमाडौं उपत्यका बाहिर तीन वटा शाखा खोली सञ्चालनमा ल्याए पश्चात् मात्र काठमाडौं उपत्यकामा बैंकिङ सेवाको पहुँच कम भएका स्थानलाई पहिलो प्राथमिकता दिने गरी एक शाखा खोल्न स्वीकृति प्रदान गर्न सकिनेछ । काठमाडौं उपत्यका बाहिर खोल्ने तीन शाखामध्ये कम्तीमा दुई शाखा नगरपालिका वा गाउँपालिकामा खोलिएको हुनुपर्नेछ ।
(च) कुनै इजाजतपत्रप्राप्त बैंक वा वित्तीय संस्थाले यस बैंकबाट समस्याग्रस्त घोषणा गरिएको बैंक वा वित्तीय संस्थाको शाखा खरिद गर्ने भएमा दुबै संस्थाले प्रचलित कानुन तथा आफ्नो आर्थिक प्रशासन विनियमावलीको अधीनमा रही शाखा खरिद बिक्री गर्न सक्नेछन् । काठमाडौं उपत्यका लगायत अन्य कुनै पनि स्थानमा अवस्थित समस्याग्रस्त बैंक तथा वित्तीय संस्थाको शाखा कार्यालय खरिद गरी सञ्चालन गरेमा शाखा खरिद गर्ने बैंक तथा वित्तीय संस्थालाई माथि उल्लिखित खण्ड (च) को व्यवस्था अनिवार्य हुने छैन ।
तर यस बैंकबाट समस्याग्रस्त घोषणा नभई विशेष निगरानीमा रहेका बैंक वा वित्तीय संस्थाको शाखा कार्यालय खरिद बिक्री सम्बन्धमा यस बैंकको पूर्व स्वीकृति लिएर मात्र गर्न/गराउन सकिनेछ ।
(छ) प्रादेशिक कार्यालय सम्बन्धी व्यवस्था:
(१) “क” वर्गका वाणिज्य बैंकहरुले प्रत्येक प्रदेशमा एक/एक वटाका दरले प्रादेशिक कार्यालयहरु स्थापना गर्नुपर्नेछ ।
(२) “ख” र “ग” वर्गका वित्तीय संस्थाले आवश्यकतानुसार प्रत्येक प्रदेशमा प्रादेशिक कार्यालयहरु स्थापना गर्न सक्नेछन् ।
(३) प्रादेशिक कार्यालय स्थापना गर्दा निम्नानुसारको व्यवस्था/प्रक्रिया पालना गर्नु पर्नेछ:
(अ) एउटै जिल्ला/प्रदेशभित्रका शाखा कार्यालयहरुलाई एउटै प्रादेशिक कार्यालयको मातहतमा राख्नु पर्नेछ ।
(आ) प्रादेशिक कार्यालयले आफ्नो मातहतका शाखा कार्यालयहरुको कामकारवाहीको अनुगमन, निरीक्षण तथा लेखापरीक्षणका अतिरिक्त केन्द्रीय कार्यालयले तोकिदिएका अन्य कार्यहरु जस्तै: आफ्नोलाई तोकिएको सीमाभित्रको शाखा कार्यालयहरुबाट प्राप्त कर्जा फाइल अध्ययन गरी स्वीकृतिको निर्णय दिने, केन्द्रीय कार्यालयबाट प्राप्त स्वीकृतिको व्यवस्थापन गर्ने, मातहतका शाखा कार्यालयहरुको वितरण गर्ने, नयाँ शाखा कार्यालयको लागि सम्भाव्यता अध्ययन गरी प्रतिवेदन तयार गर्ने, सम्बन्धित प्रदेश अन्तर्गतका शाखाहरुको समन्वय, निगरानी, संस्थागत सुशासन, जोखिम व्यवस्थापन एवम् गुनासो सुनुवाई जस्ता कार्यहरु लगायत अन्य प्रशासनिक कार्यहरु समेत गर्न सक्नेछ ।
(इ) प्रादेशिक कार्यालयबाट बैंकिङ कारोबार गर्न/गराउन पाइने छैन ।
(ई) प्रादेशिक कार्यालय खोल्नु पूर्व सम्बन्धित इजाजतपत्रप्राप्त संस्थाको सञ्चालक समितिले सो कार्यालय खोल्ने सम्बन्धमा निर्णय गर्नु पर्नेछ ।
(उ) प्रादेशिक कार्यालय सञ्चालनमा आएको १५ दिनभित्र यस बैंकको बैंक तथा वित्तीय संस्था नियमन विभाग तथा सम्बन्धित सुपरिवेक्षण विभागलाई जानकारी गराउनु पर्नेछ ।
Controlled English translation
(a) A licensed institution shall obtain prior approval of this Bank to open a branch office in a Metropolitan City or Sub-Metropolitan City. On the very day on which a branch office or extension counter commences operations, information relating to such branch or extension counter shall be updated in this Bank’s reporting portal and in the Supervisory Information System reporting portal.
(b) A licensed institution satisfying the following conditions may open a new branch office within its area of operation:
(i) a site-based feasibility study report shall be prepared showing that the proposed location for branch expansion is financially viable;
(ii) the minimum paid-up capital prescribed under the policy arrangements and directives of this Bank shall have been maintained;
(iii) the conditions prescribed by this Bank at the time of licensing shall have been fulfilled and the capital fund prescribed by this Bank shall have been maintained in the quarterly financial statement immediately preceding the opening of the branch;
(iv) arrangements shall have been made for immediate connection of the branch office to the information system at the central office through Networking or electronic means for exchange of information;
(v) the Board of Directors of the concerned institution shall have decided to establish/operate the branch office. Within 15 days from the date of such decision, an application for approval shall be submitted to this Bank in the form prescribed in Schedule 14.1. The branch office shall be opened and business commenced within six months from the date of approval by this Bank.
(c) Where the above conditions and arrangements are not fulfilled, this Bank may, in special circumstances, grant approval to a licensed institution to establish a branch at a location where such establishment is considered necessary.
(d) When granting approval for branch expansion, the feasibility study report shall also be considered, particularly where it demonstrates the potential increase in banking transactions, foreign employment/remittance business, and lending by the bank or financial institution to agriculture, energy, tourism and micro-enterprises in rural areas. The feasibility study report submitted for branch establishment shall include the capital and other costs of the proposed branch and the basis on which the proposed branch can operate profitably within three years from banking transactions other than inter-branch interest income of the same institution.
(e) Approval to open one branch in Kathmandu Valley, giving first priority to areas with low access to banking services, may be granted only after the institution has opened and brought into operation three branches outside Kathmandu Valley. Of the three branches opened outside Kathmandu Valley, at least two shall have been opened in a municipality or rural municipality.
(f) Where a licensed bank or financial institution purchases a branch of a bank or financial institution declared problematic by this Bank, the two institutions may purchase/sell the branch subject to prevailing law and their financial-administration regulations. Where such branch office of a problematic bank or financial institution situated in Kathmandu Valley or elsewhere is purchased and operated, the branch-purchasing bank or financial institution shall not be required to comply with the above branch-opening condition to that extent.
However, purchase/sale of the branch office of a bank or financial institution under special supervision but not declared problematic by this Bank shall be carried out only after obtaining prior approval of this Bank.
(g) Provincial Office:
(1) Class “A” commercial banks shall establish one provincial office in each Province.
(2) Class “B” and “C” financial institutions may establish provincial offices in each Province as necessary.
(3) The following arrangements/procedures shall be followed when establishing a provincial office:
(i) branch offices within the same district/Province shall be placed under one provincial office;
(ii) in addition to monitoring, inspection and audit of branch offices under it, the provincial office may perform other functions assigned by the central office, including study of credit files received from branch offices within its delegated limit and decision on approval, administration of approvals received from the central office, distribution/coordination among branch offices under it, feasibility studies and reports for new branch offices, coordination and supervision of branches in the Province, institutional governance, risk management, grievance handling and other administrative functions;
(iii) no banking transaction shall be carried out through a provincial office;
(iv) before opening a provincial office, the Board of Directors of the concerned licensed institution shall decide to open such office;
(v) within 15 days after the provincial office commences operation, information shall be provided to the Banks and Financial Institutions Regulation Department of this Bank and the concerned Supervision Department.
(क) इजाजतपत्रप्राप्त संस्थाले यस बैंकको पूर्वस्वीकृति बिना शाखा वा कुनै पनि किसिमको कार्यालय बन्द गर्न वा स्थानान्तरण गर्न वा गाभ्न पाउने छैनन् ।
तर, देहायबमोजिमको अवस्थामा इजाजतपत्रप्राप्त संस्था स्वयम्ले निर्णय गरी महानगरपालिकाभित्र रहेका शाखा समायोजन गर्न सक्नेछ:
(१) विद्युतीय भुक्तानी कारोबार बढिरहेको तथा वित्तीय संस्थाको शाखा उल्लेख्य रहेको सन्दर्भमा बैंक तथा वित्तीय संस्था स्वयंले महानगरपालिकामा रहेका शाखा समायोजन/एकीकरण गर्न सक्नेछन् ।
(२) सरकारी निकाय वा सार्वजनिक संस्था लक्षित गरी स्थापना भएको शाखाको हकमा उक्त संस्थाको लिखित सहमति पश्चात् मात्र शाखा समायोजन गर्न सकिनेछ ।
(३) शाखा समायोजन गर्नुपूर्व सर्वसाधारणको जानकारीका लागि कम्तीमा १० (दश) दिनको सूचना राष्ट्रिय स्तरको दैनिक पत्रिका, सम्बन्धित संस्थाको वेबसाइट र उक्त शाखाको सूचनापाटीमा समेत प्रकाशन गर्नुपर्नेछ ।
(४) दुई वा सोभन्दा बढी शाखाहरु समायोजन हुने अवस्थामा समायोजन हुने शाखाका ग्राहकले उक्त संस्थाको कर्जा चुक्ता गर्न चाहेमा सो अवधिमा अन्य सेवा बन्द गर्न चाहेमा कुनै पनि प्रकारको शुल्क नलिई कर्जा चुक्ता वा सेवा स्थगित गर्न सक्ने व्यवस्था मिलाउनु पर्नेछ ।
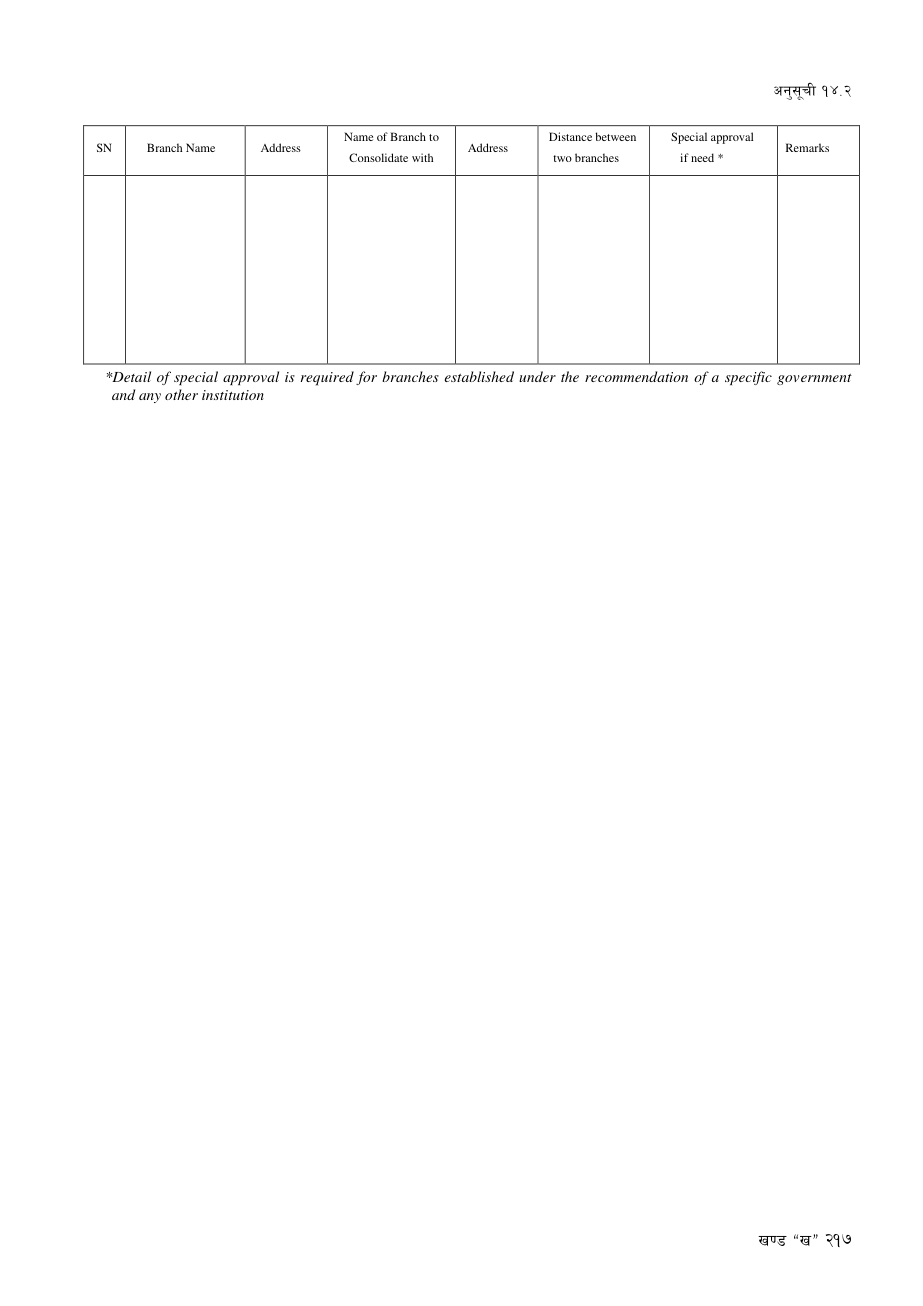
(५) शाखा समायोजन गरेको ३ कार्यदिनभित्र अनुसूची १४.२ बमोजिमको विवरण यस बैंक समक्ष पेश गर्नुपर्नेछ ।
प्रष्टीकरण: समायोजन भन्नाले कुनै इजाजतपत्रप्राप्त संस्थाको दुई वा दुई भन्दा बढी शाखाहरु एक आपसमा गाभिएर एउटा शाखा कायम हुने अवस्था सम्झनु पर्छ ।
(ख) इजाजतपत्रप्राप्त संस्थाले महानगरपालिका, उप-महानगरपालिका र नगरपालिकाको सोही वडाभित्र तथा गाउँपालिकाको हकमा सोही गाउँपालिकाभित्र शाखा कार्यालय स्थानान्तरण गर्नुपरेमा इजाजतपत्रप्राप्त संस्थाको सञ्चालक समितिको निर्णयानुसार स्थानान्तरण गरी ७ दिनभित्र सोको जानकारी यस बैंकलाई दिनुपर्नेछ ।
(ग) इजाजतपत्रप्राप्त संस्थाले केन्द्रीय/रजिष्टर्ड कार्यालय (कर्पोरेट कार्यालय) को ठेगाना परिवर्तन गर्न वा स्थानान्तरण गर्न चाहेमा यस बैंकको स्वीकृति लिई प्रचलित कानुनको अधीनमा रही आफ्नो प्रबन्धपत्र तथा नियमावलीमा संशोधन गरी गर्न सक्नेछन् ।
Controlled English translation
(a) A licensed institution shall not close, relocate or merge a branch or any type of office without prior approval of this Bank.
However, in the following circumstances the licensed institution may, by its own decision, consolidate branches situated within a Metropolitan City:
(1) considering the growth of electronic payment transactions and the significant number of branches, a bank or financial institution may consolidate/integrate its branches within a Metropolitan City;
(2) in the case of a branch established for a Government body or public institution, consolidation may be carried out only after obtaining the written consent of such institution;
(3) at least ten days before branch consolidation, notice shall be published for public information in a national daily newspaper, on the institution’s website and on the notice board of the branch;
(4) where two or more branches are consolidated, arrangements shall be made so that customers of the branches being consolidated may repay their credit or discontinue other services during the period without any charge;
(5) within three working days after consolidation, particulars in the format of Schedule 14.2 shall be submitted to this Bank.
Explanation: “Consolidation” means the situation in which two or more branches of the same licensed institution are merged with one another and one branch remains.
(b) Where a licensed institution relocates a branch office within the same ward of a Metropolitan City, Sub-Metropolitan City or Municipality, or within the same Rural Municipality in the case of a Rural Municipality, it may do so pursuant to a decision of its Board of Directors and shall inform this Bank within seven days.
(c) Where a licensed institution wishes to change or relocate the address of its central/registered office (corporate office), it may do so after obtaining approval of this Bank and amending its memorandum and articles in accordance with prevailing law.
(क) नेपाल राष्ट्र बैंक खुलेको दिन तथा यस बैंकको बैंकिङ कार्यालयले बैंकिङ कारोबार गर्ने समयसम्म इजाजतपत्रप्राप्त संस्थाहरुले अनिवार्य रुपमा आफ्ना कार्यालय खोली बैंकिङ कारोबार सञ्चालन गर्नुपर्नेछ ।
तर, इजाजतपत्रप्राप्त संस्थाहरुले नेपाल राष्ट्र बैंक खुलेको दिन र समयका अतिरिक्त समय तथा अन्य बिदाका दिन र समयमा आफ्नो कारोबार सञ्चालन गर्ने भएमा यस बैंकको बैंक तथा वित्तीय संस्था नियमन विभाग र सम्बन्धित सुपरिवेक्षण विभागमा लिखित रुपमा जानकारी दिनुपर्नेछ ।
(ख) यस बैंकबाट जारी भएको बैंक बिदाको सूचीमा अतिरिक्त नेपाल सरकारबाट आकस्मिक बिदा घोषणा भएको दिन नगद कारोबार, चेक क्लियरिङ, RTGS लगायत अत्यावश्यक बैंकिङ सेवा प्रदान गर्न बिहान १०:०० देखि दिउँसो १:३० बजेसम्म इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाले आवश्यक विभाग तथा कार्यालय खुला राखी सेवा सुचारु गर्ने व्यवस्था मिलाउनु पर्नेछ ।
Controlled English translation
(a) On days Nepal Rastra Bank is open and during the period in which the banking office of this Bank carries out banking transactions, licensed institutions shall mandatorily keep their offices open and conduct banking business.
However, where a licensed institution operates outside the days and times when Nepal Rastra Bank is open or on other holidays, it shall provide written information to the Banks and Financial Institutions Regulation Department of this Bank and the concerned Supervision Department.
(b) In addition to the bank-holiday list issued by this Bank, where the Government of Nepal declares an emergency public holiday, licensed banks and financial institutions shall keep the necessary departments and offices open from 10:00 a.m. to 1:30 p.m. to provide essential banking services including cash transactions, cheque clearing and RTGS.
(क) इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाहरुले काठमाडौं उपत्यका, महानगरपालिका र उप महानगरपालिकामा एक्सटेन्सन काउन्टर खोल्न यस बैंकको स्वीकृति लिनुपर्नेछ ।
(ख) एक्सटेन्सन काउन्टर खोल्नका लागि इजाजतपत्रप्राप्त संस्थाहरुले देहायका शर्तहरु पूरा गरेको हुनुपर्नेछ :-
(अ) यस बैंकले तोकेको न्यूनतम पुँजीकोष अनुपात तथा चुक्ता पुँजी कायम गरेको ।
(आ) यस बैंकबाट तोकिएको ब्याजदर अन्तर कायम गरेको ।
(इ) माथि उल्लिखित शर्त तथा व्यवस्थाहरु पूरा नभएको अवस्थामा इजाजतपत्रप्राप्त संस्थालाई विशेष परिस्थितिमा कुनै स्थानमा एक्सटेन्सन काउन्टर स्थापना गर्न अत्यावश्यक देखिएमा यस बैंकले स्वीकृति दिन सक्नेछ ।
(ग) खण्ड (ख) बमोजिमका शर्तहरु पूरा गरेका इजाजतपत्रप्राप्त संस्थाहरुले काठमाडौं उपत्यका, महानगरपालिका भित्र रहेका अदालत, अस्पताल, सैनिक ब्यारेक, विश्वविद्यालय, क्याम्पस, विद्यालय, सरकारी कार्यालय, औद्योगिक क्षेत्र तथा विदेशी कूटनीतिक नियोगहरुको सिफारिसमा उक्त निकायहरुको हाताभित्र वा अधिकतम २०० मिटरको दुरी सीमाभित्रमा एक्सटेन्सन काउन्टर खोल्नका लागि आवेदन पेश गरेमा आवश्यकताको आधारमा त्यस्तो काउन्टर खोल्न स्वीकृति प्रदान गर्न सकिनेछ ।
(घ) एक्सटेन्सन काउन्टरबाट कोष तथा गैरकोषमा आधारित कर्जा तथा सुविधाहरु सम्बन्धी कार्य गर्न पाइने छैन ।
(ङ) एक्सटेन्सन काउन्टरबाट विदेशी मुद्राको खरिद/बिक्री सम्बन्धी कार्य गर्न चाहेमा यस बैंकको विदेशी विनिमय व्यवस्थापन विभागबाट इजाजतपत्र लिनु पर्नेछ ।
(च) इजाजतपत्रप्राप्त संस्थाले एक्सटेन्सन काउन्टरको हिसाब मिलानको लागि नजिकको शाखा तोक्नु पर्नेछ ।
(छ) एक्सटेन्सन काउन्टर शाखामा परिवर्तन हुने भएमा शाखा स्थापना सम्बन्धी नीतिगत प्रक्रिया पूरा गर्नु पर्नेछ ।
(ज) कुनै सरकारी निकाय मार्फत हुने सरकारी कारोबारलाई लक्षित गरी एक्सटेन्सन काउन्टर स्थापना गर्दा उक्त सरकारी निकाय जुनसुकै तहको पालिकामा अवस्थित भएतापनि यस बैंकको बैंकिङ विभागबाट पूर्व सहमति लिनुपर्नेछ ।
(झ) यस बैंकको मिति २०७४/१२/१४ पत्रसंख्या वै.वि.नि.वि./नीति/परिपत्र/कक्षा/१८/०७४/७५ को परिपत्रमा तोकिएबमोजिमका बैंकिङ सुविधा नपुगेका ११६ स्थानीय तहमा जुन वाणिज्य बैंकले शाखा कार्यालय खोलेको छ सो बाहेक अन्य बैंक/वित्तीय संस्थाले परिपत्रको मितिले तीन वर्षसम्म एक्सटेन्सन काउन्टर खोल्न पाउने छैन ।
Controlled English translation
(a) Licensed banks and financial institutions shall obtain approval of this Bank to open extension counters in Kathmandu Valley, Metropolitan Cities and Sub-Metropolitan Cities.
(b) A licensed institution seeking to open an extension counter shall have fulfilled the following conditions:
(i) maintained the minimum capital-fund ratio and paid-up capital prescribed by this Bank;
(ii) maintained the interest-rate spread prescribed by this Bank;
(iii) where the above conditions are not fulfilled, this Bank may, in special circumstances, grant approval to establish an extension counter at a location where such establishment is considered essential.
(c) A licensed institution fulfilling the conditions under paragraph (b) may be granted approval, on the basis of need, to open an extension counter within the premises, or within a maximum distance of 200 metres, of courts, hospitals, military barracks, universities, campuses, schools, Government offices, industrial areas and foreign diplomatic missions situated within Kathmandu Valley or a Metropolitan City, upon recommendation of the concerned body.
(d) No fund-based or non-fund-based credit/facility business shall be conducted through an extension counter.
(e) Where foreign-currency purchase/sale transactions are to be conducted through an extension counter, a licence shall be obtained from the Foreign Exchange Management Department of this Bank.
(f) A licensed institution shall designate a nearby branch for reconciliation of the accounts of an extension counter.
(g) Where an extension counter is converted into a branch, the policy procedure applicable to branch establishment shall be completed.
(h) Where an extension counter is established for Government transactions conducted through a Government body, prior consent of the Banking Department of this Bank shall be obtained irrespective of the level of local government in which that Government body is situated.
(i) In the 116 local levels without banking facilities identified in this Bank’s Circular No. वै.वि.नि.वि./नीति/परिपत्र/कक्षा/१८/०७४/७५ dated 2074/12/14, no bank/financial institution other than the commercial bank that has opened a branch office there shall be permitted to open an extension counter for three years from the date of the circular.
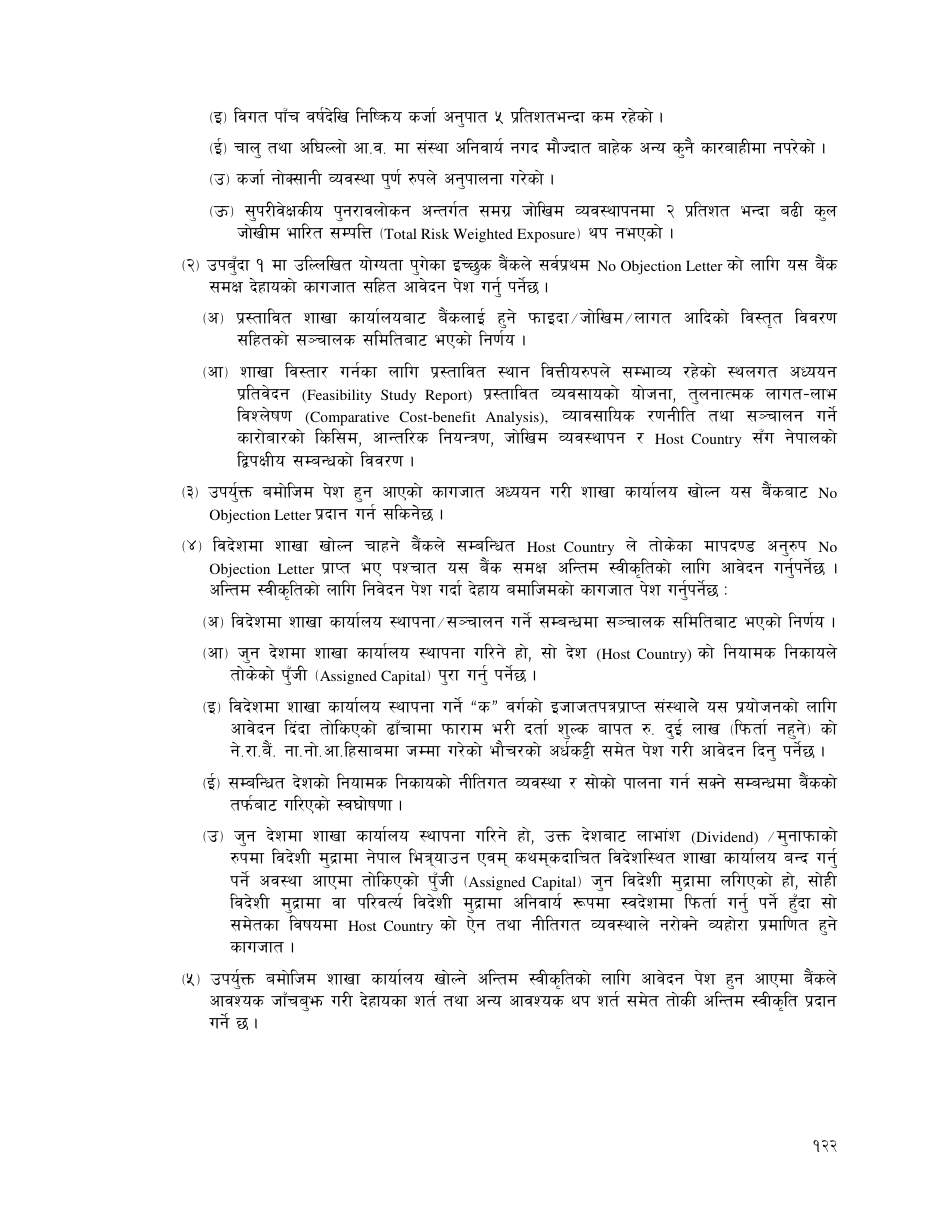
इजाजतपत्रप्राप्त “क” वर्गका वाणिज्य बैंकहरुले निम्नानुसारका शर्त तथा मापदण्डहरुको अधीनमा रही विदेशमा शाखा कार्यालय स्थापना गर्न सक्नेछन् ।
(१) देहायका अवस्था पूरा गरेका “क” वर्गका बैंकहरुले यस बैंकको स्वीकृति लिई विदेशमा शाखा कार्यालय खोल्न सक्ने छन्:
(अ) यस बैंकले तोकेको न्यूनतम चुक्ता पुँजी पुगेको ।
(आ) विगत पाँच वर्षदेखि नियमित रुपमा यस बैंकले तोकेको पुँजीकोष कायम गरेको ।
(इ) विगत पाँच वर्षदेखि निष्क्रिय कर्जा अनुपात ५ प्रतिशतभन्दा कम रहेको ।
(ई) चालु तथा अघिल्लो आ.व. मा संस्थागत अनिवार्य नगद मौज्दात बाहेक अन्य कुनै कारवाहीमा नपरेको ।
(उ) कर्जा नोक्सानी व्यवस्था पूर्ण रुपले अनुपालन गरेको ।
(ऊ) सुपरिवेक्षणीय पुनरावलोकन अन्तर्गत समग्र जोखिम व्यवस्थापनमा २ प्रतिशत भन्दा बढी कुल जोखिम भारित सम्पत्ति (Total Risk Weighted Exposure) थप नभएको ।
(२) उपबुँदा १ मा उल्लिखित योग्यता पुगेका इच्छुक बैंकले सर्वप्रथम No Objection Letter को लागि यस बैंक समक्ष देहायका कागजात सहित आवेदन पेश गर्नु पर्नेछ:
(अ) सञ्चालक समितिको निर्णय ।
(आ) प्रस्तावित शाखा कार्यालयबाट बैंकलाई हुने फाइदा/जोखिम/लागत आदिको विस्तृत विवरण सहितको सञ्चालक समितिबाट भएको निर्णय ।
(इ) शाखा विस्तार गर्नका लागि प्रस्तावित स्थान वित्तीयरुपले सम्भाव्य रहेको स्थलगत अध्ययन प्रतिवेदन (Feasibility Study Report), प्रस्तावित व्यवसायको योजना, तुलनात्मक लागत-लाभ विश्लेषण (Comparative Cost-benefit Analysis), व्यावसायिक रणनीति तथा सञ्चालन गर्ने कारोबारको किसिम, आन्तरिक नियन्त्रण, जोखिम व्यवस्थापन र Host Country सँग नेपालको द्विपक्षीय सम्बन्धको विवरण ।
(३) उपर्युक्त बमोजिम पेश हुन आएको कागजात अध्ययन गरी शाखा कार्यालय खोल्न यस बैंकबाट No Objection Letter प्रदान गर्न सकिनेछ ।
(४) विदेशमा शाखा खोल्न चाहने बैंकले सम्बन्धित Host Country ले तोकेका मापदण्ड अनुरुप No Objection Letter प्राप्त भए पश्चात यस बैंक समक्ष अन्तिम स्वीकृतिको लागि आवेदन गर्नुपर्नेछ । अन्तिम स्वीकृतिको लागि निवेदन पेश गर्दा देहाय बमोजिमको कागजात पेश गर्नुपर्नेछ:
(अ) विदेशमा शाखा कार्यालय स्थापना/सञ्चालन गर्ने सम्बन्धमा सञ्चालक समितिबाट भएको निर्णय ।
(आ) जुन देशमा शाखा कार्यालय स्थापना गरिने हो, सो देश (Host Country) को नियामक निकायले तोकेको पुँजी (Assigned Capital) पूरा गर्नु पर्नेछ ।
(इ) विदेशमा शाखा कार्यालय स्थापना गर्ने “क” वर्गको इजाजतपत्रप्राप्त संस्थाले यस प्रयोजनको लागि आवेदन दिंदा तोकिएको ढाँचामा फाराम भरी तथा शुल्क वापत रु. दुई लाख (फिर्ता नहुने) को ने.रा.बैं. ना.औ.हिसाबमा जम्मा गरेको भौचरको अर्धकट्टी समेत पेश गरी आवेदन दिनु पर्नेछ ।
(ई) सम्बन्धित देशको नियामक निकायको नीतिगत व्यवस्था र सोको पालना गर्न सक्ने सम्बन्धमा बैंकको तर्फबाट गरिएको स्वघोषणा ।
(उ) जुन देशमा शाखा कार्यालय स्थापना गरिने हो, उक्त देशबाट लाभांश (Dividend) मुनाफाको रुपमा विदेशी मुद्रा नेपाल ल्याउन नियमअनुसार रकम फिर्ता गर्नुपर्ने अवस्था आएमा तोकिएको पुँजी (Assigned Capital) जुन विदेशी मुद्रामा लगिएको हो, सोही विदेशी मुद्रामा वा परिवर्त्य विदेशी मुद्रामा अनिवार्य रुपमा स्वदेशमा फिर्ता गर्नु पर्ने हुँदा सो सम्बन्धमा विद्यमान Host Country को ऐन तथा नीति तथा व्यवस्था प्रमाणित हुने कागजात ।
(५) उपर्युक्त बमोजिम शाखा कार्यालय खोल्ने अन्तिम स्वीकृतिको लागि आवेदन पेश हुन आएमा बैंकले आवश्यक जाँचबुझ गरी देहायका शर्त तथा अन्य आवश्यक थप शर्त समेत तोकी अन्तिम स्वीकृति प्रदान गर्नेछ ।
Controlled English translation
Class “A” commercial banks licensed by this Bank may establish branch offices abroad subject to the following conditions and standards.
(1) A Class “A” bank satisfying the following conditions may, with approval of this Bank, open a branch office abroad:
(i) the minimum paid-up capital prescribed by this Bank has been met;
(ii) the capital fund prescribed by this Bank has been maintained regularly for the last five years;
(iii) the non-performing loan ratio has remained below 5 percent for the last five years;
(iv) during the current and immediately preceding fiscal year, the institution has not been subject to any action other than in relation to compulsory cash reserve;
(v) loan-loss provisioning requirements have been fully complied with;
(vi) under supervisory review, no additional Total Risk Weighted Exposure exceeding 2 percent has been imposed in relation to overall risk management.
(2) An interested bank meeting the qualifications under sub-clause (1) shall first apply to this Bank for a No Objection Letter together with:
(a) the decision of the Board of Directors;
(b) the Board decision together with detailed information on the benefits/risks/costs to the bank from the proposed branch office;
(c) a Feasibility Study Report showing financial viability of the proposed location, the proposed business plan, Comparative Cost-benefit Analysis, business strategy and types of transactions to be conducted, internal controls, risk management and details of the bilateral relationship between Nepal and the Host Country.
(3) After reviewing the documents submitted as above, this Bank may issue a No Objection Letter for opening the branch office.
(4) A bank wishing to open a branch abroad shall, after obtaining the No Objection Letter in accordance with the standards of the concerned Host Country, apply to this Bank for final approval. The following documents shall be submitted with the application for final approval:
(a) decision of the Board of Directors concerning establishment/operation of the branch abroad;
(b) evidence that the Assigned Capital prescribed by the regulator of the Host Country in which the branch is to be established has been fulfilled;
(c) the prescribed application form and the counterfoil of a voucher evidencing deposit in the specified Nepal Rastra Bank account of a non-refundable fee of NPR 200,000;
(d) self-declaration by the bank concerning the policy requirements of the regulator of the concerned country and the bank’s ability to comply with them;
(e) documentary evidence of the existing law, policy and arrangements of the Host Country concerning repatriation to Nepal, in the same foreign currency or a convertible foreign currency, of the Assigned Capital taken abroad where repatriation is required, and remittance to Nepal of dividends/profits in foreign currency.
(5) Upon receipt of an application for final approval to open a branch office as above, this Bank shall make necessary inquiries and may grant final approval subject to the following conditions and any additional conditions considered necessary.
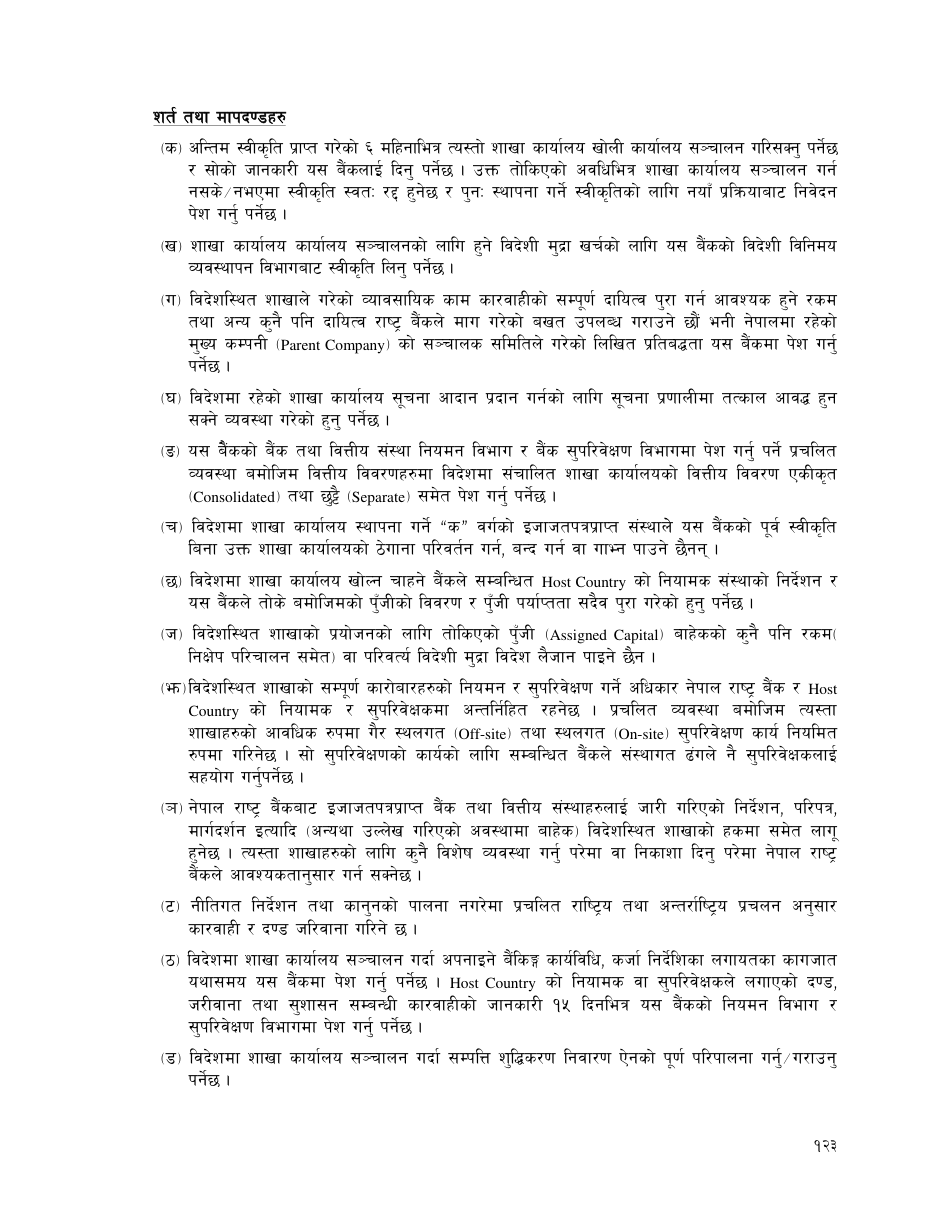
(क) अन्तिम स्वीकृति प्राप्त गरेको ६ महिनाभित्र त्यस्तो शाखा कार्यालय खोली कार्यालय सञ्चालन गरिसक्नु पर्नेछ र सोको जानकारी यस बैंकलाई दिनु पर्नेछ । उक्त तोकिएको अवधिभित्र शाखा कार्यालय सञ्चालन गर्न नसकेको/नगरेमा स्वीकृति स्वतः रद्द हुनेछ र पुनः स्थापना गर्ने स्वीकृतिको लागि नयाँ प्रक्रियाबाट निवेदन पेश गर्नु पर्नेछ ।
(ख) शाखा कार्यालय सञ्चालनका लागि हुने विदेशी मुद्रा खर्चको लागि यस बैंकको विदेशी विनिमय व्यवस्थापन विभागबाट स्वीकृति लिनु पर्नेछ ।
(ग) विदेशस्थित शाखाले गरेको व्यावसायिक काम कारवाहीको सम्पूर्ण दायित्व पूरा गर्न आवश्यक हुने रकम तथा अन्य कुनै पनि दायित्व राष्ट्र बैंकले माग गरेको बखत उपलब्ध गराउनेछौं भनी नेपालमा रहेको मुख्य कम्पनी (Parent Company) को सञ्चालक समितिले गरेको लिखित प्रतिबद्धता यस बैंकमा पेश गर्नु पर्नेछ ।
(घ) विदेशमा रहेको शाखा कार्यालयमा सूचना आदान प्रदान गर्नको लागि सूचना प्रणालीमा तत्काल आवद्ध हुन सक्ने व्यवस्था गरेको हुनु पर्नेछ ।
(ङ) यस बैंकको बैंक तथा वित्तीय संस्था नियमन विभाग र बैंक सुपरिवेक्षण विभागमा पेश गर्नु पर्ने प्रचलित व्यवस्था बमोजिम वित्तीय विवरणहरुमा विदेशमा सञ्चालित शाखा कार्यालयको वित्तीय विवरणहरु एकीकृत (Consolidated) तथा छुट्टै (Separate) समेत पेश गर्नु पर्नेछ ।
(च) विदेशमा शाखा कार्यालय स्थापना गर्ने “क” वर्गको इजाजतपत्रप्राप्त संस्थाले यस बैंकको पूर्व स्वीकृति बिना उक्त शाखा कार्यालयको ठेगाना परिवर्तन गर्न, बन्द गर्न वा गाभ्न पाउने छैन ।
(छ) विदेशमा शाखा कार्यालय खोल्न चाहने बैंकले सम्बन्धित Host Country को नियामक संस्थाको निर्देशन र यस बैंकले तोके बमोजिमको पुँजीकोष विवरण र पुँजी पर्याप्तता सम्बन्धी पूरा गरेको हुनु पर्नेछ ।
(ज) विदेशस्थित शाखाको प्रयोजनको लागि तोकिएको पुँजी (Assigned Capital) बाहेकको कुनै पनि रकम (निक्षेप परिचालन समेत) वा परिवर्त्य विदेशी मुद्रा विदेश लैजान पाइने छैन ।
(झ) विदेशस्थित शाखाको सम्पूर्ण कारोबारहरुको नियमन र सुपरिवेक्षण गर्ने अधिकार नेपाल राष्ट्र बैंक र Host Country को नियामक र सुपरिवेक्षकमा अन्तर्निहित रहनेछ । प्रचलित व्यवस्था बमोजिम त्यस्ता शाखाहरुको आवधिक रुपमा गैर-स्थलगत (Off-site) तथा स्थलगत (On-site) सुपरिवेक्षण कार्य नियमित रुपमा गरिनेछ । सो सुपरिवेक्षणको कार्यको लागि सम्बन्धित बैंकले राष्ट्र बैंकबाट खटिने सुपरिवेक्षकलाई सहयोग गर्नु पर्नेछ ।
(ञ) नेपाल राष्ट्र बैंकबाट इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाहरुलाई जारी गरिएको निर्देशन, परिपत्र, मार्गदर्शन इत्यादि (अन्यथा उल्लेख गरिएको अवस्थामा बाहेक) विदेशस्थित शाखाको हकमा समेत लागू हुनेछ । त्यस्ता शाखाहरुको लागि कुनै विशेष व्यवस्था गर्नु परेमा वा निकायमा दिनु परेमा नेपाल राष्ट्र बैंकले आवश्यकतानुसार गर्न सक्नेछ ।
(ट) नीतिगत निर्देशन तथा कानुनको पालना नगरेमा प्रचलित राष्ट्रिय तथा अन्तर्राष्ट्रिय प्रचलन अनुसार कारवाही र दण्ड जरिवाना गरिने छ ।
(ठ) विदेशमा शाखा कार्यालय सञ्चालन गर्दा अपनाउने बैंकिङ कार्यविधि, कर्जा निर्देशिका लगायतका कागजात यथासम्भव यस बैंकमा पेश गर्नु पर्नेछ । Host Country को नियामक वा सुपरिवेक्षकले लगाएको दण्ड, जरिवाना तथा सुशासन सम्बन्धी कारवाहीको जानकारी १५ दिनभित्र यस बैंकको नियमन विभाग र सुपरिवेक्षण विभागमा पेश गर्नु पर्नेछ ।
(ड) विदेशमा शाखा कार्यालय सञ्चालन गर्दा सम्पत्ति शुद्धीकरण निवारण ऐनको पूर्ण परिपालना गर्नु/गराउनु पर्नेछ ।
Controlled English translation
(a) Within six months after receiving final approval, the branch office shall be opened and brought into operation and this Bank shall be informed. If the branch office cannot be or is not brought into operation within the prescribed period, the approval shall automatically lapse and a fresh application shall be required under a new process.
(b) Approval of the Foreign Exchange Management Department of this Bank shall be obtained for foreign-currency expenditure required for operating the branch office.
(c) A written undertaking of the Board of Directors of the Parent Company in Nepal shall be submitted to this Bank stating that it will make available, when required by Nepal Rastra Bank, funds necessary to meet all liabilities arising from business conducted by the overseas branch and any other liabilities.
(d) Arrangements shall have been made for immediate connection of the overseas branch office to the information system for exchange of information.
(e) In the financial statements required to be submitted under prevailing arrangements to the Banks and Financial Institutions Regulation Department and Bank Supervision Department of this Bank, the financial statements of the overseas branch shall be submitted both on a Consolidated and Separate basis.
(f) A Class “A” licensed institution establishing an overseas branch shall not change the address, close or merge such branch without prior approval of this Bank.
(g) The bank shall comply with the capital-fund statement and capital-adequacy requirements prescribed by the regulator of the Host Country and by this Bank.
(h) Except for Assigned Capital designated for the overseas branch, no other funds, including mobilised deposits, or convertible foreign currency shall be transferred abroad for the branch.
(i) Authority to regulate and supervise all transactions of the overseas branch shall vest in Nepal Rastra Bank and the regulator/supervisor of the Host Country. Such branch shall be subject to regular periodic Off-site and On-site supervision under prevailing arrangements. The concerned bank shall assist supervisors deputed by Nepal Rastra Bank.
(j) Directives, circulars, guidelines and similar instruments issued by Nepal Rastra Bank to licensed banks and financial institutions shall, unless otherwise expressly stated, also apply to overseas branches. Nepal Rastra Bank may make special arrangements for such branches as necessary.
(k) Failure to comply with policy directives and law shall result in action and penalties in accordance with prevailing national and international practice.
(l) The bank shall, as far as possible, submit to this Bank banking procedures, credit directives and other documents used in operating the overseas branch. Information regarding any fine, penalty or governance-related action imposed by the regulator or supervisor of the Host Country shall be submitted within 15 days to this Bank’s Regulation Department and Supervision Department.
(m) In operating an overseas branch, full compliance with the Asset (Money) Laundering Prevention Act shall be ensured.
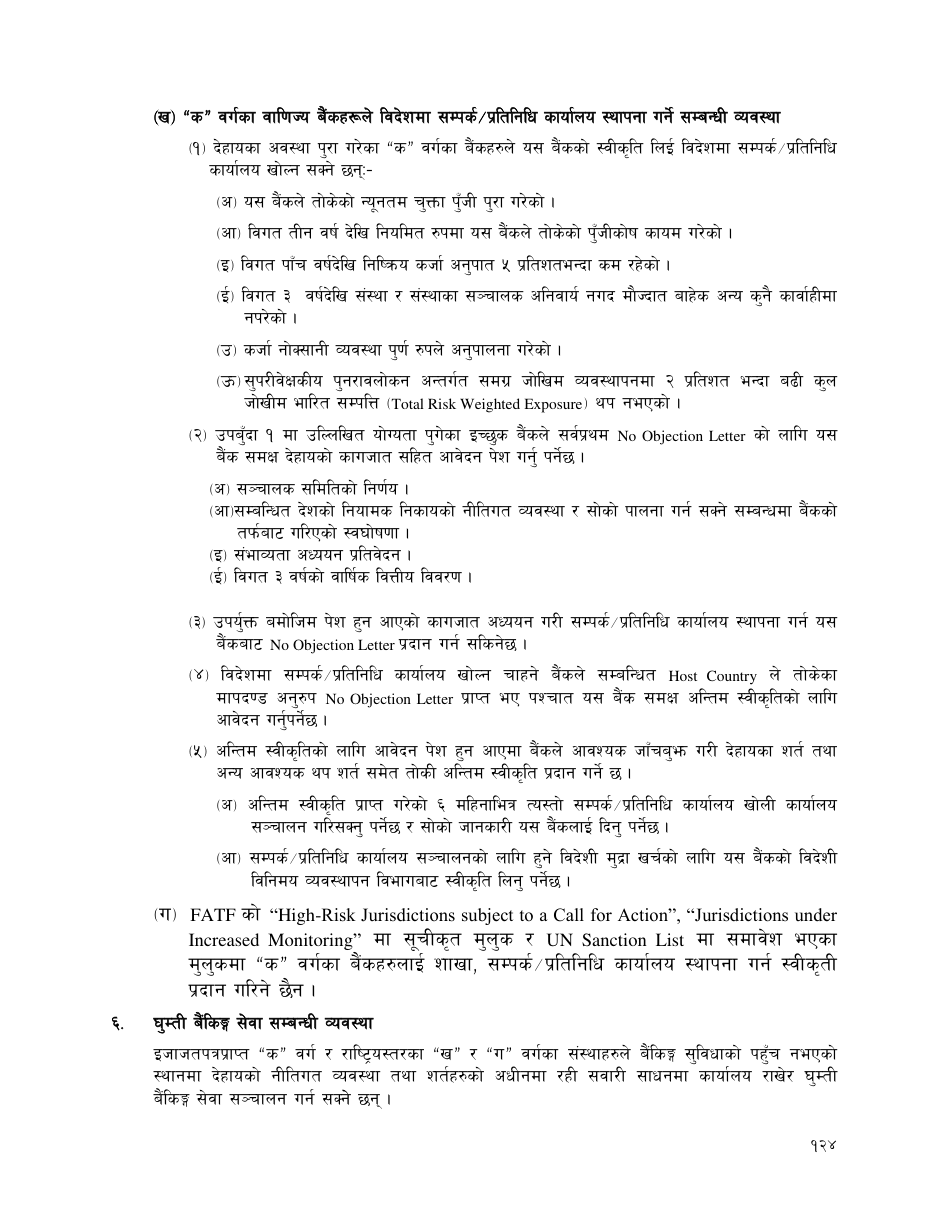
(१) देहायका अवस्था पूरा गरेका “क” वर्गका बैंकहरुले यस बैंकको स्वीकृति लिई विदेशमा सम्पर्क/प्रतिनिधि कार्यालय खोल्न सक्ने छन् :-
(अ) यस बैंकले तोकेको न्यूनतम चुक्ता पुँजी पूरा गरेको ।
(आ) विगत तीन वर्ष देखि नियमित रुपमा यस बैंकले तोकेको पुँजीकोष कायम गरेको ।
(इ) विगत पाँच वर्षदेखि निष्क्रिय कर्जा अनुपात ५ प्रतिशतभन्दा कम रहेको ।
(ई) विगत ३ वर्षदेखि संस्था र संस्थाका सञ्चालक अनिवार्य नगद मौज्दात बाहेक अन्य कुनै कारवाहीमा नपरेको ।
(उ) कर्जा नोक्सानी व्यवस्था पूर्ण रुपले अनुपालन गरेको ।
(ऊ) सुपरिवेक्षणीय पुनरावलोकन अन्तर्गत समग्र जोखिम व्यवस्थापनमा २ प्रतिशत भन्दा बढी कुल जोखिम भारित सम्पत्ति (Total Risk Weighted Exposure) थप नभएको ।
(२) उपबुँदा १ मा उल्लिखित योग्यता पुगेका इच्छुक बैंकले सर्वप्रथम No Objection Letter को लागि यस बैंक समक्ष देहायका कागजात सहित आवेदन पेश गर्नु पर्नेछ:
(अ) सञ्चालक समितिको निर्णय ।
(आ) सम्बन्धित देशको नियामक निकायको नीतिगत व्यवस्था र सोको पालना गर्न सक्ने सम्बन्धमा बैंकको तर्फबाट गरिएको स्वघोषणा ।
(इ) सम्भाव्यता अध्ययन प्रतिवेदन ।
(ई) विगत ३ वर्षको वार्षिक वित्तीय विवरण ।
(३) उपर्युक्त बमोजिम पेश हुन आएको कागजात अध्ययन गरी सम्पर्क/प्रतिनिधि कार्यालय स्थापना गर्न यस बैंकबाट No Objection Letter प्रदान गर्न सकिनेछ ।
(४) विदेशमा सम्पर्क/प्रतिनिधि कार्यालय खोल्न चाहने बैंकले सम्बन्धित Host Country ले तोकेका मापदण्ड अनुरुप No Objection Letter प्राप्त भए पश्चात यस बैंक समक्ष अन्तिम स्वीकृतिको लागि आवेदन गर्नुपर्नेछ ।
(५) अन्तिम स्वीकृतिको लागि आवेदन पेश हुन आएमा बैंकले आवश्यक जाँचबुझ गरी देहायका शर्त तथा अन्य आवश्यक थप शर्त समेत तोकी अन्तिम स्वीकृति प्रदान गर्ने छ ।
(अ) अन्तिम स्वीकृति प्राप्त गरेको ६ महिनाभित्र त्यस्तो सम्पर्क/प्रतिनिधि कार्यालय खोली कार्यालय सञ्चालन गरिसक्नु पर्नेछ र सोको जानकारी यस बैंकलाई दिनु पर्नेछ ।
(आ) सम्पर्क/प्रतिनिधि कार्यालय सञ्चालनका लागि हुने विदेशी मुद्रा खर्चको लागि यस बैंकको विदेशी विनिमय व्यवस्थापन विभागबाट स्वीकृति लिनु पर्नेछ ।
(ग) FATF को “High-Risk Jurisdictions subject to a Call for Action”, “Jurisdictions under Increased Monitoring” मा सूचीकृत मुलुक र UN Sanction List मा समावेश भएका मुलुकमा “क” वर्गका बैंकहरुलाई शाखा, सम्पर्क/प्रतिनिधि कार्यालय स्थापना गर्न स्वीकृति प्रदान गरिने छैन ।
Controlled English translation
(1) A Class “A” bank satisfying the following conditions may, with approval of this Bank, open a contact/representative office abroad:
(i) the minimum paid-up capital prescribed by this Bank has been fulfilled;
(ii) the capital fund prescribed by this Bank has been maintained regularly for the last three years;
(iii) the non-performing loan ratio has remained below 5 percent for the last five years;
(iv) during the last three years, neither the institution nor its directors has been subject to any action other than in relation to compulsory cash reserve;
(v) loan-loss provisioning requirements have been fully complied with;
(vi) under supervisory review, no additional Total Risk Weighted Exposure exceeding 2 percent has been imposed in relation to overall risk management.
(2) An interested bank meeting the qualifications under sub-clause (1) shall first apply to this Bank for a No Objection Letter together with:
(a) the decision of the Board of Directors;
(b) self-declaration by the bank concerning the policy arrangements of the regulator of the concerned country and the bank’s ability to comply;
(c) feasibility study report;
(d) annual financial statements for the previous three years.
(3) After reviewing the documents submitted as above, this Bank may issue a No Objection Letter for establishment of the contact/representative office.
(4) A bank wishing to open a contact/representative office abroad shall, after obtaining the No Objection Letter in accordance with the standards of the Host Country, apply to this Bank for final approval.
(5) Upon receipt of an application for final approval, this Bank shall make necessary inquiries and may grant final approval subject to the following conditions and any additional conditions considered necessary:
(a) within six months after receiving final approval, the contact/representative office shall be opened and brought into operation and this Bank shall be informed;
(b) approval of the Foreign Exchange Management Department of this Bank shall be obtained for foreign-currency expenditure required to operate the contact/representative office.
(c) Class “A” banks shall not be granted approval to establish a branch, contact office or representative office in countries listed by FATF as “High-Risk Jurisdictions subject to a Call for Action” or “Jurisdictions under Increased Monitoring”, or in countries included in the UN Sanction List.
इजाजतपत्रप्राप्त “क” वर्ग र राष्ट्रियस्तरका “ख” र “ग” वर्गका संस्थाहरुले बैंकिङ सुविधाको पहुँच नपुगेको स्थानमा देहायको नीतिगत व्यवस्था तथा शर्तहरुको अधीनमा रही सवारी साधनमा कार्यालय राखेर घुम्ती बैंकिङ सेवा सञ्चालन गर्न सक्ने छन् ।
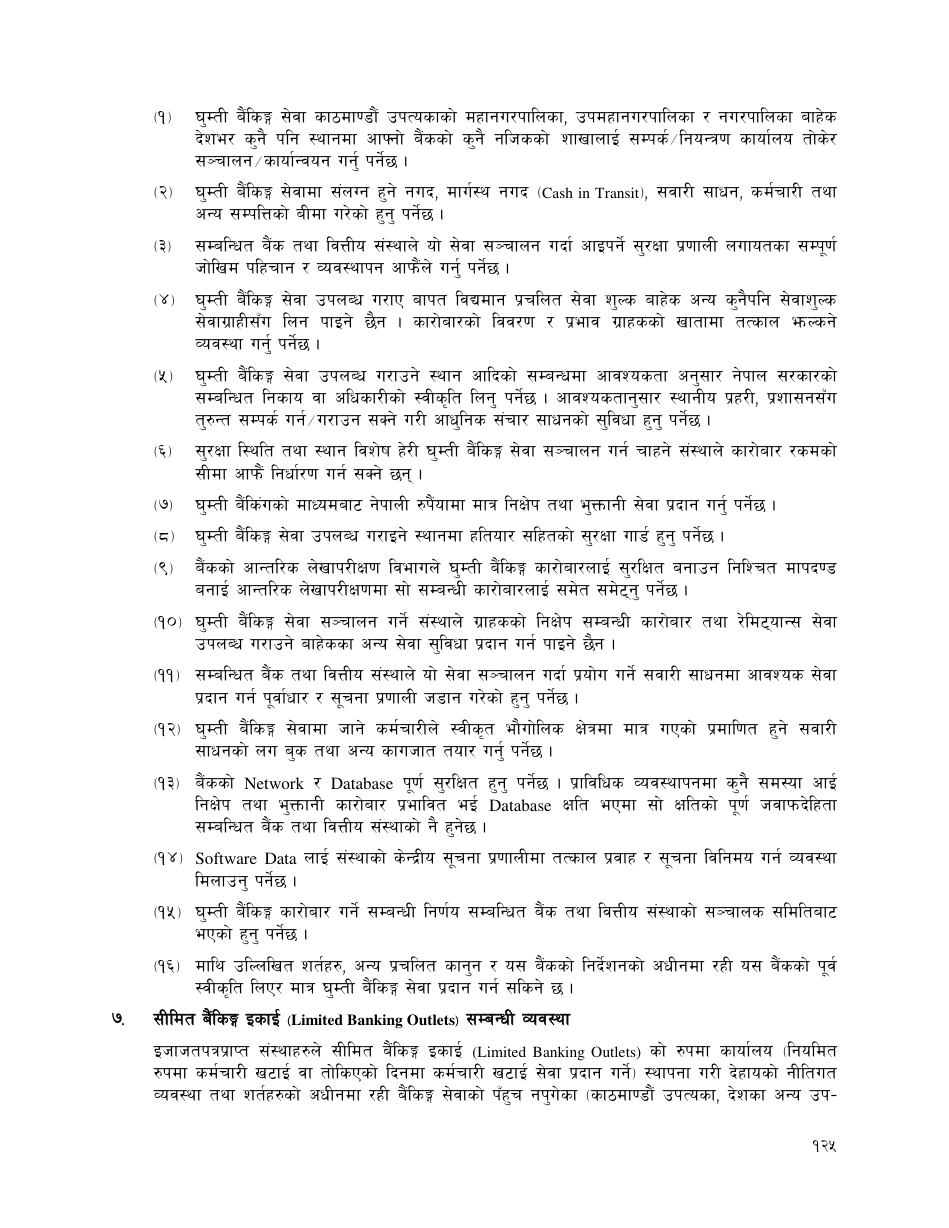
(१) घुम्ती बैंकिङ सेवा काठमाडौं उपत्यकाको महानगरपालिका, उपमहानगरपालिका र नगरपालिका बाहेक देशभर कुनै पनि स्थानमा आफ्नो बैंकको कुनै नजिकको शाखालाई सम्पर्क/नियन्त्रण कार्यालय तोकेर सञ्चालन/कार्यान्वयन गर्नु पर्नेछ ।
(२) घुम्ती बैंकिङ सेवामा संलग्न हुने नगद, मार्गस्थ नगद (Cash in Transit), सवारी साधन, कर्मचारी तथा अन्य सम्पत्तिको बीमा गरेको हुनुपर्नेछ ।
(३) सम्बन्धित बैंक तथा वित्तीय संस्थाले यो सेवा सञ्चालन गर्दा आइपर्ने सुरक्षा प्रणाली लगायतका सम्पूर्ण जोखिम पहिचान र व्यवस्थापन आफैले गर्नु पर्नेछ ।
(४) घुम्ती बैंकिङ सेवा उपलब्ध गराए वापत विद्यमान प्रचलित सेवा शुल्क बाहेक अन्य कुनैपनि सेवाशुल्क सेवाग्राहीसँग लिन पाइने छैन । कारोबारको विवरण र प्रभाव ग्राहकको खातामा तत्काल झल्कने व्यवस्था गर्नु पर्नेछ ।
(५) घुम्ती बैंकिङ सेवा उपलब्ध गराउने स्थान आदिको सम्बन्धमा आवश्यकतानुसार नेपाल सरकारको सम्बन्धित निकाय वा अधिकारीको स्वीकृति लिनु पर्नेछ । आवश्यकतानुसार स्थानीय प्रहरी, प्रशासनसँग तुरुन्त सम्पर्क गर्न/गराउन सक्ने गरी आधुनिक सञ्चार साधनको सुविधा हुनु पर्नेछ ।
(६) सुरक्षा स्थिति तथा स्थान विशेष हेरी घुम्ती बैंकिङ सेवा सञ्चालन गर्न चाहने संस्थाले कारोबार रकमको सीमा आफैले निर्धारण गर्न सक्नेछ ।
(७) घुम्ती बैंकिङको माध्यमबाट नेपाली रुपैयाँमा मात्र निक्षेप तथा भुक्तानी सेवा प्रदान गर्नु पर्नेछ ।
(८) घुम्ती बैंकिङ सेवा उपलब्ध गराइने स्थानमा हतियार सहितको सुरक्षा गार्ड हुनु पर्नेछ ।
(९) बैंकको आन्तरिक लेखापरीक्षण विभागले घुम्ती बैंकिङ कारोबारलाई सुरक्षित बनाउन निश्चित मापदण्ड बनाई आन्तरिक लेखापरीक्षणमा सो सम्बन्धी कारोबारलाई समेत समेट्नु पर्नेछ ।
(१०) घुम्ती बैंकिङ सेवा सञ्चालन गर्ने संस्थाले ग्राहकको निक्षेप सम्बन्धी कारोबार तथा रेमिट्यान्स सेवा उपलब्ध गराउने बाहेकका अन्य सेवा सुविधा प्रदान गर्न पाइने छैन ।
(११) सम्बन्धित बैंक तथा वित्तीय संस्थाले यो सेवा सञ्चालन गर्दा प्रयोग गर्ने सवारी साधनमा आवश्यक सेवा प्रदान गर्न पर्याप्त र सूचना प्रणाली जडान गरेको हुनु पर्नेछ ।
(१२) घुम्ती बैंकिङ सेवामा जाने कर्मचारीले स्वीकृत भौगोलिक क्षेत्रमा मात्र गएको प्रमाणित हुने सवारी साधनको लग बुक तथा अन्य कागजात तयार गर्नु पर्नेछ ।
(१३) बैंकको Network र Database पूर्ण सुरक्षित हुनु पर्नेछ । प्राविधिक व्यवस्थापनमा कुनै समस्या आई निक्षेप तथा भुक्तानी कारोबार प्रभावित भई Database क्षति भएमा सो क्षतिको पूर्ण जवाफदेहिता सम्बन्धित बैंक तथा वित्तीय संस्थाको नै हुनेछ ।
(१४) Software Data लाई संस्थाको केन्द्रीय सूचना प्रणालीमा तत्काल प्रवाह र सूचना विनिमय गर्न व्यवस्था मिलाउनु पर्नेछ ।
(१५) घुम्ती बैंकिङ कारोबार गर्ने सम्बन्धी निर्णय सम्बन्धित बैंक तथा वित्तीय संस्थाको सञ्चालक समितिबाट भएको हुनु पर्नेछ ।
(१६) माथि उल्लिखित शर्तहरु, अन्य प्रचलित कानुन र यस बैंकको निर्देशनको अधीनमा रही यस बैंकको पूर्व स्वीकृति लिएर मात्र घुम्ती बैंकिङ सेवा प्रदान गर्न सकिने छ ।
Controlled English translation
Class “A” institutions and national-level Class “B” and “C” institutions may operate mobile banking service, by maintaining an office in a vehicle, in areas without access to banking facilities, subject to the following policy arrangements and conditions:
(1) Mobile banking service shall be operated/implemented throughout the country outside the Metropolitan City, Sub-Metropolitan City and Municipalities of Kathmandu Valley by designating a nearby branch of the bank as the contact/control office.
(2) Cash, Cash in Transit, the vehicle, employees and other assets involved in mobile banking service shall be insured.
(3) The concerned bank or financial institution shall itself identify and manage all risks, including security-system risks, arising in operating the service.
(4) No service charge other than prevailing approved service charges shall be collected from customers for mobile banking service. Transaction details and effects shall be reflected immediately in the customer’s account.
(5) Approval of the concerned Government body or authority shall be obtained as necessary in relation to locations where mobile banking service is provided. Modern communication facilities shall be available to enable immediate contact with local police/administration as necessary.
(6) Depending on security conditions and the particular location, the institution operating mobile banking service may itself determine transaction limits.
(7) Only deposit and payment services in Nepali Rupees shall be provided through mobile banking.
(8) An armed security guard shall be present at locations where mobile banking service is provided.
(9) The bank’s internal audit department shall establish standards to ensure the security of mobile banking transactions and include such transactions in internal audit.
(10) An institution operating mobile banking service shall not provide services other than customer deposit transactions and remittance services.
(11) The vehicle used to operate the service shall have sufficient facilities and an information system installed to provide the required services.
(12) Employees deployed for mobile banking shall maintain a vehicle log book and other documents proving that travel was made only within the approved geographic area.
(13) The bank’s Network and Database shall be fully secure. If a technical problem affects deposit/payment transactions and damages the Database, the concerned bank or financial institution shall bear full responsibility for the loss.
(14) Arrangements shall be made for immediate transfer of Software Data to the institution’s central information system and for exchange of information.
(15) The decision to conduct mobile banking transactions shall have been made by the Board of Directors of the concerned bank or financial institution.
(16) Mobile banking service may be provided only after obtaining prior approval of this Bank and subject to the above conditions, other prevailing law and the directives of this Bank.
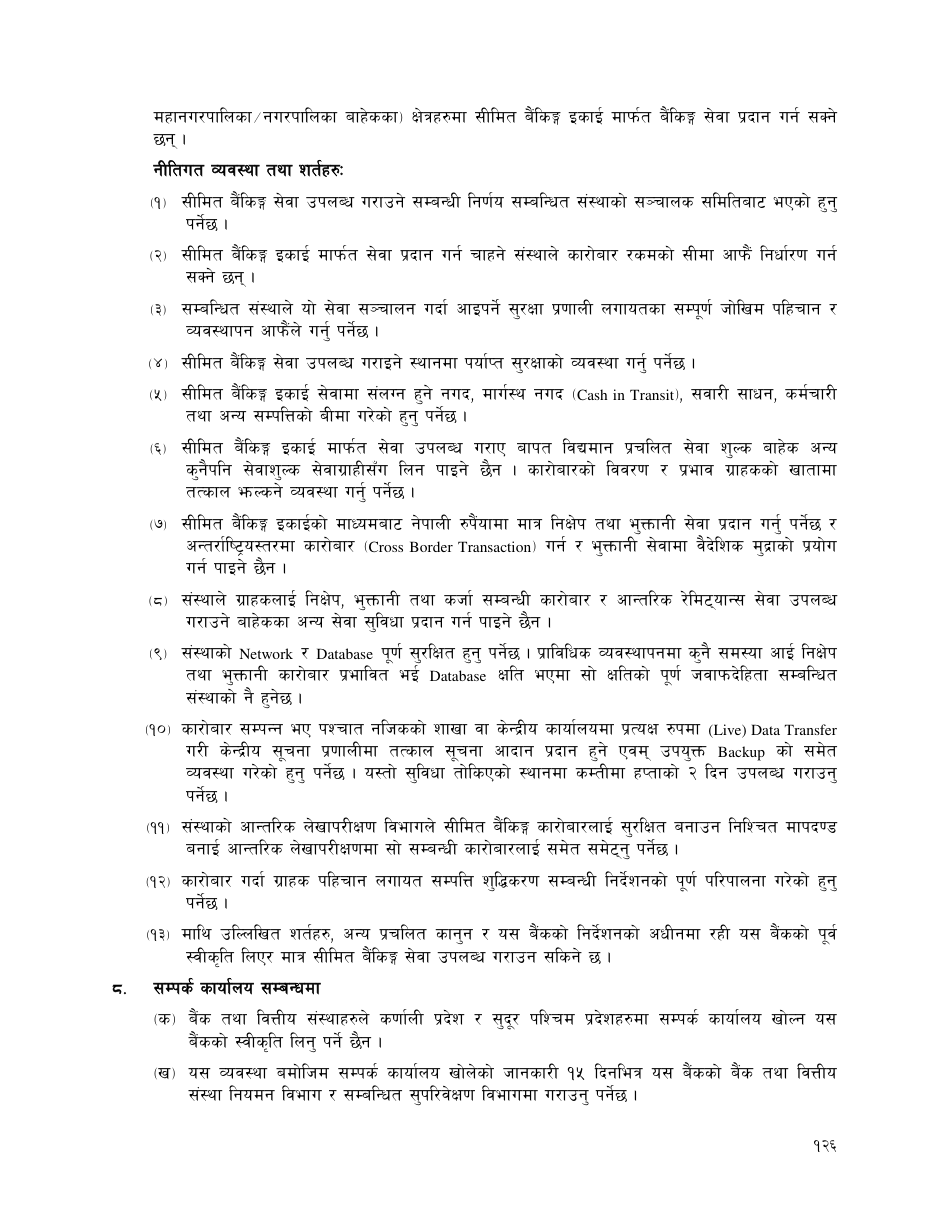
इजाजतपत्रप्राप्त संस्थाहरुले सीमित बैंकिङ इकाई (Limited Banking Outlets) को रुपमा कार्यालय (नियमित रुपमा कर्मचारी खटाई वा तोकिएको दिनमा कर्मचारी खटाई सेवा प्रदान गर्ने) स्थापना गरी देहायको नीतिगत व्यवस्था तथा शर्तहरुको अधीनमा रही बैंकिङ सेवाको पहुँच नपुगेका (काठमाडौं उपत्यका, देशका अन्य उप-महानगरपालिका/नगरपालिका बाहेकका) क्षेत्रहरुमा सीमित बैंकिङ इकाई मार्फत बैंकिङ सेवा प्रदान गर्न सक्ने छन् ।
नीतिगत व्यवस्था तथा शर्तहरु:
(१) सीमित बैंकिङ सेवा उपलब्ध गराउने सम्बन्धी निर्णय सम्बन्धित संस्थाको सञ्चालक समितिबाट भएको हुनु पर्नेछ ।
(२) सीमित बैंकिङ इकाई मार्फत सेवा प्रदान गर्न चाहने संस्थाले कारोबार रकमको सीमा आफैले निर्धारण गर्न सक्नेछ ।
(३) सम्बन्धित संस्थाले यो सेवा सञ्चालन गर्दा आइपर्ने सुरक्षा प्रणाली लगायतका सम्पूर्ण जोखिम पहिचान र व्यवस्थापन आफैले गर्नु पर्नेछ ।
(४) सीमित बैंकिङ सेवा उपलब्ध गराइने स्थानमा पर्याप्त सुरक्षाको व्यवस्था गर्नु पर्नेछ ।
(५) सीमित बैंकिङ इकाई सेवामा संलग्न हुने नगद, मार्गस्थ नगद (Cash in Transit), सवारी साधन, कर्मचारी तथा अन्य सम्पत्तिको बीमा गरेको हुनु पर्नेछ ।
(६) सीमित बैंकिङ इकाई मार्फत नेपाल उपलब्ध गराए वापत विद्यमान प्रचलित सेवा शुल्क बाहेक अन्य कुनैपनि सेवाशुल्क सेवाग्राहीसँग लिन पाइने छैन । कारोबारको विवरण र प्रभाव ग्राहकको खातामा तत्काल झल्कने व्यवस्था गर्नु पर्नेछ ।
(७) सीमित बैंकिङ इकाईको माध्यमबाट नेपाली रुपैयाँमा मात्र निक्षेप तथा भुक्तानी सेवा प्रदान गर्नु पर्नेछ र अन्तर्राष्ट्रियस्तरमा कारोबार (Cross Border Transaction) गर्न र भुक्तानी सेवामा वैदेशिक मुद्राको प्रयोग गर्न पाइने छैन ।
(८) संस्थाले ग्राहकलाई निक्षेप, भुक्तानी तथा कर्जा सम्बन्धी कारोबार र आन्तरिक रेमिट्यान्स सेवा उपलब्ध गराउने बाहेकका अन्य सेवा सुविधा प्रदान गर्न पाइने छैन ।
(९) संस्थाको Network र Database पूर्ण सुरक्षित हुनु पर्नेछ । प्राविधिक व्यवस्थापनमा कुनै समस्या आई निक्षेप तथा भुक्तानी कारोबार प्रभावित भई Database क्षति भएमा सो क्षतिको पूर्ण जवाफदेहिता सम्बन्धित संस्थाको नै हुनेछ ।
(१०) कारोबार सम्पन्न भए पश्चात् नजिकको शाखा वा केन्द्रीय कार्यालयमा प्रत्यक्ष रुपमा (Live) Data Transfer गरी केन्द्रीय सूचना प्रणालीमा तत्काल सूचना आदान प्रदान हुने एवम् उपयुक्त Backup को समेत व्यवस्था गरेको हुनु पर्नेछ । यस्तो सुविधा तोकिएको स्थानमा कम्तीमा हप्ताको २ दिन उपलब्ध गराउनु पर्नेछ ।
(११) संस्थाको आन्तरिक लेखापरीक्षण विभागले सीमित बैंकिङ कारोबारलाई सुरक्षित बनाउन निश्चित मापदण्ड बनाई आन्तरिक लेखापरीक्षणमा सो सम्बन्धी कारोबारलाई समेत समेट्नु पर्नेछ ।
(१२) कारोबार गर्दा ग्राहक पहिचान लगायत सम्पत्ति शुद्धीकरण सम्बन्धी निर्देशनको पूर्ण परिपालना गरेको हुनु पर्नेछ ।
(१३) माथि उल्लिखित शर्तहरु, अन्य प्रचलित कानुन र यस बैंकको निर्देशनको अधीनमा रही यस बैंकको पूर्व स्वीकृति लिएर मात्र सीमित बैंकिङ सेवा उपलब्ध गराउन सकिने छ ।
Controlled English translation
Licensed institutions may establish offices as Limited Banking Outlets (staffed regularly or on specified days) and provide banking services through such outlets in areas without access to banking services (excluding Kathmandu Valley and other Sub-Metropolitan Cities/Municipalities), subject to the following policy arrangements and conditions:
(1) The decision to provide limited banking service shall have been made by the Board of Directors of the concerned institution.
(2) An institution wishing to provide service through a Limited Banking Outlet may itself determine transaction limits.
(3) The concerned institution shall itself identify and manage all risks, including security-system risks, arising in operating the service.
(4) Adequate security arrangements shall be made at the location where limited banking service is provided.
(5) Cash, Cash in Transit, vehicles, employees and other assets involved in the Limited Banking Outlet service shall be insured.
(6) No service charge other than prevailing approved service charges shall be collected from customers for service through a Limited Banking Outlet. Transaction details and effects shall be reflected immediately in the customer’s account.
(7) Only deposit and payment services in Nepali Rupees shall be provided through a Limited Banking Outlet; Cross Border Transactions and use of foreign currency in payment services shall not be permitted.
(8) The institution shall not provide services other than customer deposit, payment and credit transactions and domestic remittance services.
(9) The institution’s Network and Database shall be fully secure. If a technical problem affects deposit/payment transactions and damages the Database, the concerned institution shall bear full responsibility for the loss.
(10) After completion of a transaction, Live Data Transfer shall be made to the nearest branch or central office so that information is immediately exchanged with the central information system, and appropriate Backup shall also be maintained. Such facility shall be provided at the designated location at least two days each week.
(11) The internal audit department shall establish standards to ensure the security of limited banking transactions and include such transactions in internal audit.
(12) Full compliance with customer-identification and anti-money-laundering directives shall be ensured when conducting transactions.
(13) Limited banking service may be provided only after obtaining prior approval of this Bank and subject to the above conditions, other prevailing law and the directives of this Bank.
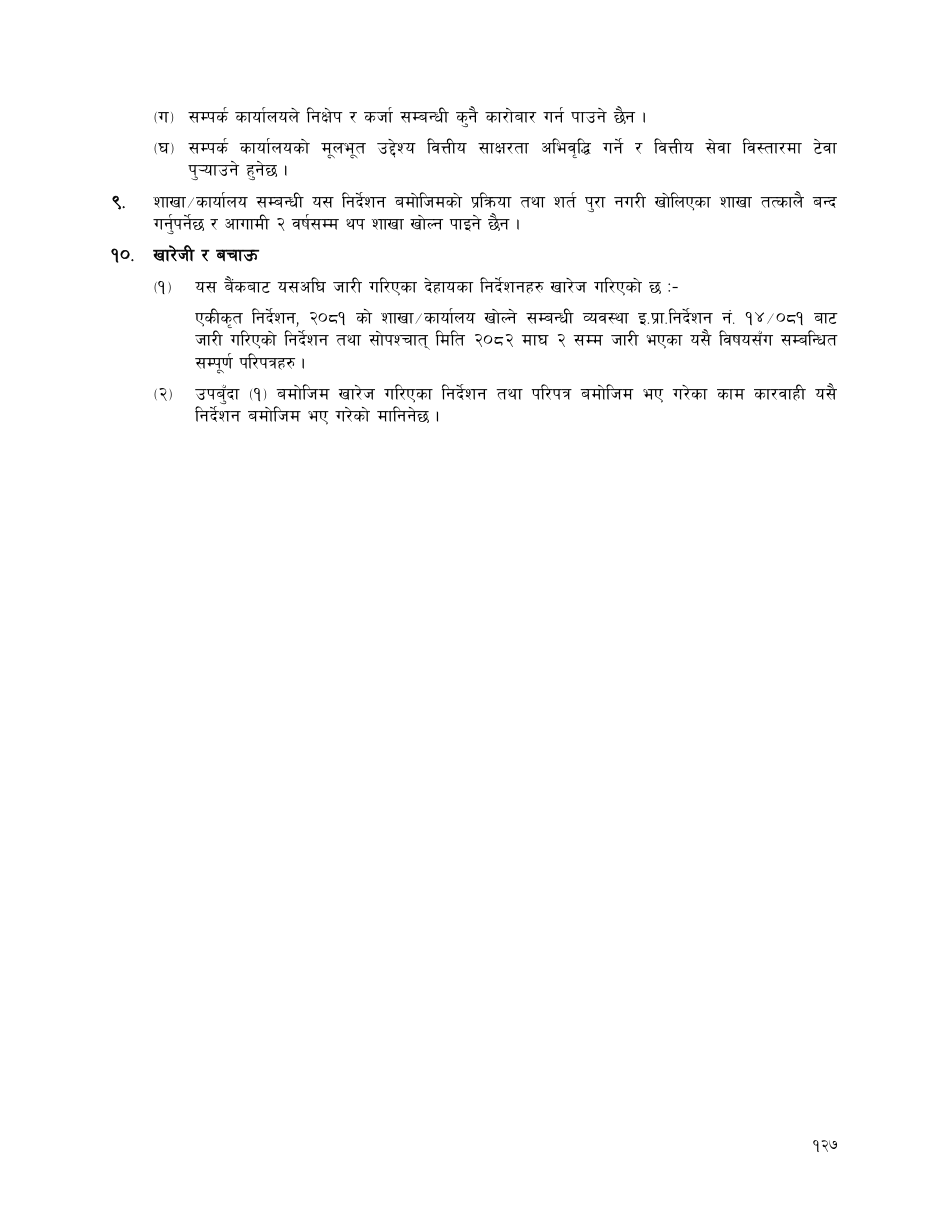
(क) बैंक तथा वित्तीय संस्थाहरुले कर्णाली प्रदेश र सुदूर पश्चिम प्रदेशहरुमा सम्पर्क कार्यालय खोल्न यस बैंकको स्वीकृति लिनु पर्ने छैन ।
(ख) यस व्यवस्था बमोजिम सम्पर्क कार्यालय खोलेको जानकारी १५ दिनभित्र यस बैंकको बैंक तथा वित्तीय संस्था नियमन विभाग र सम्बन्धित सुपरिवेक्षण विभागमा गराउनु पर्नेछ ।
(ग) सम्पर्क कार्यालयले निक्षेप र कर्जा सम्बन्धी कुनै कारोबार गर्न पाउने छैन ।
(घ) सम्पर्क कार्यालयको मूलभूत उद्देश्य वित्तीय साक्षरता अभिवृद्धि गर्ने र वित्तीय सेवा विस्तारमा टेवा पुर्याउने हुनेछ ।
Controlled English translation
(a) Banks and financial institutions shall not be required to obtain approval of this Bank to open liaison offices in Karnali Province and Sudurpashchim Province.
(b) Information regarding a liaison office opened under this provision shall be provided within 15 days to the Banks and Financial Institutions Regulation Department of this Bank and the concerned Supervision Department.
(c) A liaison office shall not be permitted to conduct deposit or credit transactions.
(d) The principal objective of a liaison office shall be to enhance financial literacy and support expansion of financial services.
शाखा/कार्यालय सम्बन्धी यस निर्देशन बमोजिमको प्रक्रिया तथा शर्त पूरा नगरी खोलिएका शाखा तत्कालै बन्द गर्नुपर्नेछ र आगामी २ वर्षसम्म थप शाखा खोल्न पाइने छैन ।
Controlled English translation
Any branch opened without completing the procedures and conditions prescribed by this Directive relating to branches/offices shall be closed immediately, and no additional branch may be opened for the following two years.
(१) यस बैंकबाट यसअघि जारी गरिएका देहायका निर्देशनहरु खारेज गरिएको छ :-
एकीकृत निर्देशन, २०८१ को शाखा/कार्यालय खोल्ने सम्बन्धी व्यवस्था इ.प्रा.निर्देशन नं. १४/०८१ बाट जारी गरिएको निर्देशन तथा सोपश्चात् मिति २०८२ माघ २ सम्म जारी भएका यसै विषयसँग सम्बन्धित सम्पूर्ण परिपत्रहरु ।
(२) उपबुँदा (१) बमोजिम खारेज गरिएका निर्देशन तथा परिपत्र बमोजिम भए गरेका काम कारवाही यसै निर्देशन बमोजिम भए गरेको मानिनेछ ।
Controlled English translation
(1) The following directives previously issued by this Bank are hereby repealed:
Directive No. 14/081 issued under the provisions relating to opening branches/offices in the Unified Directives, 2081, and all circulars relating to the same subject issued thereafter up to Magh 2, 2082.
(2) Any acts or actions done or taken pursuant to the directives and circulars repealed under sub-clause (1) shall be deemed to have been done or taken pursuant to this Directive.
Original Nepali text is authoritative. English is a controlled facilitative translation and is not an official Nepal Rastra Bank translation.
In case of inconsistency, ambiguity or difference, the official Nepali Directive and applicable Nepal Rastra Bank circulars prevail.
C.M. & Associates is not affiliated with, approved by or endorsed by Nepal Rastra Bank. This material is provided for information and reference only and does not constitute legal, regulatory, tax or professional advice.
Technical controls cannot guarantee prevention of screenshots or copying.