Directive 13अनिवार्य मौज्दात/वैधानिक तरलता सम्बन्धी व्यवस्थाProvisions Relating to Compulsory Reserve / Statutory Liquidity
Original/reproduced Nepali source controls; English is a controlled facilitative translation.
Applicability Class A licensed institutions; Class B licensed institutions; Class C licensed institutions
Classification PASS
Updated-through statement No later directive-specific amendment event is asserted beyond the supplied reviewed source set.
Rendering basis Render web-normalized sections and canonical supplemental objects exactly. Canonical reviewed JSON is authoritative for web/PDF. Do not OCR or rewrite legal text.
नेपाली मूल पाठ
यस बैंकबाट “क”, “ख” र “ग” वर्गको इजाजतपत्रप्राप्त संस्थाले आफ्नो निक्षेप तथा सापटी दायित्वको आधारमा कायम गर्नु पर्ने अनिवार्य मौज्दात तथा तरल सम्पत्ति व्यवस्था सम्बन्धमा नेपाल राष्ट्र बैंक ऐन, २०५८ को दफा ७९ ले दिएको अधिकार प्रयोग गरी देहायका निर्देशन जारी गरिएको छ ।
Controlled English translation
In exercise of the authority conferred by Section 79 of the Nepal Rastra Bank Act, 2058, the following directives are issued in relation to the compulsory reserve and liquid-asset requirements to be maintained by Class “A”, “B” and “C” licensed institutions on the basis of their deposit and borrowing liabilities.
(१) यस बैंकबाट इजाजतपत्रप्राप्त “क”, “ख” र “ग” वर्गका संस्थाले कुल निक्षेप दायित्वको ४ (चार) प्रतिशत अनिवार्य नगद मौज्दातबापत यस बैंकमा राख्नु पर्नेछ । यस व्यवस्थाबमोजिम कायम गर्नु पर्ने अनिवार्य नगद मौज्दातको न्यूनतम ९० प्रतिशत रकम मिति २०८२/०२/१८ देखि दैनिक रुपमा यस बैंकमा राख्नु पर्नेछ ।
(२) “ख” र “ग” वर्गका इजाजतपत्रप्राप्त संस्थाले यस बैंकको कार्यालय नभएको स्थानमा नजिकको “क” वर्गको इजाजतपत्रप्राप्त संस्थामा यस प्रयोजनको लागि चल्ती खाता खोली आवश्यक रकम जम्मा गरेमा पनि अनिवार्य मौज्दातमा गणना गरिनेछ ।
तर, ब्याज आर्जन हुने गरी “क” वर्गको इजाजतपत्रप्राप्त संस्थामा जम्मा गरेको रकमलाई अनिवार्य मौज्दातमा गणना गरिने छैन । यस्तो खाताको जानकारी यस बैंकको सम्बन्धित सुपरिवेक्षण विभागमा दिनु पर्नेछ ।
अनिवार्य मौज्दात प्रयोजनका लागि खोलिने खाता सम्बन्धित वित्तीय संस्थाको केन्द्रीय कार्यालय भएको स्थानमा मात्र खोल्नु पर्नेछ ।
सम्बन्धित वित्तीय संस्थाको केन्द्रीय कार्यालय रहेको स्थानमा नेपाल राष्ट्र बैंकको कार्यालय नभएको खण्डमा नजिकको “क” वर्गको एउटा बैंकमा जम्मा गरेको रकमलाई मात्र अनिवार्य मौज्दातमा गणना गरिनेछ । यस बैंकको कार्यालय बाहेक एकभन्दा बढी बैंक/शाखामा जम्मा गरेको रकमलाई यस प्रयोजनका लागि योग्य मानिने छैन ।
अनिवार्य मौज्दात गणना गर्ने प्रयोजनका लागि खाता खोलिएको बैंकबाट सम्बन्धित वित्तीय संस्थाले कुनै खण्डको गैरकोषीय सापटी/सुविधा उपयोग गर्न पाउने छैन । तर, विपन्न वर्ग कर्जा उपलब्ध गर्न/गराउन यस निर्देशनले बाधा पुगेको मानिने छैन ।
(३) उपबुँदा (१) बमोजिम राख्नु पर्ने मौज्दात नपुग भएको अवस्थामा देहायबमोजिम जरिवाना लगाइने छ :-
(क) पहिलो पटक अनिवार्य मौज्दात नपुग भएको अवस्थामा नपुग भए जति रकममा प्रचलित बैंक दरको प्रतिशतमात्र ।
(ख) दोस्रो पटक अनिवार्य मौज्दात नपुग भएको अवस्थामा नपुग भए जति रकममा प्रचलित बैंक दरको दुई प्रतिशतले ।
(ग) तेस्रो पटक र सो भन्दा पछि जति पटक नपुग भए पनि नपुग भए जति रकममा प्रचलित बैंक दरको दोब्बर प्रतिशतले ।
तर, समस्याग्रस्त घोषणा गरी निक्षेप स्वीकार तथा कर्जा प्रवाहमा प्रतिबन्ध लगाएको अवस्थामा त्यस्तो बैंक वा वित्तीय संस्थालाई जरिवाना लगाउन अनिवार्य हुने छैन ।
(४) उपबुँदा (३) को खण्ड (क), (ख) र (ग) बमोजिम पटक कायम गर्दा प्रत्येक आर्थिक वर्षको लागि अलग अलग पटक कायम गरिने छ । जरिवानाको पटक निर्धारण गर्दा १४ दिन (दुई सप्ताह) को मौज्दात गणनालाई एक पटक मानिनेछ ।
(५) अनिवार्य मौज्दातमा नपुग भएजति रकममा प्रचलित बैंक दरको प्रतिशतले दुई हप्ताको हिसाबमा जरिवाना लगाइनेछ र यसरी नपुग भएजतिको रकमलाई बैंक दरको प्रतिशतले गुणा गरी सोही आर्थिक वर्षको कुल अनिवार्य मौज्दात गणना हुने अवधि (दुई हप्ता) एक अवधिले भाग गरिनेछ । एउटै अवधि (दुईहप्ताको) मा न्यूनतम दैनिक मौज्दात तथा अनिवार्य मौज्दात दुबैमा नपुग भएमा नपुग लाग्ने जरिवानामध्ये जुन बढी हुन्छ सो मात्र लाग्ने छ ।
(६) अनिवार्य मौज्दात गणना सम्बन्धी प्रयोजनका लागि देहायको प्रक्रिया अपनाइनेछ :-
(क) अनिवार्य मौज्दातको गणना साप्ताहिक औसत निक्षेप मौज्दातका आधारमा गरिने छ ।
(ख) मौज्दातको गणना गर्दा खण्ड (क) मा उल्लिखित समयावधि पछि एकहप्ता अन्तराल कायम गरी तत्पश्चातको दुई हप्ता (आइतबार देखि १४ औं दिनको शनिबार) मा कायम गरिने औसत नगद मौज्दातलाई लिइनेछ ।
(ग) अनिवार्य मौज्दात गणना गर्ने प्रयोजनको लागि कुल निक्षेप दायित्वका हकमा साप्ताहिक रुपमा आइतबार देखि शनिबारसम्मको कुल निक्षेपको योगलाई सात अङ्कले भाग गरी दैनिक औसत निर्धारण गरिनेछ । त्यसरी निकालिएको नगद मौज्दातको गणना गर्दा आइतबार देखि १४ औं दिनको शनिबारसम्मको दैनिक मौज्दातको कुल योगलाई चौध अङ्कले भाग गरी दैनिक औसत निर्धारण गरिने छ ।
(घ) यस निर्देशन बमोजिम कायम गर्नुपर्ने अनिवार्य मौज्दातको कम्तीमा ९० प्रतिशत मौज्दात दैनिक रुपमा कायम गर्नु पर्नेछ ।
(७) यस उद्देश्यको लागि इजाजतपत्रप्राप्त संस्थाको सम्पूर्ण कार्यालयहरुलाई एउटै इकाई मानिने छ ।
(८) यस बैंकमा रहेको खातामा जम्मा हुने गरी फण्ड ट्रान्सफरको सिलसिलामा मार्गस्थ (Transit) मा पर्न गएको स्वदेशी मुद्राको रकमलाई यस बैंकको मौज्दातमा समावेश गराइने छ । बैंक तथा वित्तीय संस्थाले मार्गस्थमा पर्न गएको स्वदेशी मुद्राको रकमको प्रमाण समेत संलग्न गरी पठाउनु पर्नेछ ।
Controlled English translation
(1) Class “A”, “B” and “C” institutions licensed by this Bank shall maintain with this Bank, as compulsory cash reserve, 4 (four) percent of their total deposit liabilities. At least 90 percent of the compulsory cash reserve required under this provision shall, from 2082/02/18, be maintained with this Bank on a daily basis.
(2) Where a Class “B” or Class “C” licensed institution, at a place where this Bank has no office, opens a current account with the nearest Class “A” licensed institution for this purpose and deposits the required amount, such amount shall also be counted toward compulsory reserve.
However, an amount deposited with a Class “A” licensed institution so as to earn interest shall not be counted toward compulsory reserve. Information relating to such account shall be provided to the concerned Supervision Department of this Bank.
An account opened for compulsory-reserve purposes shall be opened only at the place where the central office of the concerned financial institution is situated.
Where there is no office of Nepal Rastra Bank at the place where the central office of the concerned financial institution is situated, only the amount deposited with one nearest Class “A” bank shall be counted toward compulsory reserve. Amounts deposited with more than one bank/branch, other than an office of this Bank, shall not qualify for this purpose.
For purposes of compulsory-reserve calculation, the concerned financial institution shall not use any non-fund-based borrowing/facility from the bank with which such account is opened. However, nothing in this Directive shall prevent providing/causing provision of deprived-sector credit.
(3) Where the reserve required under sub-clause (1) is deficient, a fine shall be imposed as follows:
(a) for the first instance of deficiency in compulsory reserve, on the deficient amount at the prevailing Bank Rate;
(b) for the second instance of deficiency, on the deficient amount at the prevailing Bank Rate plus two percent;
(c) for the third and every subsequent instance of deficiency, on the deficient amount at twice the prevailing Bank Rate.
However, where an institution has been declared problematic and restricted from accepting deposits and extending credit, imposition of such fine on that bank or financial institution shall not be mandatory.
(4) For purposes of counting instances under paragraphs (a), (b) and (c) of sub-clause (3), each fiscal year shall be counted separately. For determining the number of instances of fine, the 14-day (two-week) reserve-calculation period shall be treated as one instance.
(5) A fine shall be imposed on the deficient amount in compulsory reserve, calculated for two weeks at the prevailing Bank Rate; for this purpose the deficient amount shall be multiplied by the Bank Rate percentage and divided by one reserve-calculation period (two weeks) of the relevant fiscal year. Where, within the same two-week period, both the minimum daily reserve and the compulsory reserve are deficient, only the higher of the applicable fines shall be imposed.
(6) The following procedure shall be followed for purposes of compulsory-reserve calculation:
(a) compulsory reserve shall be calculated on the basis of the weekly average deposit balance;
(b) in calculating the reserve, after the period referred to in paragraph (a), an interval of one week shall be maintained and the average cash balance maintained during the following two weeks (from Sunday to the fourteenth day, Saturday) shall be taken;
(c) for purposes of compulsory-reserve calculation, in respect of total deposit liabilities, the sum of total deposits from Sunday to Saturday on a weekly basis shall be divided by seven to determine the daily average. In calculating the cash balance so derived, the total of the daily balances from Sunday to the fourteenth day, Saturday, shall be divided by fourteen to determine the daily average;
(d) at least 90 percent of the compulsory reserve required under this Directive shall be maintained on a daily basis.
(7) For this purpose, all offices of a licensed institution shall be treated as one unit.
(8) Domestic-currency amounts that are in transit in the course of a fund transfer for deposit into an account maintained with this Bank shall be included in the balance with this Bank. The bank or financial institution shall submit evidence of the domestic-currency amount in transit.
(१) यस दफाको प्रयोजनको लागि “कुल निक्षेप” भन्नाले इजाजतपत्रप्राप्त संस्थाको चल्ती, कल, बचत र मुद्दती खातामा जम्मा भएको रकम सम्झनु पर्छ र सो शब्दले इजाजतपत्रप्राप्त संस्थाले यस बैंकले तोकेबमोजिमका विभिन्न वित्तीय उपकरणको माध्यमबाट स्वीकार गर्ने रकम समेतलाई जनाउँछ ।
(२) यस बैंकको साधारण खातामा भएको मौज्दातलाई मात्र अनिवार्य मौज्दातमा गणना गरिने छ । यस बैंकमा विशेष प्रयोजनको लागि खोलिएको विशेष खाता तथा विदेशी मुद्रा खातामा रहेको रकमलाई यस प्रयोजनको लागि गणना गरिने छैन ।
(३) अनिवार्य मौज्दात गणना प्रयोजनको लागि परिवर्त्य विदेशी मुद्राको निक्षेप, कर्मचारी जमानत तथा मार्जिन खातामा रहेको रकम कुल निक्षेपमा समावेश गरिने छैन ।
(४) “चल्ती खाता” भन्नाले मागेको बखत जहिले पनि झिक्न मिल्ने गरी बैंक वा वित्तीय संस्थामा राखिएको रकमको हरहिसाब लेखिएको खाता सम्झनु पर्छ ।
(५) “बचत खाता” भन्नाले बैंक वा वित्तीय संस्थामा बचतको निमित्त राखिएको रकमको हरहिसाब लेखिएको खाता सम्झनु पर्छ ।
(६) “मुद्दती खाता” भन्नाले बैंक वा वित्तीय संस्थामा निश्चित अवधिसम्म जम्मा रहने गरी राखिएको रकमको हरहिसाब लेखिएको खाता सम्झनु पर्छ ।
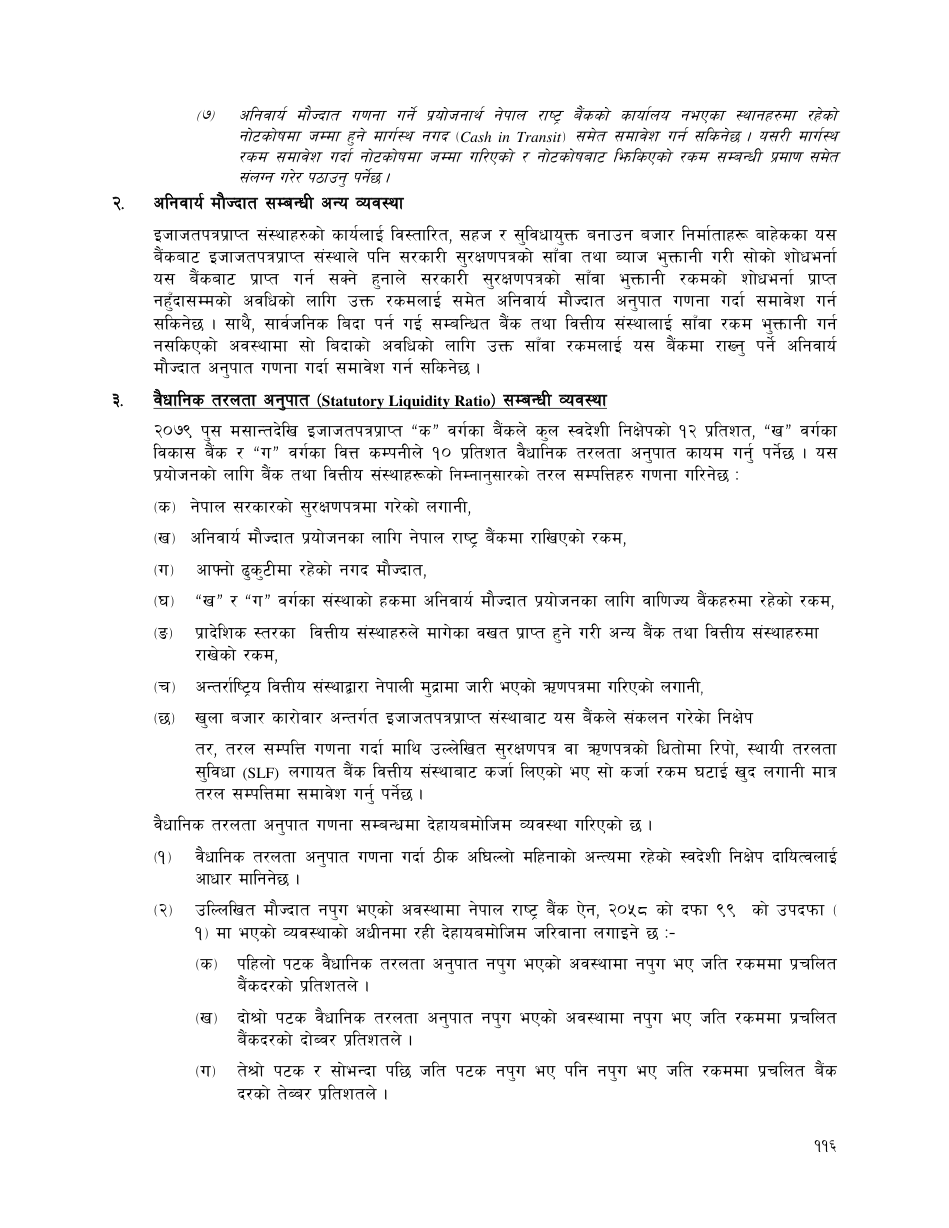
(७) अनिवार्य मौज्दात गणना गर्ने प्रयोजनार्थ नेपाल राष्ट्र बैंकको कार्यालय नभएका स्थानहरुमा रहेको नोटकोषमा जम्मा हुने मार्गस्थ नगद (Cash in Transit) समेत समावेश गर्न सकिनेछ । यसरी मार्गस्थ रकम समावेश गर्दा नोटकोषमा जम्मा गरिसकेको र नोटकोषबाट फिर्ता भएको रकम सम्बन्धी प्रमाण समेत संलग्न गरेर पठाउनु पर्नेछ ।
Controlled English translation
(1) For the purpose of this clause, “total deposits” means amounts deposited in current, call, savings and fixed accounts of a licensed institution, and includes amounts accepted by a licensed institution through various financial instruments as prescribed by this Bank.
(2) Only the balance in the ordinary account maintained with this Bank shall be counted toward compulsory reserve. Amounts held in special-purpose accounts and foreign-currency accounts maintained with this Bank shall not be counted for this purpose.
(3) For compulsory-reserve calculation, convertible foreign-currency deposits, employee security deposits and amounts in margin accounts shall not be included in total deposits.
(4) “Current account” means an account recording amounts kept with a bank or financial institution that may be withdrawn at any time on demand.
(5) “Savings account” means an account recording amounts kept with a bank or financial institution for saving purposes.
(6) “Fixed account” means an account recording amounts kept with a bank or financial institution for a specified period.
(7) For compulsory-reserve calculation, cash in transit to the note chest located in a place where Nepal Rastra Bank has no office may also be included. When such amount in transit is included, evidence relating to the amount deposited into and returned from the note chest shall also be submitted.
इजाजतपत्रप्राप्त संस्थाहरुको कार्यालय विस्तारित, सहज र सुविधायुक्त बनाउन बजार निर्माताहरु बाहेकका यस बैंकबाट इजाजतपत्रप्राप्त संस्थाले पनि सरकारी सुरक्षणपत्रको साँवा तथा ब्याज भुक्तानी गरी सोको शोधभर्ना यस बैंकबाट प्राप्त गर्न सक्ने हुनाले सरकारी सुरक्षणपत्रको साँवा भुक्तानी रकमको शोधभर्ना प्राप्त नहुँदासम्मको अवधिको लागि उक्त रकमलाई समेत अनिवार्य मौज्दात अनुपात गणना गर्दा समावेश गर्न सकिनेछ । साथै, सार्वजनिक बिदा पर्न गई सम्बन्धित बैंक तथा वित्तीय संस्थालाई साँवा रकम भुक्तानी गर्न नसकिएको अवस्थामा सो दिनको अनिवार्य मौज्दात शोधभर्ना गरिएको रकम संकलन राख्नु अनिवार्य मौज्दात अनुपात गणना गर्दा समावेश गर्न सकिनेछ ।
Controlled English translation
In order to make the offices of licensed institutions more extensive, convenient and accessible, institutions licensed by this Bank other than market makers may also make payment of principal and interest on Government securities and obtain reimbursement thereof from this Bank. Accordingly, until reimbursement of the principal amount of Government securities is received, such amount may also be included in calculating the compulsory-reserve ratio. Likewise, where due to a public holiday the principal amount cannot be paid to the concerned bank or financial institution, the reimbursable amount relating to that day’s compulsory reserve may be included in calculating the compulsory-reserve ratio.
२०७९ पुस मसान्तदेखि इजाजतपत्रप्राप्त “क” वर्गका बैंकले कुल स्वदेशी निक्षेपको १२ प्रतिशत, “ख” वर्गका विकास बैंक र “ग” वर्गका वित्त कम्पनीले १० प्रतिशत वैधानिक तरलता अनुपात कायम गर्नु पर्नेछ । यस प्रयोजनको लागि बैंक तथा वित्तीय संस्थाहरुको निम्नानुसारको तरल सम्पत्तिहरु गणना गरिनेछ ।
(क) नेपाल सरकारको सुरक्षणपत्रमा गरेको लगानी,
(ख) अनिवार्य मौज्दात प्रयोजनका लागि नेपाल राष्ट्र बैंकमा राखिएको रकम,
(ग) आफ्नो ढुकुटीमा रहेको नगद मौज्दात,
(घ) “ख” र “ग” वर्गका संस्थाको हकमा अनिवार्य मौज्दात प्रयोजनका लागि वाणिज्य बैंकहरुमा रहेको रकम,
(ङ) प्रादेशिक स्तरका वित्तीय संस्थाहरुले मागेको बखत प्राप्त हुने गरी अन्य बैंक तथा वित्तीय संस्थाहरुमा राखेको रकम,
(च) अन्तर्राष्ट्रिय वित्तीय संस्थाद्वारा नेपाली मुद्रामा जारी भएको ऋणपत्रमा गरिएको लगानी,
(छ) खुला बजार कारोबार अन्तर्गत इजाजतपत्रप्राप्त संस्थाबाट यस बैंकले संकलन गरेको निक्षेप ।
तर, तरल सम्पत्ति गणना गर्दा माथि उल्लेखित सुरक्षणपत्र वा ऋणपत्रको धितोमा रिपो, स्थायी तरलता सुविधा (SLF) लगायत बैंक वित्तीय संस्थाबाट कर्जा लिएको भए सो कर्जा रकम घटाई खुद लगानी मात्र तरल सम्पत्तिमा समावेश गर्नु पर्नेछ ।
वैधानिक तरलता अनुपात गणना सम्बन्धमा देहायबमोजिम व्यवस्था गरिएको छ ।
(१) वैधानिक तरलता अनुपात गणना गर्दा ठीक अघिल्लो महिनाको अन्त्यमा रहेको स्वदेशी निक्षेप दायित्वलाई आधार मानिनेछ ।
(२) उल्लिखित मौज्दात नपुग भएको अवस्थामा नेपाल राष्ट्र बैंक ऐन, २०५८ को दफा ९९ को उपदफा (१) मा भएको व्यवस्थाको अधीनमा रही देहायबमोजिम जरिवाना लगाइने छ :-
(क) पहिलो पटक वैधानिक तरलता अनुपात नपुग भएको अवस्थामा नपुग भए जति रकममा प्रचलित बैंकदरको प्रतिशतले ।
(ख) दोस्रो पटक वैधानिक तरलता अनुपात नपुग भएको अवस्थामा नपुग भए जति रकममा प्रचलित बैंकदरको दोब्बर प्रतिशतले ।
(ग) तेस्रो पटक र सोभन्दा पछि जति पटक नपुग भए पनि नपुग भए जति रकममा प्रचलित बैंक दरको तेब्बर प्रतिशतले ।
तर, समस्याग्रस्त घोषणा गरी निक्षेप स्वीकार तथा कर्जा प्रवाहमा प्रतिबन्ध लगाएको अवस्थामा त्यस्तो बैंक वा वित्तीय संस्थालाई जरिवाना लगाउन अनिवार्य हुने छैन ।
(३) उपबुँदा (२) को खण्ड (क), (ख) र (ग) बमोजिम पटक कायम गर्दा प्रत्येक आर्थिक वर्षको लागि अलग अलग पटक कायम गरिनेछ । जरिवानाको पटक निर्धारण महिनाको आधारमा गरिनेछ ।
(४) वैधानिक तरलता अनुपात नपुग भए जति रकममा प्रचलित बैंकदरको प्रतिशतले मासिक हिसाबमा जरिवाना लगाइनेछ र यसरी नपुग भए जति रकमलाई बैंकदरको प्रतिशतले गुणा गरी १२ ले भाग गरिनेछ ।
(५) वैधानिक तरलता अनुपात नपुग भएको अवस्थामा जरिवानाको प्रयोजनका लागि यस बैंकले तोके बमोजिम प्रकाशित गरेको बैंकदरलाई नै आधार लिइनेछ ।
प्रष्टीकरण:
(१) यस दफाको प्रयोजनको लागि सरकारी सुरक्षणपत्र भन्नाले नेपाल सरकारले जारी गरेको बचतपत्र, विकास ऋणपत्र, ट्रेजरी बिल तथा यस बैंकले तोकेको अन्य सुरक्षणपत्र सम्झनु पर्छ ।
तर, बजार निर्माता (Market Maker) को रुपमा कार्य गरिरहेका बैंक तथा वित्तीय संस्थाहरुले कारोबार (Trading) प्रयोजनको लागि नेपाल राष्ट्र बैंक, राष्ट्र ऋण व्यवस्थापन विभाग अन्तर्गतको विशेष खाता (Special Account) मा रहेको सरकारी सुरक्षणपत्र रकमलाई निक्षेप गणना (Trading) प्रयोजनको लागि मात्र हुने हुँदा सो सुरक्षणपत्रको रकम वैधानिक तरलता अनुपात (Statutory Liquidity Ratio, SLR) प्रयोजनको लागि सरकारी सुरक्षणपत्रमा गणना गर्न पाइने छैन ।
Controlled English translation
From the end of Poush 2079, Class “A” banks shall maintain a Statutory Liquidity Ratio of 12 percent of total domestic deposits, and Class “B” development banks and Class “C” finance companies shall maintain 10 percent. For this purpose, the following liquid assets of banks and financial institutions shall be counted:
(a) investment in Government of Nepal securities;
(b) amounts maintained with Nepal Rastra Bank for compulsory-reserve purposes;
(c) cash balance held in own vault;
(d) in the case of Class “B” and “C” institutions, amounts maintained with commercial banks for compulsory-reserve purposes;
(e) amounts maintained by provincial-level financial institutions with other banks and financial institutions, receivable on demand;
(f) investment in debentures issued in Nepali currency by international financial institutions;
(g) deposits collected by this Bank from licensed institutions under open-market operations.
However, when calculating liquid assets, where credit has been taken against the above securities or debentures through repo, Standing Liquidity Facility (SLF) or from banks/financial institutions, the amount of such credit shall be deducted and only the net investment shall be included as liquid assets.
The following arrangements apply to calculation of the Statutory Liquidity Ratio:
(1) in calculating the Statutory Liquidity Ratio, domestic deposit liabilities as at the end of the immediately preceding month shall be taken as the basis;
(2) where the required balance is deficient, a fine shall be imposed subject to Section 99(1) of the Nepal Rastra Bank Act, 2058 as follows:
(a) for the first instance of deficiency, on the deficient amount at the prevailing Bank Rate;
(b) for the second instance, on the deficient amount at twice the prevailing Bank Rate;
(c) for the third and every subsequent instance, on the deficient amount at three times the prevailing Bank Rate.
However, where an institution has been declared problematic and restricted from accepting deposits and extending credit, imposition of such fine shall not be mandatory.
(3) for purposes of counting instances under paragraphs (a), (b) and (c) of sub-clause (2), each fiscal year shall be counted separately; the number of instances shall be determined on a monthly basis;
(4) a fine shall be imposed monthly on the deficient amount at the prevailing Bank Rate by multiplying the deficient amount by the Bank Rate percentage and dividing by 12;
(5) for purposes of the fine for deficiency in the Statutory Liquidity Ratio, the Bank Rate published as prescribed by this Bank shall be used.
Explanation:
(1) For the purpose of this clause, Government securities mean savings certificates, development bonds, Treasury Bills issued by the Government of Nepal and other securities specified by this Bank.
However, Government securities held in a Special Account under the Public Debt Management Department of Nepal Rastra Bank by banks and financial institutions acting as Market Makers, for Trading purposes, shall not be counted as Government securities for Statutory Liquidity Ratio (SLR) purposes because such securities are held solely for Trading purposes.
(१) यस बैंकबाट यसअघि जारी गरिएका देहायका निर्देशनहरु खारेज गरिएको छ :-
एकीकृत निर्देशन, २०८१ को अनिवार्य मौज्दात/वैधानिक तरलता सम्बन्धी व्यवस्था इ.प्रा निर्देशन नं. १३/०८१ बाट जारी गरिएको निर्देशन तथा सोपश्चात् मिति २०८२ माघ २ सम्म जारी भएका यसै विषयसँग सम्बन्धित सम्पूर्ण परिपत्रहरु ।
(२) उपबुँदा (१) बमोजिम खारेज गरिएका निर्देशन तथा परिपत्र बमोजिम भए गरेका काम कारवाही यसै निर्देशन बमोजिम भए गरेको मानिनेछ ।
Controlled English translation
(1) The following directives previously issued by this Bank are hereby repealed:
Directive No. 13/081 issued under the provisions relating to compulsory reserve/statutory liquidity in the Unified Directives, 2081, and all circulars relating to the same subject issued thereafter up to Magh 2, 2082.
(2) Any acts or actions done or taken pursuant to the directives and circulars repealed under sub-clause (1) shall be deemed to have been done or taken pursuant to this Directive.
Original Nepali text is authoritative. English is a controlled facilitative translation and is not an official Nepal Rastra Bank translation.
In case of inconsistency, ambiguity or difference, the official Nepali Directive and applicable Nepal Rastra Bank circulars prevail.
C.M. & Associates is not affiliated with, approved by or endorsed by Nepal Rastra Bank. This material is provided for information and reference only and does not constitute legal, regulatory, tax or professional advice.
Technical controls cannot guarantee prevention of screenshots or copying.