Directive 16वित्तीय स्रोत संकलन सम्बन्धी व्यवस्थाProvisions Relating to Mobilisation of Financial Resources
Original/reproduced Nepali source controls; English is a controlled facilitative translation.
Applicability Class A licensed institutions; Class B licensed institutions; Class C licensed institutions
Classification PASS
Updated-through statement No later directive-specific amendment event is asserted beyond the supplied reviewed source set.
Rendering basis Render web-normalized sections and canonical supplemental objects exactly. Canonical reviewed JSON is authoritative for web/PDF. Do not OCR or rewrite legal text.
नेपाली मूल पाठ
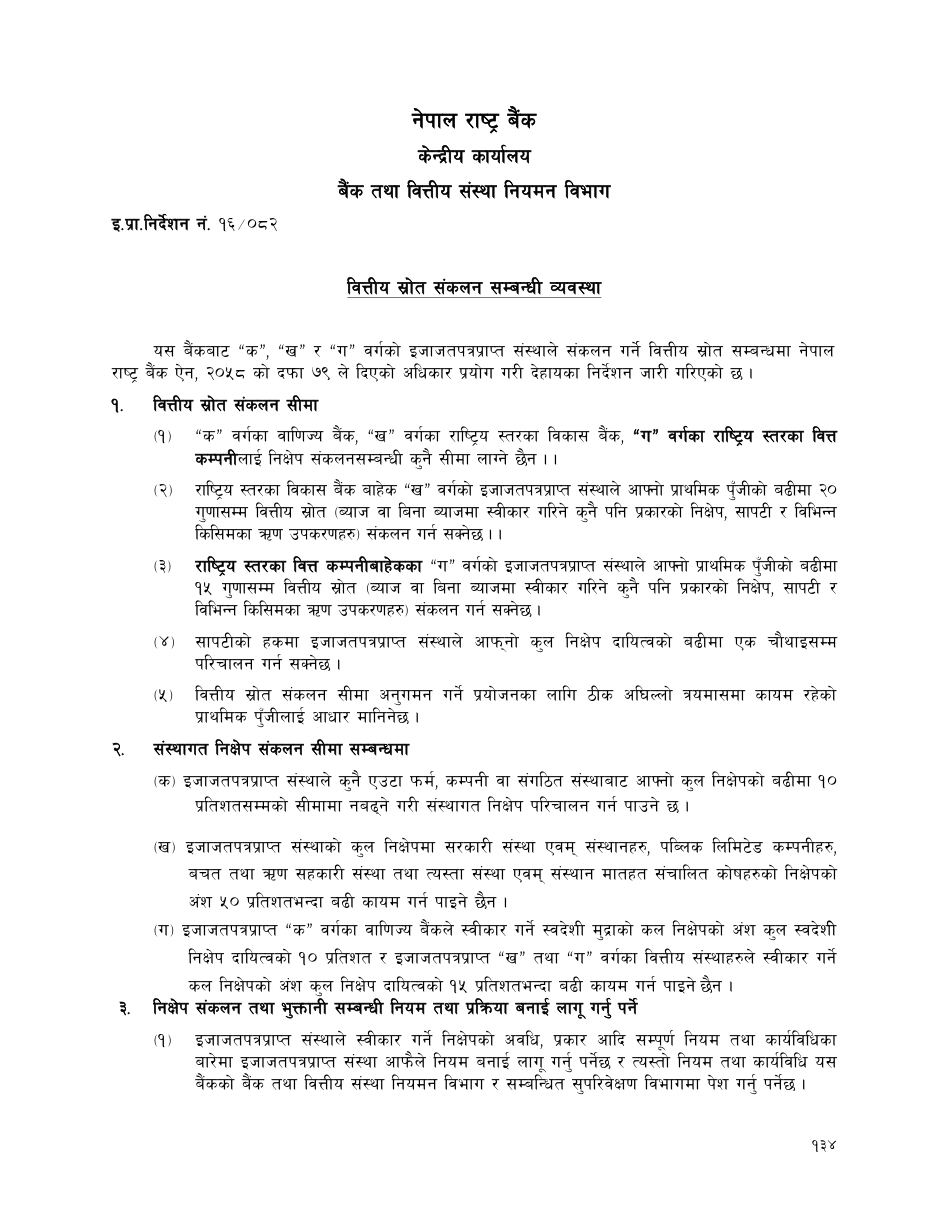
यस बैंकबाट “क”, “ख” र “ग” वर्गको इजाजतपत्रप्राप्त संस्थाले संकलन गर्ने वित्तीय स्रोत सम्बन्धमा नेपाल राष्ट्र बैंक ऐन, २०५८ को दफा ७९ ले दिएको अधिकार प्रयोग गरी देहायका निर्देशन जारी गरिएको छ ।
Controlled English translation
In exercise of the authority conferred by Section 79 of the Nepal Rastra Bank Act, 2058, the following directives are issued in relation to financial resources mobilised by Class “A”, “B” and “C” licensed institutions.
(१) “क” वर्गका वाणिज्य बैंक, “ख” वर्गका राष्ट्रिय स्तरका विकास बैंक, “ग” वर्गका राष्ट्रिय स्तरका वित्त कम्पनीलाई निक्षेप संकलनसम्बन्धी कुनै सीमा लाग्ने छैन ।
(२) राष्ट्रिय स्तरका विकास बैंक बाहेक “ख” वर्गको इजाजतपत्रप्राप्त संस्थाले आफ्नो प्राथमिक पुँजीको बढीमा २० गुणासम्म वित्तीय स्रोत (ब्याज वा बिना ब्याजमा स्वीकार गरिने कुनै पनि प्रकारको निक्षेप, सापटी र विभिन्न किसिमका ऋण उपकरणहरु) संकलन गर्न सक्नेछ ।
(३) राष्ट्रिय स्तरका वित्त कम्पनीबाहेकका “ग” वर्गको इजाजतपत्रप्राप्त संस्थाले आफ्नो प्राथमिक पुँजीको बढीमा १५ गुणासम्म वित्तीय स्रोत (ब्याज वा बिना ब्याजमा स्वीकार गरिने कुनै पनि प्रकारको निक्षेप, सापटी र विभिन्न किसिमका ऋण उपकरणहरु) संकलन गर्न सक्नेछ ।
(४) सापटीको हकमा इजाजतपत्रप्राप्त संस्थाले आफ्नो कुल निक्षेप दायित्वको बढीमा एक चौथाईसम्म परिचालन गर्न सक्नेछ ।
(५) वित्तीय स्रोत संकलन सीमा अनुगमन गर्ने प्रयोजनको लागि ठीक अघिल्लो त्रैमासमा कायम रहेको प्राथमिक पुँजीलाई आधार मानिनेछ ।
Controlled English translation
(1) No limit on deposit mobilisation shall apply to Class “A” commercial banks, national-level Class “B” development banks and national-level Class “C” finance companies.
(2) A Class “B” licensed institution other than a national-level development bank may mobilise financial resources up to twenty times its Tier 1 capital. For this purpose, financial resources include all forms of deposits accepted with or without interest, borrowings and various types of debt instruments.
(3) A Class “C” licensed institution other than a national-level finance company may mobilise financial resources up to fifteen times its Tier 1 capital. For this purpose, financial resources include all forms of deposits accepted with or without interest, borrowings and various types of debt instruments.
(4) In the case of borrowings, a licensed institution may mobilise an amount up to one-fourth of its total deposit liabilities.
(5) For monitoring the limit on financial-resource mobilisation, the Tier 1 capital maintained in the immediately preceding quarter shall be taken as the basis.
(क) इजाजतपत्रप्राप्त संस्थाले कुनै एउटा फर्म, कम्पनी वा संगठित संस्थाबाट आफ्नो कुल निक्षेपको बढीमा १० प्रतिशतसम्मको सीमामा नबढ्ने गरी संस्थागत निक्षेप परिचालन गर्न पाउने छ ।
(ख) इजाजतपत्रप्राप्त संस्थाको कुल निक्षेपमा सरकारी संस्था एवम् संस्थानहरु, पब्लिक लिमिटेड कम्पनीहरु, बचत तथा ऋण सहकारी संस्था तथा त्यस्ता संस्था एवम् संस्थान मातहत सञ्चालित कोषहरुको निक्षेपको अंश ५० प्रतिशतभन्दा बढी कायम गर्न पाउने छैन ।
(ग) इजाजतपत्रप्राप्त “क” वर्गका वाणिज्य बैंकले स्वीकार गर्ने स्वदेशी मुद्राको कुल निक्षेपमा संस्थागत निक्षेपको अंश १० प्रतिशत र इजाजतपत्रप्राप्त “ख” तथा “ग” वर्गका वित्तीय संस्थाहरुले स्वीकार गर्ने कुल निक्षेपको अंश कुल निक्षेप दायित्वको १५ प्रतिशतभन्दा बढी कायम गर्न पाउने छैन ।
Controlled English translation
(a) A licensed institution may mobilise institutional deposits from any one firm, company or organised institution only up to a limit not exceeding 10 percent of its total deposits.
(b) In the total deposits of a licensed institution, the share of deposits of Government bodies and public enterprises, public limited companies, savings and credit cooperatives and funds operated under such bodies and institutions shall not exceed 50 percent.
(c) In the total domestic-currency deposits accepted by a Class “A” commercial bank, the share of institutional deposits shall not exceed 10 percent; and in the case of Class “B” and “C” licensed financial institutions, the share of institutional deposits shall not exceed 15 percent of total deposit liabilities.
(१) इजाजतपत्रप्राप्त संस्थाले स्वीकार गर्ने निक्षेपको अवधि, प्रकार आदि सम्पूर्ण नियम तथा कार्यविधिका बारेमा इजाजतपत्रप्राप्त संस्था आफैंले नियम बनाई लागू गर्नु पर्नेछ र त्यस्तो नियम तथा कार्यविधि यस बैंकको बैंक तथा वित्तीय संस्था नियमन विभाग र सम्बन्धित सुपरिवेक्षण विभागमा पेश गर्नु पर्नेछ ।
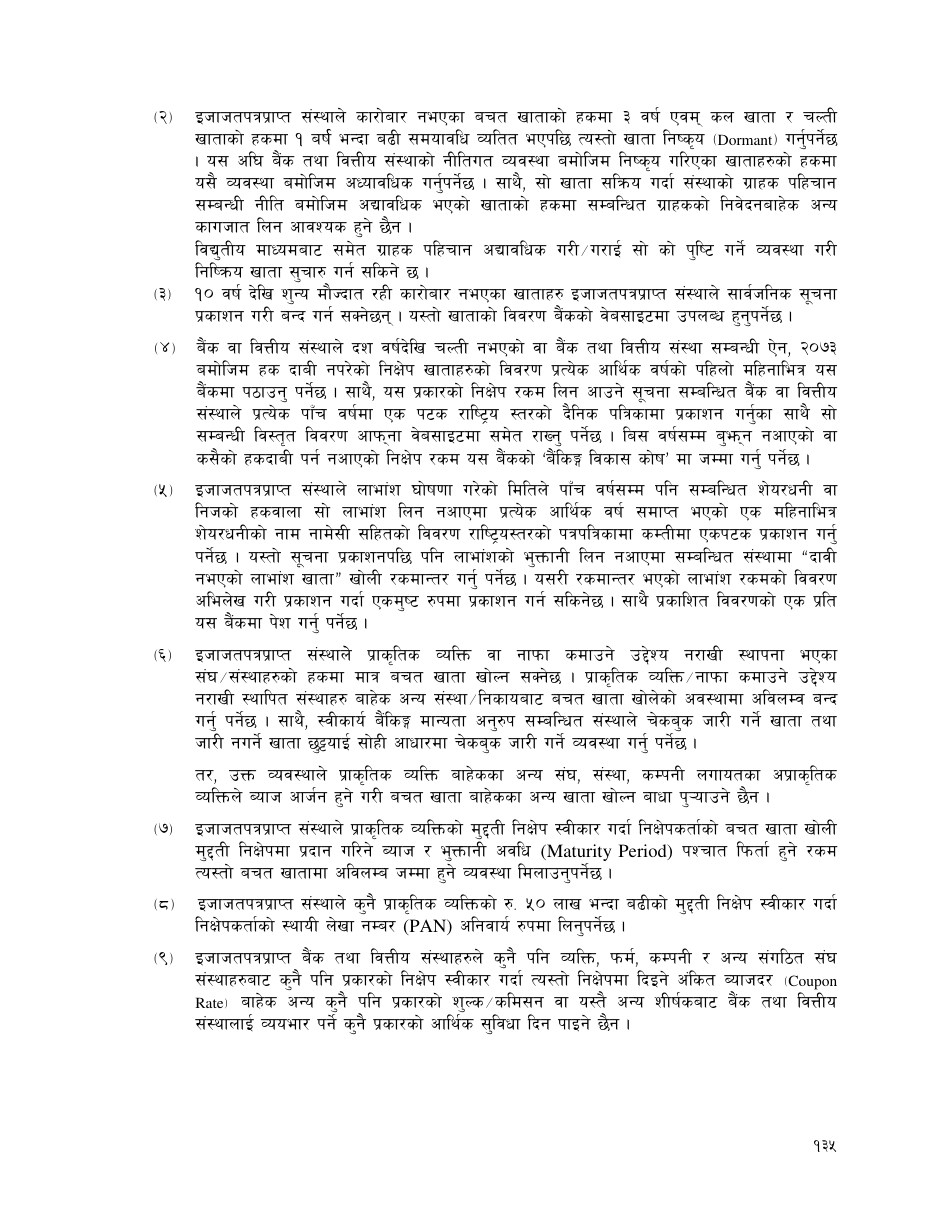
(२) इजाजतपत्रप्राप्त संस्थाले कारोबार नभएका बचत खाताको हकमा ३ वर्ष एवम् कल खाता र चल्ती खाताको हकमा १ वर्ष भन्दा बढी समयावधि व्यतीत भएपछि त्यस्तो खाता निष्क्रिय (Dormant) गर्नु पर्नेछ । यसअघि बैंक तथा वित्तीय संस्थाको नीतिगत व्यवस्था बमोजिम निष्क्रिय गरिएका खाताहरुको हकमा यसै व्यवस्था बमोजिम अध्यावधिक गर्नुपर्नेछ । साथै, सो खाता सक्रिय गर्दा संस्थाको ग्राहक पहिचान सम्बन्धी नीति बमोजिम अध्यावधिक भएको खाताको हकमा सम्बन्धित ग्राहकको निवेदनबाहेक अन्य कागजात लिन आवश्यक हुने छैन । विद्युतीय माध्यमबाट समेत ग्राहक पहिचान अध्यावधिक गरी/गराई सो को पुष्टि गर्ने व्यवस्था गरी निष्क्रिय खाता सुचारु गर्न सकिने छ ।
(३) १० वर्षदेखि शून्य मौज्दात रही कारोबार नभएका खाताहरु इजाजतपत्रप्राप्त संस्थाले सार्वजनिक सूचना प्रकाशन गरी बन्द गर्न सक्नेछन् । यस्तो खाता बन्द गर्दा बैंकको वेबसाइटमा उपलब्ध गराउनु पर्नेछ ।
(४) बैंक वा वित्तीय संस्थाले दश वर्षदेखि चल्ती नभएको वा बैंक तथा वित्तीय संस्था सम्बन्धी ऐन, २०७३ बमोजिम हक दाबी नभएको निष्क्रिय खाताहरुको विवरण प्रत्येक आर्थिक वर्षको पहिलो महिनाभित्र यस बैंकमा पठाउनु पर्नेछ । साथै, यस प्रकारको निक्षेप रकम लिन आउने सूचना सम्बन्धित बैंक वा वित्तीय संस्थाले प्रत्येक पाँच वर्षमा एक पटक राष्ट्रियस्तरको दैनिक पत्रिकामा प्रकाशन गर्नुका साथै सो सम्बन्धी विस्तृत विवरण आफ्नो वेबसाइटमा समेत राख्नु पर्नेछ । कसैको हकदाबी पर्न नआएको निक्षेप रकम यस बैंकको “बैंकिङ विकास कोष” मा जम्मा गर्नु पर्नेछ ।
(५) इजाजतपत्रप्राप्त संस्थाले लाभांश घोषणा गरेको मितिले पाँच वर्षसम्म पनि सम्बन्धित शेयरधनी वा निजको हकवालाले सो लाभांश लिन नआएमा प्रत्येक आर्थिक वर्ष समाप्त भएको एक महिनाभित्र शेयरधनीको नामनामेसी सहितको विवरण राष्ट्रियस्तरको पत्रिकामा कम्तीमा एकपटक प्रकाशन गर्नु पर्नेछ । यस्तो सूचना प्रकाशनपछि पनि लाभांशको भुक्तानी लिन नआएमा सम्बन्धित संस्थामा “दाबी नभएको लाभांश खाता” खोली रकम जम्मा गर्नु पर्नेछ । यसरी रकमान्तर भएको लाभांश रकमको विवरण अर्धवार्षिक गरी प्रकाशन गर्नु पर्नेछ र सो विवरण आफ्नो वेबसाइटमा तीन वर्षसम्म राखी यस बैंकमा पेश गर्नु पर्नेछ ।
(६) इजाजतपत्रप्राप्त संस्थाले प्राकृतिक व्यक्ति वा नाफा कमाउने उद्देश्य नराखी स्थापना भएका संघ/संस्थाहरुको हकमा मात्र बचत खाता खोल्न सक्नेछन् । प्राकृतिक व्यक्ति/नाफा कमाउने उद्देश्य नराखी स्थापित संस्थाहरु बाहेक अन्य संस्था, कम्पनी र अन्य संगठित संस्थाहरुको बचत खाता खोल्न पाइने छैन । साथै, स्वीकृत बैंकिङ मान्यता अनुरुप सम्बन्धित संस्थाले चेकबुक जारी गर्ने खाता तथा जारी नगर्ने खाता छुट्याई सोही आधारमा चेकबुक जारी गर्ने व्यवस्था गर्नु पर्नेछ ।
तर, उक्त व्यवस्थाले प्राकृतिक व्यक्ति बाहेकका अन्य संघ, संस्था, कम्पनी लगायतका अप्राकृतिक व्यक्ति वा आर्जन हुने गरी राखिएको बचत खाता बाहेक अन्य खाता खोल्न बाधा पुर्याएको छैन ।
(७) इजाजतपत्रप्राप्त संस्थाले पाकेको मुद्दती निक्षेपको साँवा तथा ब्याज खातामा खोली मुद्दती निक्षेपमा प्रदान गरिने ब्याज र भुक्तानी अवधि (Maturity Period) पश्चात् फिर्ता हुने रकम त्यस्तो बचत खातामा अभिलेख जम्मा हुने व्यवस्था मिलाउनु पर्नेछ ।
(८) इजाजतपत्रप्राप्त संस्थाले कुनै प्राकृतिक व्यक्तिको रु. ५० लाख भन्दा बढीको मुद्दती निक्षेप स्वीकार गर्दा निक्षेपकर्ताको स्थायी लेखा नम्बर (PAN) अनिवार्य रुपमा लिनुपर्नेछ ।
(९) इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाहरुले कुनै पनि व्यक्ति, फर्म, कम्पनी र अन्य संगठित संघ संस्थाहरुलाई कुनै पनि प्रकारको निक्षेप स्वीकार गर्दा त्यस्तो रकममा निक्षेपमा दिइने अंकित ब्याजदर (Coupon Rate) बाहेक अन्य कुनै पनि प्रकारको शुल्क/कमिशन वा यसै अन्य शीर्षकबाट बैंक तथा वित्तीय संस्थालाई व्ययभार पर्ने कुनै प्रकारको आर्थिक सुविधा दिन पाइने छैन ।
Controlled English translation
(1) A licensed institution shall itself frame and implement rules and procedures concerning the term, type and all other matters relating to deposits accepted by it, and such rules and procedures shall be submitted to the Banks and Financial Institutions Regulation Department of this Bank and to the concerned Supervision Department.
(2) In the case of a savings account with no transaction, the account shall be made Dormant after three years; and in the case of a call account or current account, after more than one year has elapsed without transaction. Accounts previously made dormant under the institution’s policy shall be updated in accordance with this provision. When such an account is reactivated, where customer identification has been updated pursuant to the institution’s customer-identification policy, no document other than the concerned customer’s application shall be required. A dormant account may also be reactivated after customer identification has been updated through electronic means and arrangements have been made to confirm the same.
(3) Accounts having a zero balance and no transaction for ten years may be closed by the licensed institution after publication of a public notice. Information relating to such closure shall be made available on the bank’s website.
(4) A bank or financial institution shall, within the first month of each fiscal year, submit to this Bank particulars of accounts that have remained inactive for ten years or in respect of which no claim has been made under the Bank and Financial Institution Act, 2073. The concerned bank or financial institution shall also, once every five years, publish in a national daily newspaper a notice calling for claims to such deposit amounts and shall keep detailed information thereof on its website. Deposit amounts in respect of which no claim has been made shall be deposited in this Bank’s “Banking Development Fund”.
(5) Where, within five years from the date on which a licensed institution declares a dividend, the concerned shareholder or lawful claimant does not collect the dividend, particulars including the shareholder’s name shall be published at least once in a national newspaper within one month after the end of each fiscal year. If the dividend remains unclaimed even after publication of the notice, an “Unclaimed Dividend Account” shall be opened with the concerned institution and the amount deposited therein. Details of dividend amounts transferred in this manner shall be published half-yearly, kept on the institution’s website for three years and submitted to this Bank.
(6) A licensed institution may open savings accounts only for natural persons or associations/institutions established without a profit-making objective. Savings accounts shall not be opened for other institutions, companies or organised bodies. In addition, in accordance with accepted banking practice, the institution shall distinguish accounts for which chequebooks are issued from those for which chequebooks are not issued and arrange issuance accordingly.
However, nothing in this provision shall prevent non-natural persons, including associations, institutions and companies, from opening accounts other than an interest-bearing savings account.
(7) A licensed institution shall arrange that principal and interest of a matured fixed deposit, including the amount refundable after the Maturity Period, is credited to the relevant savings account.
(8) When a licensed institution accepts a fixed deposit exceeding NPR 5 million from a natural person, it shall mandatorily obtain the depositor’s Permanent Account Number (PAN).
(9) When a licensed bank or financial institution accepts any type of deposit from any person, firm, company or other organised association/institution, it shall not provide any charge, commission or other economic facility that creates a financial burden for the bank or financial institution in addition to the stated interest rate (Coupon Rate) payable on the deposit.
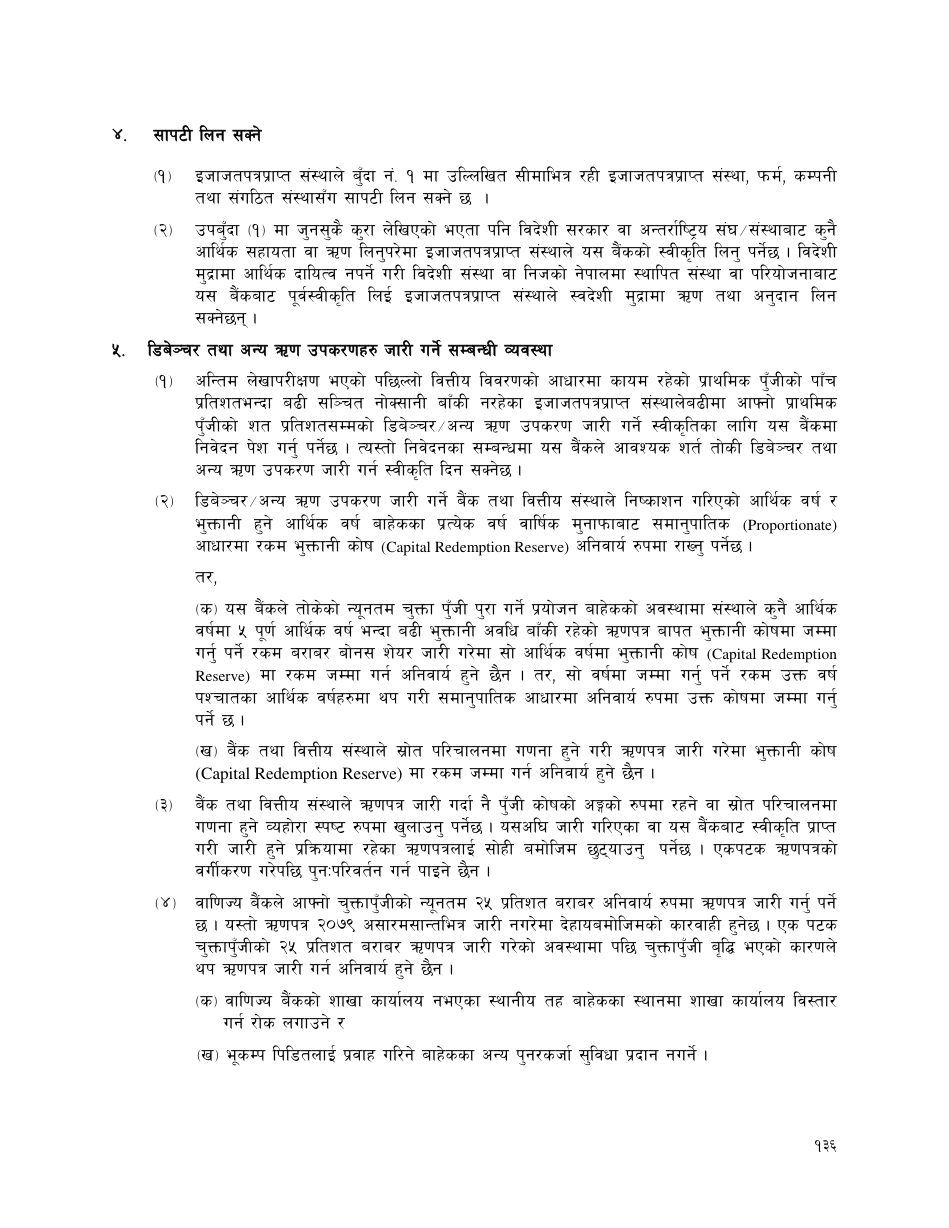
(१) इजाजतपत्रप्राप्त संस्थाले बुँदा नं. १ मा उल्लिखित सीमाभित्र रही इजाजतपत्रप्राप्त संस्था, फर्म, कम्पनी तथा संगठित संस्थासँग सापटी लिन सक्ने छ ।
(२) उपबुँदा (१) मा जुनसुकै कुरा लेखिएको भएतापनि विदेशी सरकार वा अन्तर्राष्ट्रिय संघ/संस्थाबाट कुनै आर्थिक सहायता वा ऋण लिनुपरेमा इजाजतपत्रप्राप्त संस्थाले यस बैंकको स्वीकृति लिनुपर्नेछ । विदेशी मुद्रामा आर्थिक दायित्व नपर्ने गरी विदेशी संस्था वा निजको नेपालमा स्थापित संस्था वा परियोजनाबाट यस बैंकबाट पूर्वस्वीकृति लिई इजाजतपत्रप्राप्त संस्थाले स्वदेशी मुद्रामा ऋण तथा अनुदान लिन सक्नेछ ।
Controlled English translation
(1) A licensed institution may borrow from another licensed institution, firm, company or organised institution within the limit specified in Clause 1.
(2) Notwithstanding sub-clause (1), where economic assistance or a loan is to be obtained from a foreign Government or international organisation/institution, the licensed institution shall obtain approval of this Bank. A licensed institution may, with prior approval of this Bank, obtain a loan or grant in domestic currency from a foreign institution or an institution/project established by it in Nepal, provided no foreign-currency liability arises.
(१) अन्तिम लेखापरीक्षण भएको पछिल्लो वित्तीय विवरणको आधारमा कायम रहेको प्राथमिक पुँजीको पाँच प्रतिशतभन्दा बढी सञ्चित नोक्सानी बाँकी नरहेको इजाजतपत्रप्राप्त संस्थाले आफ्नो प्राथमिक पुँजीको शत प्रतिशतसम्मको डिबेञ्चर/अन्य ऋण उपकरण जारी गर्ने स्वीकृतिका लागि यस बैंकमा निवेदन पेश गर्नु पर्नेछ । त्यस्तो निवेदनका सम्बन्धमा यस बैंकले आवश्यक शर्त तोकी डिबेञ्चर तथा अन्य ऋण उपकरण जारी गर्न स्वीकृति दिन सक्नेछ ।
(२) डिबेञ्चर/अन्य ऋण उपकरण जारी गर्ने बैंक तथा वित्तीय संस्थाले निष्काशन गरिएको आर्थिक वर्ष र भुक्तानी हुने आर्थिक वर्ष बाहेकका प्रत्येक वर्ष वार्षिक मुनाफाबाट समानुपातिक (Proportionate) आधारमा रकम भुक्तानी कोष (Capital Redemption Reserve) अनिवार्य रुपमा राख्नु पर्नेछ ।
तर,
(क) यस बैंकले तोकेको न्यूनतम चुक्ता पुँजी पूरा गर्ने प्रयोजन बाहेकको अवस्थामा संस्थाले कुनै आर्थिक वर्षमा ५ पूर्ण आर्थिक वर्ष भन्दा बढी भुक्तानी अवधि बाँकी रहेको ऋणपत्र जारी गरेको रकम बराबर बोनस शेयर जारी गरेमा सो आर्थिक वर्षमा भुक्तानी कोष (Capital Redemption Reserve) मा रकम जम्मा गर्न अनिवार्य हुने छैन । तर, सो वर्षमा जम्मा गर्नुपर्ने रकम उक्त वर्ष पश्चात्का आर्थिक वर्षहरुमा थप गरी समानुपातिक आधारमा अनिवार्य रुपमा उक्त कोषमा जम्मा गर्नु पर्नेछ ।
(ख) बैंक तथा वित्तीय संस्थाले स्रोत परिचालनमा गणना हुने गरी ऋणपत्र जारी गरेमा भुक्तानी कोष (Capital Redemption Reserve) मा रकम जम्मा गर्न अनिवार्य हुने छैन ।
(३) बैंक तथा वित्तीय संस्थाले ऋणपत्र जारी गर्दा नै पुँजी कोषको अङ्गको रुपमा रहने वा स्रोत परिचालनमा गणना हुने व्यहोरा स्पष्ट रुपमा खुलाउनु पर्नेछ । यसअघि जारी गरिएका ऋणपत्रको हकमा समेत सोही बमोजिम छुट्याउनु पर्नेछ । एकपटक ऋणपत्रको वर्गीकरण गरेपछि पुनःपरिवर्तन गर्न पाइने छैन ।
(४) वाणिज्य बैंकले आफ्नो चुक्तापुँजीको न्यूनतम २५ प्रतिशत बराबर अनिवार्य रुपमा ऋणपत्र जारी गर्नु पर्नेछ । यस्तो ऋणपत्र २०८२ असारमसान्तभित्र जारी गरिसक्नु पर्नेछ । तर एकपटक चुक्तापुँजीको २५ प्रतिशत बराबर ऋणपत्र जारी गरेको अवस्थामा पछि चुक्तापुँजी वृद्धि भएको कारणले थप ऋणपत्र जारी गर्न अनिवार्य हुने छैन ।
(क) वाणिज्य बैंकको शाखा कार्यालय नभएका स्थानीय तह बाहेकका स्थानमा शाखा कार्यालय विस्तार गर्न रोक लगाउने र
(ख) भूकम्प पीडितलाई प्रवाह गरिने बाहेकका अन्य पुनरकर्जा सुविधा प्रदान नगर्ने ।
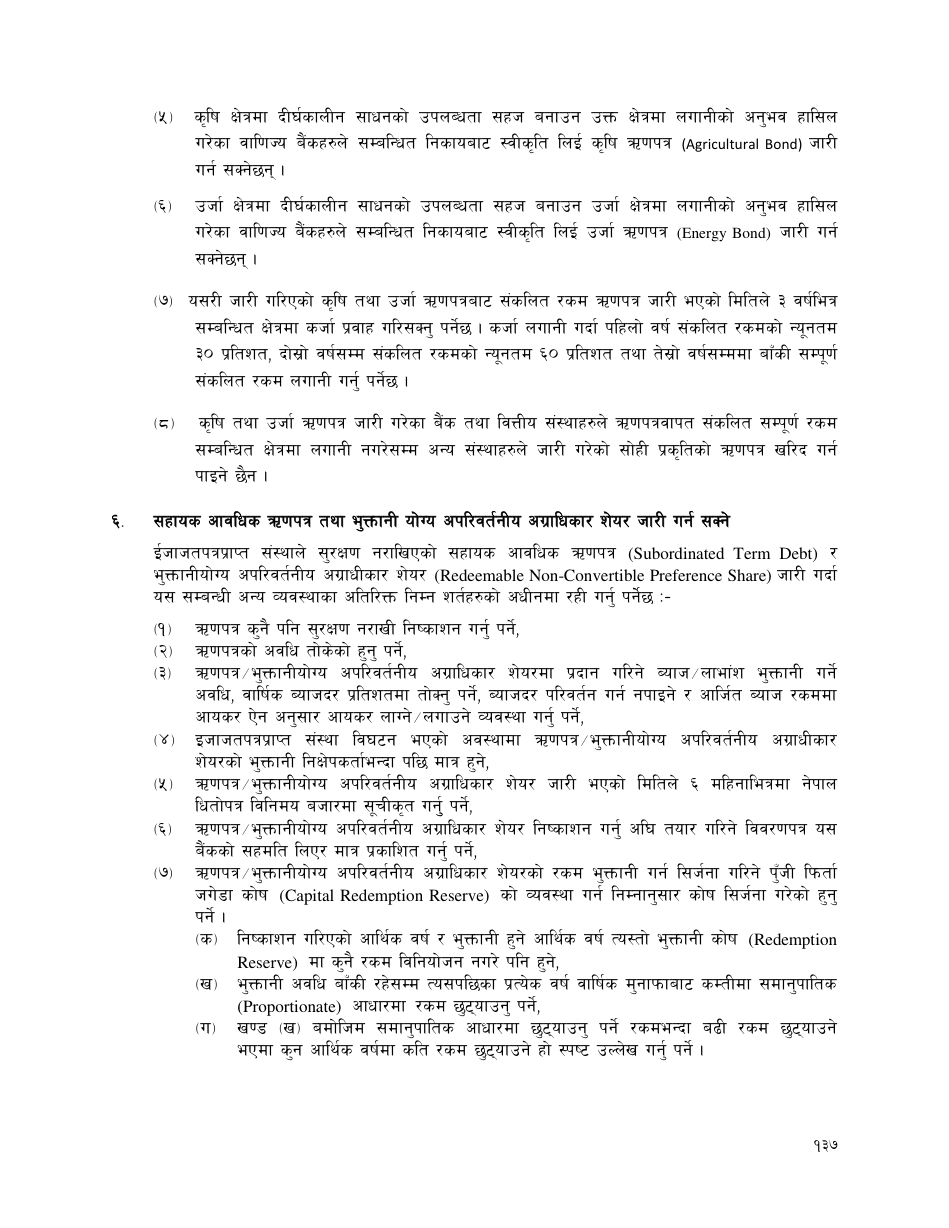
(५) कृषि क्षेत्रमा दीर्घकालीन साधनको उपलब्धता सहज बनाउन उक्त क्षेत्रमा लगानीको अनुभव हासिल गरेका वाणिज्य बैंकहरुले सम्बन्धित निकायबाट स्वीकृति लिई कृषि ऋणपत्र (Agricultural Bond) जारी गर्न सक्नेछन् ।
(६) ऊर्जा क्षेत्रमा दीर्घकालीन साधनको उपलब्धता सहज बनाउन ऊर्जा क्षेत्रमा लगानीको अनुभव हासिल गरेका वाणिज्य बैंकहरुले सम्बन्धित निकायबाट स्वीकृति लिई ऊर्जा ऋणपत्र (Energy Bond) जारी गर्न सक्नेछन् ।
(७) यसरी जारी गरिएको कृषि तथा ऊर्जा ऋणपत्रबाट संकलित रकम ऋणपत्र जारी भएको मितिले ३ वर्षभित्र सम्बन्धित क्षेत्रमा कर्जा प्रवाह गरिसक्नु पर्नेछ । कर्जा लगानी गर्दा पहिलो वर्ष संकलित रकमको न्यूनतम ३० प्रतिशत, दोस्रो वर्षसम्म संकलित रकमको न्यूनतम ६० प्रतिशत तथा तेस्रो वर्षसम्ममा बाँकी सम्पूर्ण संकलित रकम लगानी गर्नु पर्नेछ ।
(८) कृषि तथा ऊर्जा ऋणपत्र जारी गरेका बैंक तथा वित्तीय संस्थाहरुले ऋणपत्रबापत संकलित सम्पूर्ण रकम सम्बन्धित क्षेत्रमा लगानी नगरिसकेसम्म अन्य संस्थाहरुले जारी गरेको सोही प्रकृतिको ऋणपत्र खरिद गर्न पाउने छैन ।
Controlled English translation
(1) A licensed institution whose accumulated loss, on the basis of its latest audited financial statements, does not exceed five percent of its Tier 1 capital may apply to this Bank for approval to issue debentures/other debt instruments up to one hundred percent of its Tier 1 capital. This Bank may grant approval to issue such debentures or other debt instruments subject to necessary conditions.
(2) A bank or financial institution issuing debentures/other debt instruments shall, in each year other than the year of issue and the year of redemption, mandatorily appropriate from annual profit to a Capital Redemption Reserve on a Proportionate basis.
However:
(a) except where the purpose is to meet the minimum paid-up capital prescribed by this Bank, if in any fiscal year the institution issues bonus shares equal to the amount of a debenture whose remaining maturity exceeds five full fiscal years, it shall not be mandatory to deposit the amount in the Capital Redemption Reserve in that fiscal year. The amount that would otherwise have been deposited shall, however, be added to and mandatorily deposited in the Reserve on a proportionate basis in subsequent fiscal years;
(b) where a bank or financial institution issues a debenture that is counted toward resource mobilisation, depositing an amount in the Capital Redemption Reserve shall not be mandatory.
(3) At the time a bank or financial institution issues a debenture, it shall clearly state whether the debenture will form part of the capital fund or be counted toward resource mobilisation. Previously issued debentures shall also be separated/classified accordingly. Once classified, a debenture shall not subsequently be reclassified.
(4) A commercial bank shall mandatorily issue debentures equal to at least 25 percent of its paid-up capital. Such debentures shall be issued by the end of Ashadh 2082. Where debentures equal to 25 percent of the then paid-up capital have once been issued, a subsequent increase in paid-up capital shall not make further issuance mandatory solely on that account.
(a) branch expansion shall be prohibited at locations other than Local Levels without a commercial-bank branch; and
(b) refinance facilities other than those provided to earthquake-affected persons shall not be granted.
(5) To facilitate the availability of long-term resources in agriculture, commercial banks having experience in lending to the sector may, with approval of the concerned authority, issue Agricultural Bonds.
(6) To facilitate the availability of long-term resources in energy, commercial banks having experience in lending to the energy sector may, with approval of the concerned authority, issue Energy Bonds.
(7) Amounts collected through Agricultural and Energy Bonds shall be lent to the relevant sector within three years from the date of issue. At least 30 percent of the amount collected shall be invested in the first year, at least 60 percent cumulatively by the end of the second year, and the entire remaining amount by the end of the third year.
(8) Until the full amount collected through Agricultural or Energy Bonds has been invested in the relevant sector, a bank or financial institution that issued such bonds shall not purchase bonds of the same nature issued by another institution.
इजाजतपत्रप्राप्त संस्थाले सुरक्षण नराखिएको सहायक आवधिक ऋणपत्र (Subordinated Term Debt) र भुक्तानीयोग्य अपरिवर्तनीय अग्राधिकार शेयर (Redeemable Non-Convertible Preference Share) जारी गर्दा यस सम्बन्धी अन्य व्यवस्थाका अतिरिक्त निम्न शर्तहरुको अधीनमा रही गर्नु पर्नेछ:
(१) ऋणपत्र कुनै पनि सुरक्षण नराखी निष्काशन गर्नु पर्ने,
(२) ऋणपत्रको अवधि तोकिएको हुनु पर्ने,
(३) ऋणपत्र/भुक्तानीयोग्य अपरिवर्तनीय अग्राधिकार शेयरमा प्रदान गरिने ब्याज/लाभांश भुक्तानी गर्ने अवधि, वार्षिक ब्याजदर प्रतिशतमा तोक्नु पर्ने, ब्याजदर परिवर्तन गर्न नपाइने र आर्जित ब्याज रकममा आयकर ऐन अनुसार आयकर लाग्ने/लगाउने व्यवस्था गर्नु पर्ने,
(४) इजाजतपत्रप्राप्त संस्था विघटन भएको अवस्थामा ऋणपत्र/भुक्तानीयोग्य अपरिवर्तनीय अग्राधिकार शेयरको भुक्तानी निक्षेपकर्ताभन्दा पछि मात्र हुने,
(५) ऋणपत्र/भुक्तानीयोग्य अपरिवर्तनीय अग्राधिकार शेयर जारी भएको मितिले ६ महिनाभित्रमा नेपाल धितोपत्र विनिमय बजारमा सूचीकृत गर्नु पर्ने,
(६) ऋणपत्र/भुक्तानीयोग्य अपरिवर्तनीय अग्राधिकार शेयर निष्काशन गर्न अघि तयार गरिने विवरणपत्र यस बैंकको सहमति लिएर मात्र प्रकाशित गर्नु पर्ने,
(७) ऋणपत्र/भुक्तानीयोग्य अपरिवर्तनीय अग्राधिकार शेयरको रकम भुक्तानी गर्न सिर्जना गरिने पुँजी फिर्ता जगेडा कोष (Capital Redemption Reserve) को व्यवस्था गर्न निम्नानुसार कोष सिर्जना गरेको हुनु पर्ने:
(क) निष्काशन गरिएको आर्थिक वर्ष र भुक्तानी हुने आर्थिक वर्ष त्यस्तो भुक्तानी कोष (Redemption Reserve) मा कुनै रकम विनियोजन नगरे पनि हुने,
(ख) भुक्तानी अवधि बाँकी रहेका प्रत्येक वर्ष वार्षिक मुनाफाबाट कम्तीमा समानुपातिक (Proportionate) आधारमा रकम छुट्याउनु पर्ने,
(ग) खण्ड (ख) बमोजिम समानुपातिक आधारमा छुट्याउनु पर्ने रकमभन्दा बढी रकम छुट्याउने भएमा जुन आर्थिक वर्षमा कोष रकम छुट्याउने हो स्पष्ट उल्लेख गर्नु पर्नेछ ।
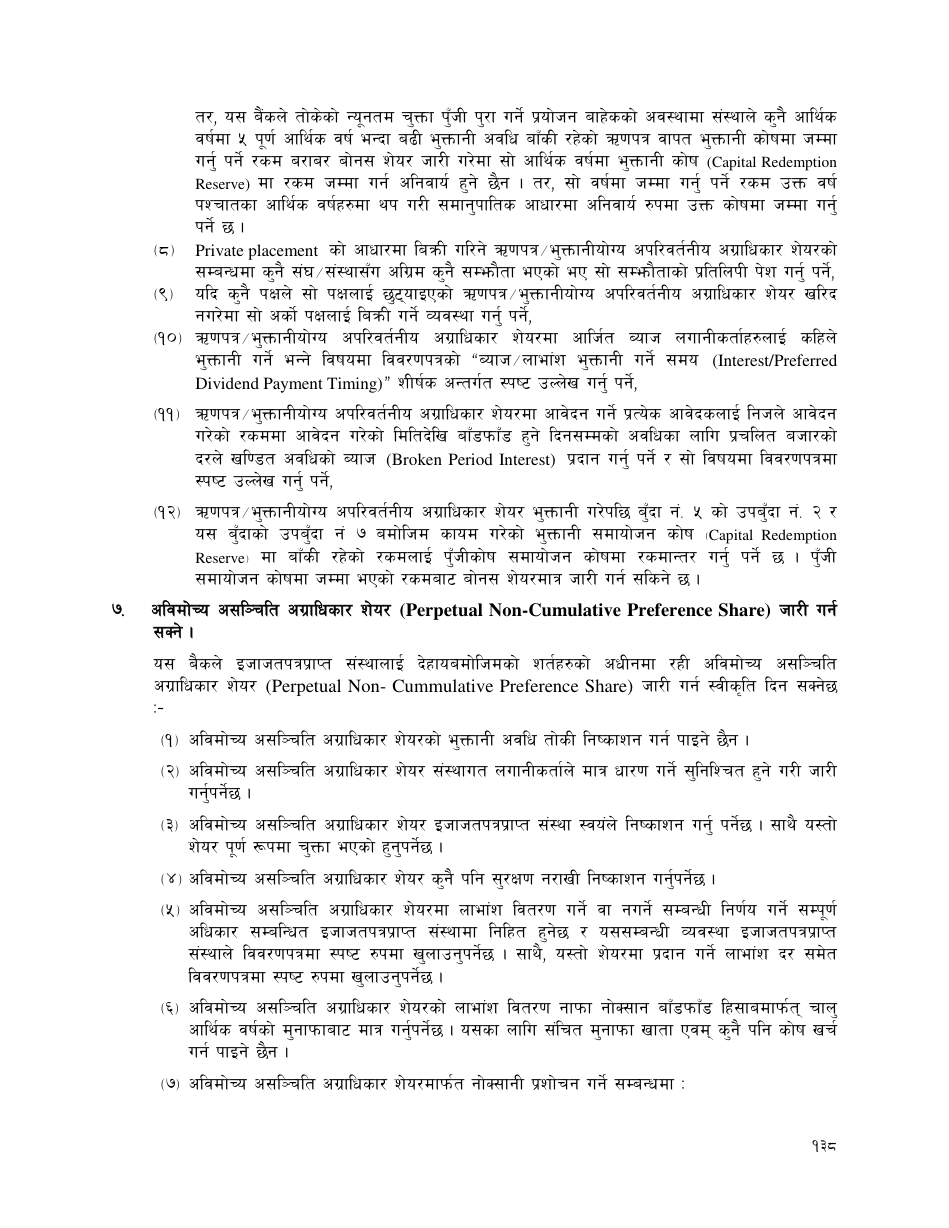
तर, यस बैंकले तोकेको न्यूनतम चुक्ता पुँजी पूरा गर्ने प्रयोजन बाहेकको अवस्थामा संस्थाले कुनै आर्थिक वर्षमा ५ पूर्ण आर्थिक वर्ष भन्दा बढी भुक्तानी अवधि बाँकी रहेको ऋणपत्र वापत भुक्तानी कोषमा जम्मा गर्नु पर्ने रकम बराबर बोनस शेयर जारी गरेमा सो आर्थिक वर्षमा भुक्तानी कोष (Capital Redemption Reserve) मा रकम जम्मा गर्न अनिवार्य हुने छैन । तर, सो वर्षमा जम्मा गर्नु पर्ने रकम उक्त वर्ष पश्चात्का आर्थिक वर्षहरुमा थप गरी समानुपातिक आधारमा अनिवार्य रुपमा उक्त कोषमा जम्मा गर्नु पर्नेछ ।
(८) Private placement को आधारमा बिक्री गरिने ऋणपत्र/भुक्तानीयोग्य अपरिवर्तनीय अग्राधिकार शेयरको सम्बन्धमा कुनै संघ/संस्थासँग अग्रिम कुनै सम्झौता भएको भए सो सम्झौताको प्रतिलिपि पेश गर्नु पर्ने,
(९) यदि कुनै पक्षले सो पक्षलाई छुट्याइएको ऋणपत्र/भुक्तानीयोग्य अपरिवर्तनीय अग्राधिकार शेयर खरिद नगरेमा सो ऋणपत्र खुल्लाई बिक्री गर्ने व्यवस्था गर्नु पर्ने,
(१०) ऋणपत्र/भुक्तानीयोग्य अपरिवर्तनीय अग्राधिकार शेयरमा आर्जित ब्याज लगानीकर्ताहरुलाई कहिले भुक्तानी गर्ने भन्ने विषयमा विवरणपत्रको “ब्याज/लाभांश भुक्तानी गर्ने समय (Interest/Preferred Dividend Payment Timing)” शीर्षक अन्तर्गत स्पष्ट उल्लेख गर्नु पर्ने,
(११) ऋणपत्र/भुक्तानीयोग्य अपरिवर्तनीय अग्राधिकार शेयरमा आवेदन गर्ने प्रत्येक आवेदकलाई निजले आवेदन गरेको रकममा आवेदन गरेको मितिदेखि बाँडफाँड हुने दिनसम्मको अवधिका लागि प्रचलित बजारको दरले खण्डित अवधिको ब्याज (Broken Period Interest) प्रदान गर्नु पर्ने र सो विषयमा विवरणपत्रमा स्पष्ट उल्लेख गर्नु पर्ने,
(१२) ऋणपत्र/भुक्तानीयोग्य अपरिवर्तनीय अग्राधिकार शेयर भुक्तानी गरेपछि बुँदा नं. ५ को उपबुँदा नं. २ र यस बुँदाको उपबुँदा नं. ७ बमोजिम कायम गरेको भुक्तानी कोषमा बाँकी रहेको रकमलाई पुँजीकोष समायोजन कोषमा रकमान्तर गर्नु पर्नेछ । पुँजी समायोजन कोषमा जम्मा भएको रकमबाट बोनस शेयरमात्र जारी गर्न सकिने छ ।
Controlled English translation
When issuing unsecured Subordinated Term Debt and Redeemable Non-Convertible Preference Shares, a licensed institution shall, in addition to other applicable provisions, comply with the following conditions:
(1) the debt instrument shall be issued without any security;
(2) the maturity of the debt instrument shall be specified;
(3) the period for payment of interest/dividend on the debt instrument or Redeemable Non-Convertible Preference Shares and the annual interest rate in percentage terms shall be specified; the interest rate shall not be changed; and income tax on accrued interest shall be applied in accordance with the Income Tax Act;
(4) in the event of liquidation of the licensed institution, payment of the debt instrument/Redeemable Non-Convertible Preference Shares shall be made only after depositors have been paid;
(5) the debt instrument/Redeemable Non-Convertible Preference Shares shall be listed on the Nepal securities exchange within six months from the date of issue;
(6) the prospectus prepared before issuance shall be published only after obtaining the consent of this Bank;
(7) a Capital Redemption Reserve for repayment shall be created as follows:
(a) no amount need be appropriated in the fiscal year of issue or the fiscal year of redemption;
(b) in each year in which the instrument remains outstanding, at least a proportionate amount shall be appropriated from annual profit;
(c) where an amount exceeding the proportionate amount under paragraph (b) is to be appropriated, the fiscal year in which such amount will be appropriated shall be clearly stated.
However, except where the purpose is to meet the minimum paid-up capital prescribed by this Bank, if in any fiscal year the institution issues bonus shares equal to the amount otherwise required to be deposited in the Capital Redemption Reserve in respect of a debt instrument having more than five full fiscal years remaining to maturity, it shall not be mandatory to deposit such amount in the Reserve in that fiscal year. The amount shall, however, be added to and deposited on a proportionate basis in subsequent fiscal years.
(8) where an instrument is to be sold by Private Placement and any prior agreement has been entered into with an association/institution, a copy of that agreement shall be submitted;
(9) where a party does not purchase the instrument allotted to it, arrangements shall be made to offer it for open sale;
(10) the prospectus shall clearly state, under “Interest/Preferred Dividend Payment Timing”, when accrued interest will be paid to investors;
(11) each applicant shall be paid Broken Period Interest, at the prevailing market rate, on the amount applied for from the date of application until the date of allotment, and this shall be clearly stated in the prospectus;
(12) after redemption, the amount remaining in the reserve maintained pursuant to Clause 5(2) and sub-clause (7) of this Clause shall be transferred to the Capital Adjustment Reserve. Only bonus shares may be issued from amounts deposited in the Capital Adjustment Reserve.
यस बैंकले इजाजतपत्रप्राप्त संस्थालाई देहायबमोजिमका शर्तहरुको अधीनमा रही अविमोच्य असञ्चित अग्राधिकार शेयर (Perpetual Non-Cumulative Preference Share) जारी गर्न स्वीकृति दिन सक्नेछ:
(१) अविमोच्य असञ्चित अग्राधिकार शेयरको भुक्तानी अवधि तोकी निष्काशन गर्न पाइने छैन ।
(२) अविमोच्य असञ्चित अग्राधिकार शेयर संस्थागत लगानीकर्ताले मात्र धारण गर्ने सुनिश्चित हुने गरी जारी गर्नुपर्नेछ ।
(३) अविमोच्य असञ्चित अग्राधिकार शेयर इजाजतपत्रप्राप्त संस्था स्वयंले निष्काशन गर्नुपर्नेछ । साथै यस्तो शेयर पूर्ण रुपमा चुक्ता भएको हुनुपर्नेछ ।
(४) अविमोच्य असञ्चित अग्राधिकार शेयर कुनै पनि सुरक्षण नराखी निष्काशन गर्नुपर्नेछ ।
(५) अविमोच्य असञ्चित अग्राधिकार शेयरमा लाभांश वितरण गर्ने वा नगर्ने सम्बन्धी निर्णय गर्ने सम्पूर्ण अधिकार सम्बन्धित इजाजतपत्रप्राप्त संस्थामा निहित हुनेछ र यससम्बन्धी व्यवस्था इजाजतपत्रप्राप्त संस्थाले विवरणपत्रमा स्पष्ट रुपमा खुलाउनुपर्नेछ । साथै, यस्तो शेयरमा प्रदान गर्ने लाभांश दर समेत विवरणपत्रमा स्पष्ट रुपमा खुलाउनुपर्नेछ ।
(६) अविमोच्य असञ्चित अग्राधिकार शेयरको लाभांश वितरण नाफा नोक्सान बाँडफाँड हिसाबमार्फत चालु आर्थिक वर्षको मुनाफाबाट मात्र गर्नुपर्नेछ । यसका लागि सञ्चित मुनाफा खाता एवम् कुनै पनि कोष खर्च गर्न पाइने छैन ।
(७) अविमोच्य असञ्चित अग्राधिकार शेयरमार्फत नोक्सानी प्रशोचन गर्ने सम्बन्धमा:
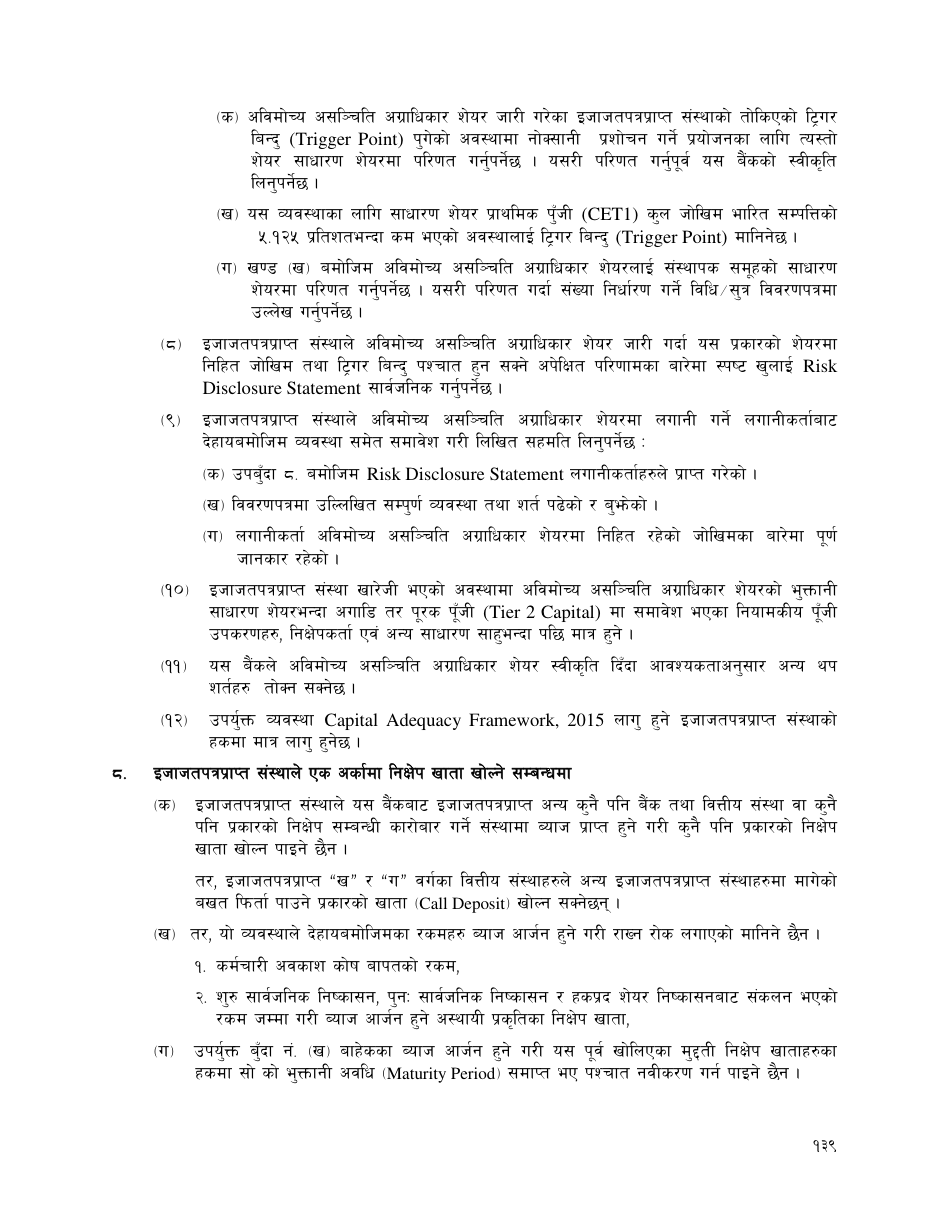
(क) अविमोच्य असञ्चित अग्राधिकार शेयर जारी गरेको इजाजतपत्रप्राप्त संस्थाको तोकिएको ट्रिगर बिन्दु (Trigger Point) पुगेको अवस्थामा नोक्सानी प्रशोचन गर्ने प्रयोजनका लागि त्यस्तो शेयर साधारण शेयरमा परिणत गर्नुपर्नेछ । यसरी परिणत गर्नु अघि यस बैंकको स्वीकृति लिनुपर्नेछ ।
(ख) यस व्यवस्थाको लागि साधारण शेयर प्राथमिक पुँजी (CET1) कुल जोखिम भारित सम्पत्तिको ५.१२५ प्रतिशतभन्दा कम भएको अवस्थालाई ट्रिगर बिन्दु (Trigger Point) मानिनेछ ।
(ग) खण्ड (ख) बमोजिम अविमोच्य असञ्चित अग्राधिकार शेयरलाई संस्थापक समूहको साधारण शेयरमा परिणत गर्नुपर्नेछ । यसरी परिणत गर्दा संख्या निर्धारण गर्ने विधि/सूत्र विवरणपत्रमा उल्लेख गर्नुपर्नेछ ।
(८) इजाजतपत्रप्राप्त संस्थाले अविमोच्य असञ्चित अग्राधिकार शेयर जारी गर्दा यस प्रकारको शेयरमा निहित जोखिम तथा ट्रिगर बिन्दु पश्चात हुन सक्ने अपेक्षित परिणामका बारेमा स्पष्ट खुलाइ Risk Disclosure Statement सार्वजनिक गर्नुपर्नेछ ।
(९) इजाजतपत्रप्राप्त संस्थाले अविमोच्य असञ्चित अग्राधिकार शेयरमा लगानी गर्ने लगानीकर्ताबाट देहायबमोजिम व्यहोरा समेत समावेश गरी लिखित सहमति लिनुपर्नेछ:
(क) उपबुँदा ८ बमोजिम Risk Disclosure Statement लगानीकर्ताले प्राप्त गरेको,
(ख) विवरणपत्रमा उल्लिखित सम्पूर्ण व्यवस्था तथा शर्त पढेको र बुझेको,
(ग) लगानीकर्ता अविमोच्य असञ्चित अग्राधिकार शेयरमा निहित जोखिमका बारेमा पूर्ण जानकार रहेको ।
(१०) इजाजतपत्रप्राप्त संस्था खारेजी भएको अवस्थामा अविमोच्य असञ्चित अग्राधिकार शेयरको भुक्तानी साधारण शेयरभन्दा अगाडि तर पूरक पुँजी (Tier 2 Capital) मा समावेश भएका नियामकीय पुँजी उपकरणहरु, निक्षेपकर्ता एवं अन्य साधारण साहुभन्दा पछि मात्र हुने ।
(११) यस बैंकले अविमोच्य असञ्चित अग्राधिकार शेयर स्वीकृति दिंदा आवश्यकतानुसार अन्य थप शर्तहरु तोक्न सक्नेछ ।
(१२) उपर्युक्त व्यवस्था Capital Adequacy Framework, 2015 लागू हुने इजाजतपत्रप्राप्त संस्थाको हकमा मात्र लागू हुनेछ ।
Controlled English translation
This Bank may grant approval to a licensed institution to issue Perpetual Non-Cumulative Preference Shares subject to the following conditions:
(1) such shares shall not be issued with a specified redemption period;
(2) they shall be issued in a manner ensuring that only institutional investors hold them;
(3) they shall be issued by the licensed institution itself and shall be fully paid-up;
(4) they shall be issued without security;
(5) the entire authority to decide whether or not to distribute dividends shall vest in the concerned licensed institution, and this arrangement and the dividend rate shall be clearly disclosed in the prospectus;
(6) dividends shall be distributed only from the profit of the current fiscal year through the profit-and-loss appropriation account. Retained earnings or any reserve shall not be used;
(7) loss absorption:
(a) when the prescribed Trigger Point is reached, the shares shall be converted into ordinary shares for loss absorption, with prior approval of this Bank;
(b) the Trigger Point shall be the condition in which Common Equity Tier 1 (CET1) falls below 5.125 percent of total risk-weighted assets;
(c) the shares shall be converted into ordinary shares of the promoter group and the method/formula for determining the number of shares shall be stated in the prospectus;
(8) the institution shall publicly issue a Risk Disclosure Statement clearly disclosing the risks and expected consequences after the Trigger Point;
(9) the institution shall obtain written consent from each investor confirming that the investor has received the Risk Disclosure Statement, read and understood all provisions and conditions in the prospectus, and is fully aware of the risks;
(10) in liquidation, payment shall rank ahead of ordinary shares but after regulatory capital instruments included in Tier 2 Capital, depositors and other ordinary creditors;
(11) this Bank may prescribe additional conditions as necessary;
(12) these provisions shall apply only to licensed institutions to which the Capital Adequacy Framework, 2015 applies.
(क) इजाजतपत्रप्राप्त संस्थाले यस बैंकबाट इजाजतपत्रप्राप्त अन्य कुनै पनि बैंक तथा वित्तीय संस्था वा कुनै पनि प्रकारको निक्षेप सम्बन्धी कारोबार गर्ने संस्थामा ब्याज प्राप्त हुने गरी कुनै पनि प्रकारको निक्षेप खाता खोल्न पाउने छैन ।
तर, इजाजतपत्रप्राप्त “ख” र “ग” वर्गका वित्तीय संस्थाहरुले अन्य इजाजतपत्रप्राप्त संस्थाहरुमा मागेको बखत फिर्ता पाउने प्रकारको खाता (Call Deposit) खोल्न सक्नेछन् ।
(ख) यो व्यवस्थाले देहायबमोजिमका रकमहरु ब्याज आर्जन हुने गरी राख्न रोक लगाएको मानिने छैन:
१. कर्मचारी अवकाश कोष वापतको रकम,
२. शुरु सार्वजनिक निष्काशन, पुनः सार्वजनिक निष्काशन र हकप्रद शेयर निष्काशनबाट संकलन भएको रकम जम्मा गरी ब्याज आर्जन हुने गरी राखिएको निक्षेप खाता ।
(ग) उपर्युक्त बुँदा नं. (ख) बाहेकका ब्याज आर्जन हुने गरी यस पूर्व खोलिएका मुद्दती निक्षेप खाताहरुको हकमा सो को भुक्तानी अवधि (Maturity Period) समाप्त भए पश्चात् नवीकरण गर्न पाइने छैन ।
Controlled English translation
(a) A licensed institution shall not open with any other bank or financial institution licensed by this Bank, or with any institution carrying out deposit business, any deposit account on which interest is earned.
However, Class “B” and “C” licensed financial institutions may open with other licensed institutions a Call Deposit account repayable on demand.
(b) This provision shall not prohibit placing the following amounts in interest-bearing accounts:
1. amounts relating to employee retirement funds;
2. amounts collected from an Initial Public Offering, Further Public Offering or rights-share issue and deposited in an interest-bearing deposit account.
(c) Interest-bearing fixed-deposit accounts previously opened, other than those under paragraph (b), shall not be renewed after expiry of their Maturity Period.
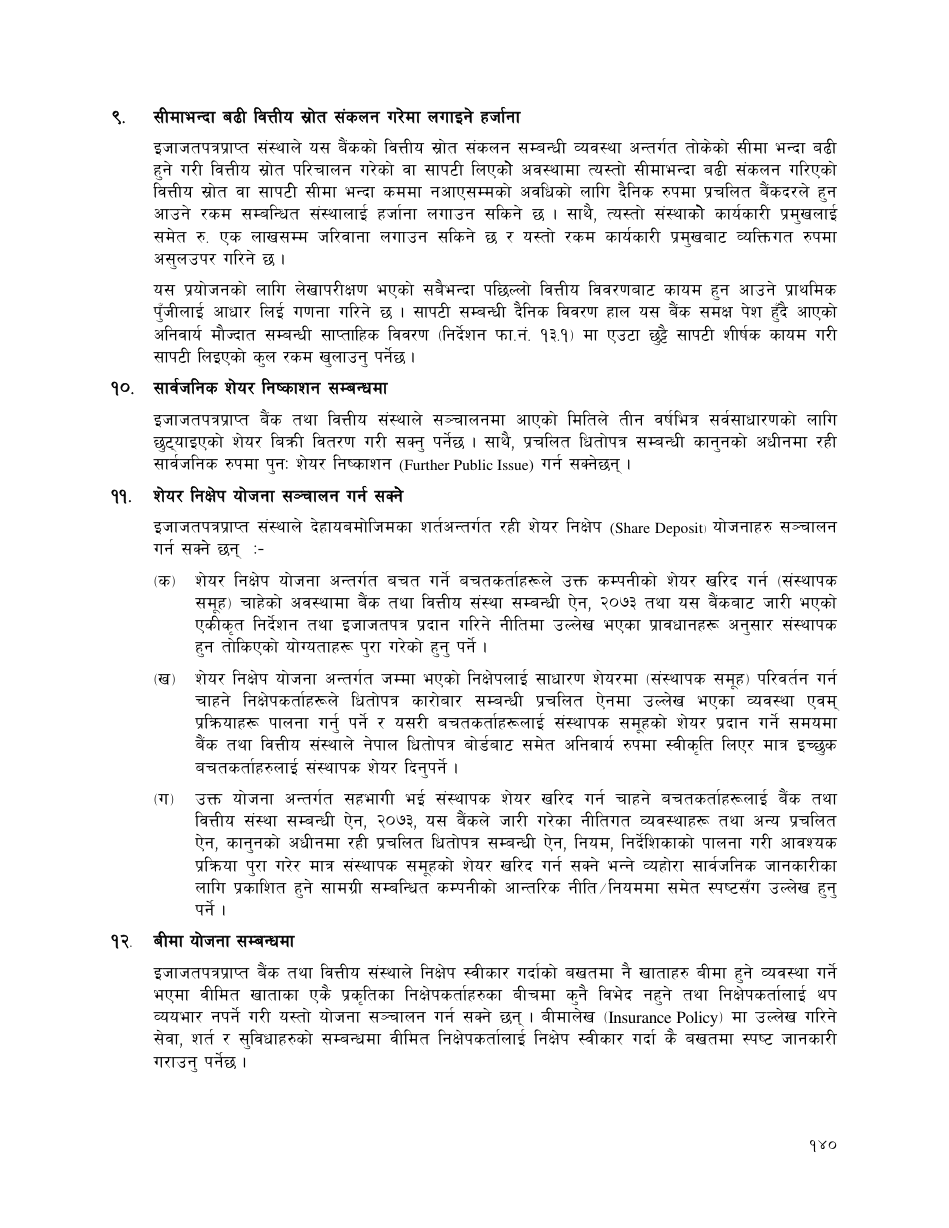
इजाजतपत्रप्राप्त संस्थाले यस बैंकको वित्तीय स्रोत संकलन सम्बन्धी व्यवस्था अन्तर्गत तोकिएको सीमा भन्दा बढी हुने गरी वित्तीय स्रोत परिचालन गरेको वा सापटी लिएको अवस्थामा त्यस्तो सीमाभन्दा बढी संकलन गरिएको निक्षेप स्रोत वा सापटी सीमामा नल्याएसम्मको अवधिको लागि दैनिक रुपमा प्रचलित बैंकदरले हुन आउने रकम सम्बन्धित संस्थालाई हर्जाना लगाउन सकिने छ । साथै, त्यस्तो संस्थाको कार्यकारी प्रमुखलाई समेत रु. एक लाखसम्म जरिवाना लगाउन सकिने छ र यस्तो रकम कार्यकारी प्रमुखबाट व्यक्तिगत रुपमा असुलउपर गरिने छ ।
यस प्रयोजनको लागि लेखापरीक्षण भएको सबैभन्दा पछिल्लो वित्तीय विवरणबाट कायम हुन आउने प्राथमिक पुँजीलाई आधार लिई गणना गरिने छ । सापटी सम्बन्धी दैनिक विवरण हाल यस बैंक समक्ष पेश भइरहेको अनिवार्य मौज्दात सम्बन्धी साप्ताहिक विवरण (निर्देशन फा.नं. १३.१) मा एउटा छुट्टै सापटी शीर्षक कायम गरी सापटी लिएको कुल रकम खुलाउनु पर्नेछ ।
Controlled English translation
Where a licensed institution mobilises financial resources or obtains borrowings in excess of the limit prescribed under this Bank’s financial-resource mobilisation provisions, the concerned institution may be charged a penalty, for each day until the excess deposit resources or borrowings are brought within the prescribed limit, calculated at the prevailing Bank Rate on the excess amount. In addition, the Chief Executive may be fined up to NPR 100,000, and such fine shall be recovered personally from the Chief Executive.
For this purpose, the Tier 1 capital derived from the latest audited financial statements shall be used as the basis of calculation. The daily statement of borrowings shall be disclosed by adding a separate borrowing heading to the compulsory-reserve weekly statement (Directive Form No. 13.1) currently submitted to this Bank, showing the total amount borrowed.
इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्था सञ्चालनमा आएको मितिले तीन वर्षभित्र सर्वसाधारणको लागि छुट्याइएको शेयर बिक्री वितरण गरी सक्नुपर्नेछ । साथै, चुक्तापुँजी वृद्धि प्रयोजनको लागि सर्वसाधारणलाई थप सार्वजनिक रुपमा पुनः शेयर निष्काशन (Further Public Issue) गर्न सक्नेछन् ।
Controlled English translation
A licensed bank or financial institution shall complete sale and distribution of shares allocated to the public within three years from the date on which it commenced operations. It may also make a Further Public Issue of shares to the public for the purpose of increasing paid-up capital.
इजाजतपत्रप्राप्त संस्थाले देहायबमोजिमका शर्तअन्तर्गत रही शेयर निक्षेप (Share Deposit) योजनाहरु सञ्चालन गर्न सक्ने छन्:
(क) शेयर निक्षेप योजना अन्तर्गत बचत गर्ने बचतकर्ताहरुले उक्त कम्पनीको शेयर खरिद गर्न (संस्थापक समेत) चाहेको अवस्थामा बैंक तथा वित्तीय संस्था सम्बन्धी ऐन, २०७३ तथा यस बैंकबाट जारी भएको एकीकृत निर्देशन तथा इजाजतपत्र प्रदान गरिने नीतिमा उल्लेख भएका प्रावधानहरु अनुसार संस्थापक हुन तोकिएको योग्यताहरु पूरा गरेको हुनु पर्ने ।
(ख) शेयर निक्षेप योजना अन्तर्गत जम्मा भएको निक्षेपलाई साधारण शेयरमा (संस्थापक समूह) परिवर्तन गर्न चाहने निक्षेपकर्ताहरुले विगतमा कारोबार गरिरहेका छन् वा हाल कायम ग्राहक भएका वा पूरा प्रक्रियाहरु पालना गर्नु पर्ने र यस्ता बचतकर्ताहरुलाई संस्थापक समूहको शेयर प्रदान गर्ने सम्बन्धमा बैंक तथा वित्तीय संस्थाले नेपाल धितोपत्र बोर्डबाट समेत अनिवार्य रुपमा स्वीकृति लिएर मात्र इच्छुक बचतकर्ताहरुलाई संस्थापक शेयर दिनुपर्ने ।
(ग) उक्त योजना अन्तर्गत सहभागी भई संस्थापक शेयर खरिद गर्न चाहने बचतकर्ताहरुलाई बैंक तथा वित्तीय संस्था सम्बन्धी ऐन, २०७३, यस बैंकले जारी गरेको एकीकृत निर्देशन तथा अन्य प्रचलित ऐन, कानुनको अधीनमा रही प्रचलित धितोपत्र सम्बन्धी ऐन, नियम, निर्देशिकाको पालना गरी आवश्यक प्रक्रिया पूरा गरेर मात्र संस्थापक समूहको शेयर खरिद गर्न सक्ने भन्ने व्यहोरा सार्वजनिक जानकारीका लागि प्रकाशित हुने सामग्रीमा उल्लेख भएको हुनुपर्ने ।
Controlled English translation
A licensed institution may operate Share Deposit schemes subject to the following conditions:
(a) where depositors under a Share Deposit scheme wish to purchase shares of the company, including promoter shares, they shall fulfil the qualifications prescribed for becoming promoters under the Bank and Financial Institution Act, 2073, the Unified Directives issued by this Bank and the applicable licensing policy;
(b) depositors wishing to convert deposits under a Share Deposit scheme into ordinary shares of the promoter group shall comply with the required procedures. In relation to providing promoter-group shares to such depositors, the bank or financial institution shall obtain mandatory approval from the Securities Board of Nepal before providing promoter shares to interested depositors;
(c) materials published for public information shall state that a depositor participating in the scheme who wishes to purchase promoter shares may do so only after completing the required procedures in compliance with the Bank and Financial Institution Act, 2073, the Unified Directives issued by this Bank, other prevailing laws, and applicable securities laws, rules and directives.
इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाले निक्षेप स्वीकार गर्दाको बखतमा नै खाताहरु बीमा हुने व्यवस्था गर्ने भएमा बीमित खाताका एकै प्रकृतिका निक्षेपकर्ताहरुका बीचमा कुनै विभेद नहुने तथा निक्षेपकर्तालाई थप व्ययभार नपर्ने गरी यस्तो योजना सञ्चालन गर्न सक्नेछन् । बीमा पोलिसी (Insurance Policy) मा उल्लिखित गरिने सेवा, शर्त र सुविधाहरुको सम्बन्धमा बीमित निक्षेपकर्तालाई निक्षेप स्वीकार गर्दा कै बखतमा स्पष्ट जानकारी गराउनु पर्नेछ ।
Controlled English translation
A licensed bank or financial institution may operate an insurance scheme for deposit accounts at the time deposits are accepted, provided there is no discrimination among depositors of the same class of insured accounts and no additional financial burden is imposed on depositors. The insured depositor shall, at the time the deposit is accepted, be clearly informed of the services, conditions and facilities stated in the Insurance Policy.
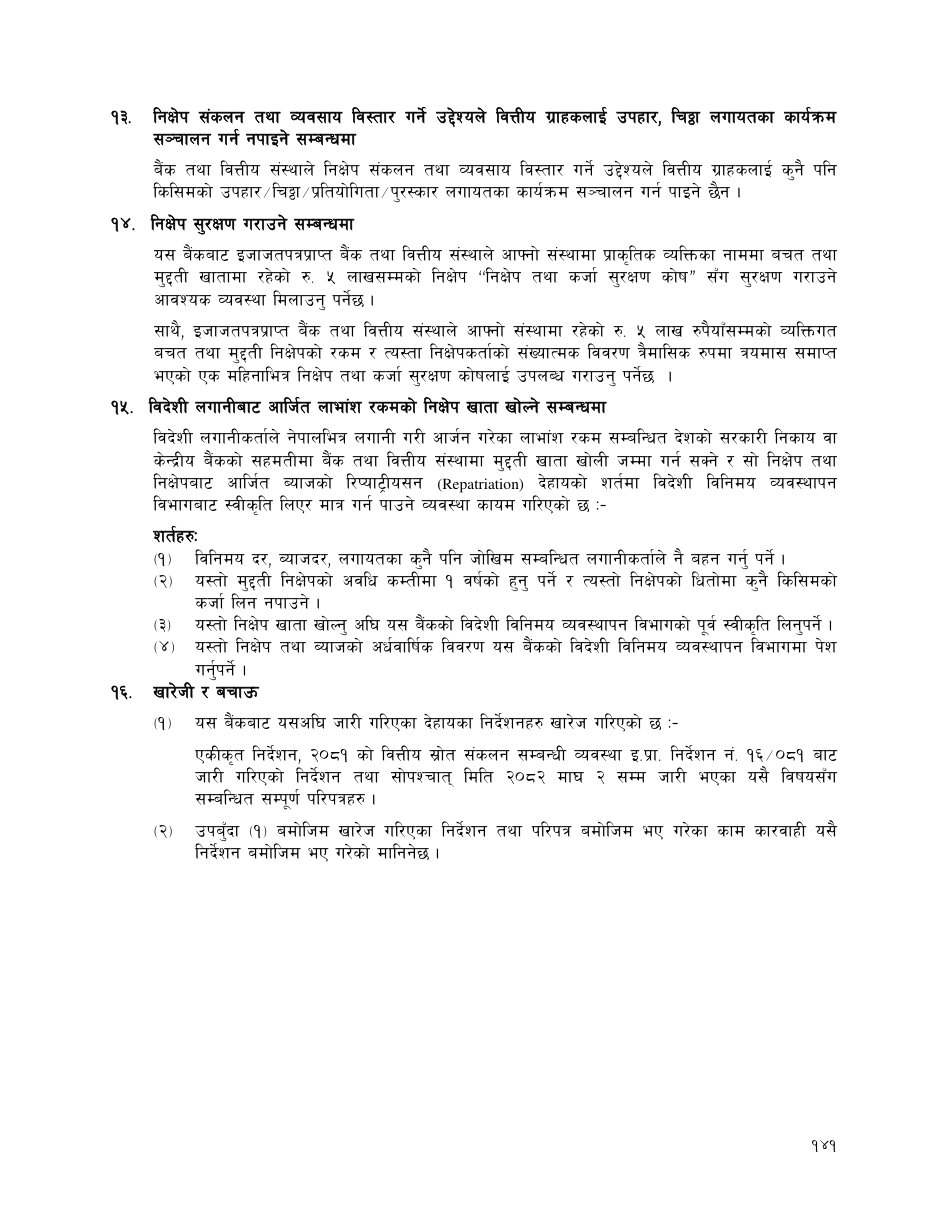
बैंक तथा वित्तीय संस्थाले निक्षेप संकलन तथा व्यवसाय विस्तार गर्ने उद्देश्यले वित्तीय ग्राहकलाई कुनै पनि किसिमको उपहार/चिठ्ठा/प्रतियोगिता/पुरस्कार लगायतका कार्यक्रम सञ्चालन गर्न पाउने छैन ।
Controlled English translation
A bank or financial institution shall not operate any programme involving gifts, lotteries, competitions, prizes or similar benefits for financial customers for the purpose of mobilising deposits or expanding business.
यस बैंकबाट इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाले आफ्नो संस्थामा प्राकृतिक व्यक्तिका नाममा बचत तथा मुद्दती खातामा रहेको रु. ५ लाखसम्मको निक्षेप निक्षेप तथा कर्जा सुरक्षण कोषसँग सुरक्षण गराउने आवश्यक व्यवस्था मिलाउनु पर्नेछ ।
साथै, इजाजतपत्रप्राप्त बैंक तथा वित्तीय संस्थाले आफ्नो संस्थामा रहेको रु. ५ लाख रुपैयाँसम्मको व्यक्तिगत बचत तथा मुद्दती निक्षेपको रकम र त्यस्ता निक्षेपकर्ताको संख्यात्मक विवरण त्रैमासिक रुपमा त्रैमास समाप्त भएको एक महिनाभित्र निक्षेप तथा कर्जा सुरक्षण कोषलाई उपलब्ध गराउनु पर्नेछ ।
Controlled English translation
A bank or financial institution licensed by this Bank shall arrange for protection, through the Deposit and Credit Guarantee Fund, of deposits up to NPR 500,000 held in savings and fixed accounts in the name of a natural person.
In addition, the licensed bank or financial institution shall provide to the Deposit and Credit Guarantee Fund, quarterly within one month after quarter-end, the amount of individual savings and fixed deposits up to NPR 500,000 held with it and the number of such depositors.
विदेशी लगानीकर्ताले नेपालभित्र लगानी गरी आर्जन गरेको लाभांश रकम सम्बन्धित देशको सरकारी निकाय वा केन्द्रीय बैंकको सहमतिमा बैंक तथा वित्तीय संस्थामा मुद्दती खाता खोली जम्मा गर्न सक्ने र सो निक्षेप तथा निक्षेपबाट आर्जित ब्याजको रिपाट्रिएशन (Repatriation) देहायको शर्तमा विदेशी विनिमय व्यवस्थापन विभागबाट स्वीकृति लिएर मात्र गर्न पाउने व्यवस्था कायम गरिएको छ:
शर्तहरु:
(१) विनिमय दर, ब्याजदर लगायतका कुनै पनि जोखिम सम्बन्धित लगानीकर्ताले नै बहन गर्नु पर्ने ।
(२) यस्तो मुद्दती निक्षेपको अवधि कम्तीमा १ वर्षको हुनु पर्ने र त्यस्तो निक्षेपको धितोमा कुनै किसिमको कर्जा लिन नपाउने ।
(३) यस्तो निक्षेप खाता खोल्नु अघि यस बैंकको विदेशी विनिमय व्यवस्थापन विभागको पूर्व स्वीकृति लिनुपर्ने ।
(४) यस्तो निक्षेप तथा ब्याजको अर्धवार्षिक विवरण यस बैंकको विदेशी विनिमय व्यवस्थापन विभागमा पेश गर्नु पर्ने ।
Controlled English translation
A foreign investor may deposit dividends earned from investment in Nepal in a fixed-deposit account with a bank or financial institution with the consent of the Government authority or central bank of the concerned country. Repatriation of such deposit and interest earned thereon shall be permitted only after obtaining approval from the Foreign Exchange Management Department, subject to the following conditions:
(1) all risks, including exchange-rate and interest-rate risk, shall be borne by the investor;
(2) the fixed deposit shall have a minimum term of one year and no loan may be obtained against that deposit;
(3) prior approval of the Foreign Exchange Management Department of this Bank shall be obtained before opening the deposit account;
(4) a half-yearly statement of such deposits and interest shall be submitted to the Foreign Exchange Management Department of this Bank.
(१) यस बैंकबाट यसअघि जारी गरिएका देहायका निर्देशनहरु खारेज गरिएको छ :-
एकीकृत निर्देशन, २०८१ को वित्तीय स्रोत संकलन सम्बन्धी व्यवस्था इ.प्रा. निर्देशन नं. १६/०८१ बाट जारी गरिएको निर्देशन तथा सोपश्चात् मिति २०८२ माघ २ सम्म जारी भएका यसै विषयसँग सम्बन्धित सम्पूर्ण परिपत्रहरु ।
(२) उपबुँदा (१) बमोजिम खारेज गरिएका निर्देशन तथा परिपत्र बमोजिम भए गरेका काम कारवाही यसै निर्देशन बमोजिम भए गरेको मानिनेछ ।
Controlled English translation
(1) The following directives previously issued by this Bank are hereby repealed:
the directive issued as Directive No. 16/081 under the provisions relating to mobilisation of financial resources in the Unified Directives, 2081, and all circulars relating to the same subject issued thereafter up to Magh 2, 2082.
(2) Any acts or actions done or taken pursuant to the directives and circulars repealed under sub-clause (1) shall be deemed to have been done or taken pursuant to this Directive.
Original Nepali text is authoritative. English is a controlled facilitative translation and is not an official Nepal Rastra Bank translation.
In case of inconsistency, ambiguity or difference, the official Nepali Directive and applicable Nepal Rastra Bank circulars prevail.
C.M. & Associates is not affiliated with, approved by or endorsed by Nepal Rastra Bank. This material is provided for information and reference only and does not constitute legal, regulatory, tax or professional advice.
Technical controls cannot guarantee prevention of screenshots or copying.